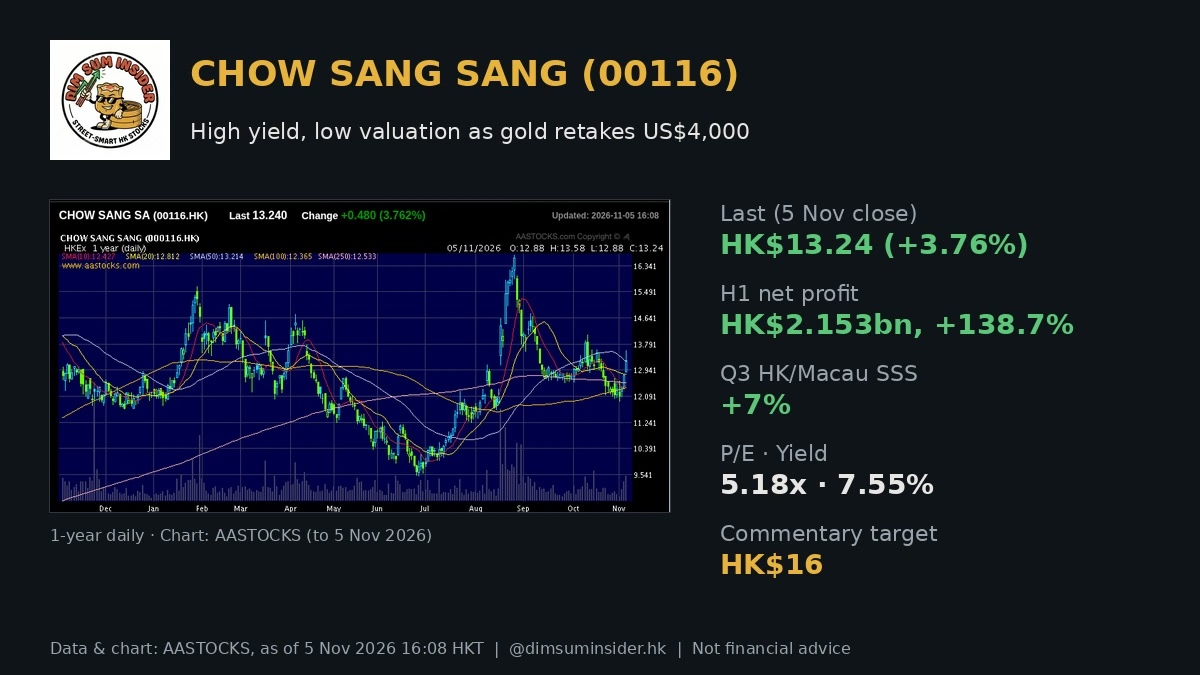
Chow Sang Sang (00116), listed as CHOW SANG SANG on AASTOCKS, jumped 3.76% to HK$13.24 on Thursday 5 Nov as gold climbed back to US$4,000/oz and Hong Kong stocks rallied. This Chow Sang Sang 00116 stock analysis asks whether a jeweller earning record profits, still growing same-store sales and trading near 5x earnings with a 7.6% yield is a value opportunity or a gold-price trap.
Market commentary notes call it high yield, low valuation and suggest accumulating at current prices with a HK$16 target. We think the risk-reward is attractive, with the gold price as the swing factor.
Key takeaways
- Record first half. H1 2026 revenue HK$12.878bn (+16.7%) and net profit HK$2.153bn (+138.7%), helped by higher gold prices. The first interim dividend rose 33.3% to 28 cents.
- Sales still growing in Q3. Even with gold well off its early-year level, Q3 retail sales rose 3%. Hong Kong and Macau same-store sales (SSS) rose 7%, mainland SSS rose 4%, and Taiwan and other regions were also positive.
- Fewer, better stores. 739 points of sale at end-September, 37 fewer than at end-June. The group is focusing on tier-2-and-above mainland cities and upgrading shops.
- Gold is back at US$4,000. The World Gold Council (WGC) reports central banks bought a net 321 tonnes in Q3, up 42% YoY, the fastest growth since end-2024.
- Cheap on AASTOCKS numbers. P/E 5.18x (TTM 3.00x), P/B 0.62x against NAV of HK$21.53, and yield 7.55% (TTM 8.08%).
- Commentary view. Trailing P/E under 5x, about 3x forward; trailing yield about 7.84%, forward near 10%; accumulate, target HK$16.
Gold: a double-edged sword for jewellers
Chow Sang Sang shares peaked at HK$16.69 in late August, then fell with gold. Investors worried that jewellers holding large gold inventories would see short-term margin pressure and could need inventory write-downs. The stock touched HK$11.93 on Monday before rebounding.
Market commentary notes argue a gold pullback cuts both ways. Lower prices bring back shoppers who had been put off by high prices, and news reports describe more customers in jewellery shops recently. The notes also see the US midterm results, which left the Republicans without control of either chamber, as limiting further large fiscal expansion and tax cuts. That could ease US Treasury yields and the US dollar, which tends to support both stocks and gold.
The longer-term gold story remains supported by central bank buying: 321 tonnes net in Q3 according to the WGC, +42% YoY.
Chow Sang Sang H1 2026 results and Q3 update
| Item | H1 2026 | Change |
|---|---|---|
| Revenue | HK$12.878bn | +16.7% YoY |
| Net profit | HK$2.153bn | +138.7% YoY |
| First interim dividend | HK$0.28 | +33.3% YoY |
| Q3 2026 operating metric | Change / figure |
|---|---|
| Retail sales value | +3% |
| Hong Kong & Macau same-store sales | +7% |
| Mainland China same-store sales | +4% |
| Taiwan and other regions | Positive growth |
| Points of sale (end-Sep) | 739 (−37 vs end-June) |
Our read: positive same-store sales in every region, after a quarter in which gold was volatile, suggest demand is holding up. Closing 37 stores while targeting larger cities should support productivity per store.
Chow Sang Sang 00116 stock analysis: valuation
| Metric | Chow Sang Sang (00116) |
|---|---|
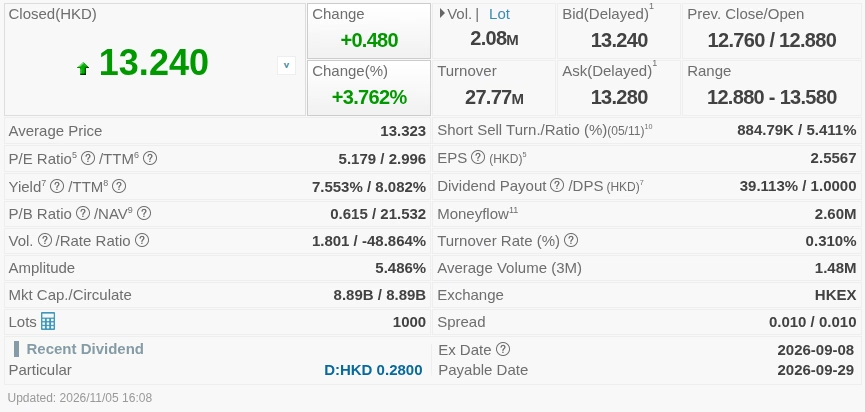
| Last price (2026/11/05 close) | HK$13.240 |
| Day change | +HK$0.480 (+3.762%) |
| Prev close / open | HK$12.760 / HK$12.880 |
| Day range | HK$12.880 – 13.580 |
| 52-week range | HK$9.480 – 16.690 |
| Market cap | HK$8.89B |
| P/E / TTM P/E | 5.179x / 2.996x (EPS HK$2.5567) |
| P/B (NAV HK$21.532) | 0.615x |
| Dividend yield / TTM | 7.553% / 8.082% (DPS HK$1.00) |
| Volume / turnover | 2.08M / HK$27.77M |
| Market commentary notes | Figure |
|---|---|
| Reference close | HK$12.76 (2026/11/04, +3.1%) |
| Earlier call | Recommended at HK$10.76 in June, target HK$13.40 (reached) |
| Trailing P/E | Under 5x, below peers |
| Forward P/E | About 3x |
| Trailing / forward yield | ~7.84% / near 10% |
| Full-year profit outlook | High double-digit growth |
| Strategy / target | Accumulate at current price / HK$16 (~20.8% above HK$13.24) |
What the numbers tell us (our analysis):
- Below book value. At 0.62x P/B the market prices the company well under its HK$21.53 NAV, unusual for a profitable, dividend-paying retailer.
- Income support. A 7.55% yield on HK$1.00 DPS pays holders to wait. AASTOCKS shows a dividend payout of about 39%, leaving room for the payout to grow.
- Room to the high. At HK$13.24 the stock is about 21% below its 52-week high of HK$16.69 and 40% above the HK$9.48 low.
Technical analysis: back above all key averages
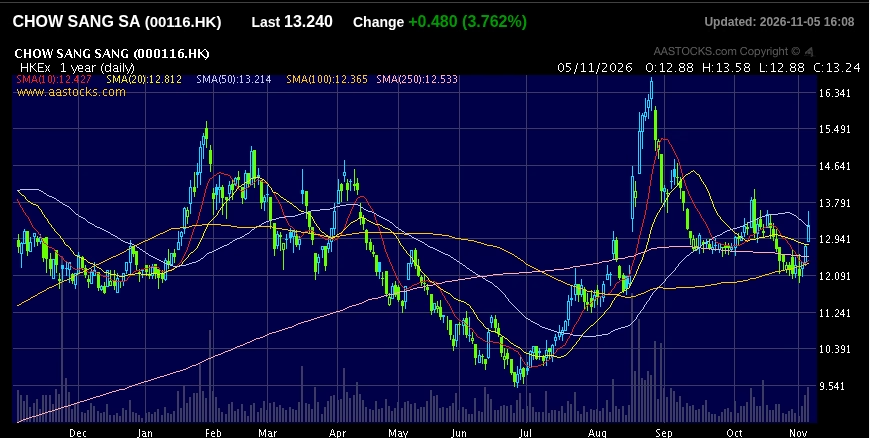
The AASTOCKS one-year daily chart shows a spike to about HK$15.5 in February, a slide to the HK$9.48 low in early July, then a sharp rally to HK$16.69 in late August. The stock then pulled back and spent October drifting around HK$12–13 before Thursday’s jump.
- Moving averages. The close of 13.24 is above SMA10 12.427, SMA100 12.365, SMA250 12.533, SMA20 12.812 and, just, SMA50 13.214.
- Momentum. RSI(14) is 57.2, firm but not overbought. Thursday’s intraday high was HK$13.58.
- Support. HK$12.81 (SMA20), then HK$12.37–12.53 (SMA100/SMA250), then HK$11.93 (Monday’s low).
- Resistance. HK$13.58 (day high), then around HK$14.6 (September rebound zone), then HK$16.0 (commentary target) and HK$16.69 (52-week high).
Risks
- Gold price. A fresh fall in gold could hit margins and force inventory write-downs; the first-half profit surge was partly gold-driven.
- Tough comparisons. A +138.7% profit jump sets a high base for next year.
- Consumer demand. Mainland spending and Hong Kong tourist flows can turn quickly.
- Store network. Fewer stores (−37 in Q3) must be offset by higher sales per store.
- Just above SMA50. A close back below HK$13.21 would weaken the breakout.
- Estimates can change. Forward P/E, yield and targets are views, not guarantees.
The DimSumInsider take
Chow Sang Sang combines record profits, positive same-store sales across regions and a sub-book valuation with a 7.6% yield. Gold is the key variable, but the stock already priced in much of the pullback. We agree with the market commentary notes’ stance: accumulating at current prices looks reasonable, with HK$16 as the target. We would want the price to hold above SMA20 (HK$12.81) and would reassess below the HK$11.93 low.
FAQ
What were Chow Sang Sang’s H1 2026 results?
Revenue rose 16.7% to HK$12.878bn and net profit rose 138.7% to HK$2.153bn. The first interim dividend rose 33.3% to 28 cents.
How did Chow Sang Sang trade in Q3 2026?
Retail sales rose 3%. Hong Kong and Macau same-store sales rose 7%, mainland same-store sales rose 4%, and Taiwan and other regions also grew. There were 739 points of sale at end-September, 37 fewer than at end-June.
How does the gold price affect Chow Sang Sang?
Higher gold lifts revenue and inventory gains but can deter buyers. A falling price can squeeze margins and trigger write-downs, but it also brings price-sensitive shoppers back.
What is Chow Sang Sang’s valuation?
According to AASTOCKS as of the 2026/11/05 close: HK$13.24, P/E 5.18x (TTM 3.00x), P/B 0.62x, yield 7.55% (TTM 8.08%) and market cap HK$8.89B. Market commentary notes put the forward P/E at about 3x and the forward yield near 10%.
What levels matter for 00116?
Support is at HK$12.81, then HK$12.37–12.53, then HK$11.93. Resistance is at HK$13.58, then about HK$14.6, then HK$16.0 and HK$16.69.
Disclaimer: For information only. Based on public market commentary notes, company results and operating updates as reported, World Gold Council data, and AASTOCKS data as of 2026/11/05 16:08 HKT (market Closed); data may be delayed. Forward P/E, yields and targets are forward-looking estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
Leave a Reply