Tag: Valuation

  • Chow Sang Sang (00116): High Yield, Low Valuation as Gold Retakes US$4,000

    Chow Sang Sang (00116): High Yield, Low Valuation as Gold Retakes US$4,000

    Chow Sang Sang (00116), listed as CHOW SANG SANG on AASTOCKS, jumped 3.76% to HK$13.24 on Thursday 5 Nov as gold climbed back to US$4,000/oz and Hong Kong stocks rallied. This Chow Sang Sang 00116 stock analysis asks whether a jeweller earning record profits, still growing same-store sales and trading near 5x earnings with a 7.6% yield is a value opportunity or a gold-price trap.

    Market commentary notes call it high yield, low valuation and suggest accumulating at current prices with a HK$16 target. We think the risk-reward is attractive, with the gold price as the swing factor.
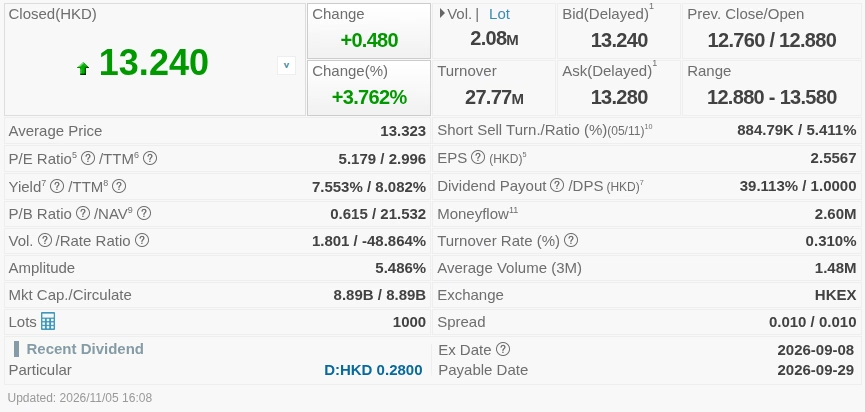
    Chow Sang Sang (00116) detailed quote on AASTOCKS, 5 Nov 2026 16:08 HKT
    Source: AASTOCKS, as of 5 Nov 2026 16:08 HKT

    Key takeaways

    • Record first half. H1 2026 revenue HK$12.878bn (+16.7%) and net profit HK$2.153bn (+138.7%), helped by higher gold prices. The first interim dividend rose 33.3% to 28 cents.
    • Sales still growing in Q3. Even with gold well off its early-year level, Q3 retail sales rose 3%. Hong Kong and Macau same-store sales (SSS) rose 7%, mainland SSS rose 4%, and Taiwan and other regions were also positive.
    • Fewer, better stores. 739 points of sale at end-September, 37 fewer than at end-June. The group is focusing on tier-2-and-above mainland cities and upgrading shops.
    • Gold is back at US$4,000. The World Gold Council (WGC) reports central banks bought a net 321 tonnes in Q3, up 42% YoY, the fastest growth since end-2024.
    • Cheap on AASTOCKS numbers. P/E 5.18x (TTM 3.00x), P/B 0.62x against NAV of HK$21.53, and yield 7.55% (TTM 8.08%).
    • Commentary view. Trailing P/E under 5x, about 3x forward; trailing yield about 7.84%, forward near 10%; accumulate, target HK$16.

    Gold: a double-edged sword for jewellers

    Chow Sang Sang shares peaked at HK$16.69 in late August, then fell with gold. Investors worried that jewellers holding large gold inventories would see short-term margin pressure and could need inventory write-downs. The stock touched HK$11.93 on Monday before rebounding.

    Market commentary notes argue a gold pullback cuts both ways. Lower prices bring back shoppers who had been put off by high prices, and news reports describe more customers in jewellery shops recently. The notes also see the US midterm results, which left the Republicans without control of either chamber, as limiting further large fiscal expansion and tax cuts. That could ease US Treasury yields and the US dollar, which tends to support both stocks and gold.

    The longer-term gold story remains supported by central bank buying: 321 tonnes net in Q3 according to the WGC, +42% YoY.

    Chow Sang Sang H1 2026 results and Q3 update

    ItemH1 2026Change
    RevenueHK$12.878bn+16.7% YoY
    Net profitHK$2.153bn+138.7% YoY
    First interim dividendHK$0.28+33.3% YoY
    Source: company results as reported in market commentary notes. AASTOCKS lists the HK$0.28 dividend with ex-date 2026-09-08, payable 2026-09-29.
    Q3 2026 operating metricChange / figure
    Retail sales value+3%
    Hong Kong & Macau same-store sales+7%
    Mainland China same-store sales+4%
    Taiwan and other regionsPositive growth
    Points of sale (end-Sep)739 (−37 vs end-June)
    Source: company Q3 operational update as reported in market commentary notes.

    Our read: positive same-store sales in every region, after a quarter in which gold was volatile, suggest demand is holding up. Closing 37 stores while targeting larger cities should support productivity per store.

    Chow Sang Sang 00116 stock analysis: valuation

    MetricChow Sang Sang (00116)
    Last price (2026/11/05 close)HK$13.240
    Day change+HK$0.480 (+3.762%)
    Prev close / openHK$12.760 / HK$12.880
    Day rangeHK$12.880 – 13.580
    52-week rangeHK$9.480 – 16.690
    Market capHK$8.89B
    P/E / TTM P/E5.179x / 2.996x (EPS HK$2.5567)
    P/B (NAV HK$21.532)0.615x
    Dividend yield / TTM7.553% / 8.082% (DPS HK$1.00)
    Volume / turnover2.08M / HK$27.77M
    Data: AASTOCKS, updated 2026/11/05 16:08 HKT, market Closed; quotes delayed.
    Market commentary notesFigure
    Reference closeHK$12.76 (2026/11/04, +3.1%)
    Earlier callRecommended at HK$10.76 in June, target HK$13.40 (reached)
    Trailing P/EUnder 5x, below peers
    Forward P/EAbout 3x
    Trailing / forward yield~7.84% / near 10%
    Full-year profit outlookHigh double-digit growth
    Strategy / targetAccumulate at current price / HK$16 (~20.8% above HK$13.24)
    Source: market commentary notes (forward-looking views and estimates, not AASTOCKS data). Commentary figures were based on the HK$12.76 close; today’s AASTOCKS close is HK$13.24.

    What the numbers tell us (our analysis):

    • Below book value. At 0.62x P/B the market prices the company well under its HK$21.53 NAV, unusual for a profitable, dividend-paying retailer.
    • Income support. A 7.55% yield on HK$1.00 DPS pays holders to wait. AASTOCKS shows a dividend payout of about 39%, leaving room for the payout to grow.
    • Room to the high. At HK$13.24 the stock is about 21% below its 52-week high of HK$16.69 and 40% above the HK$9.48 low.

    Technical analysis: back above all key averages
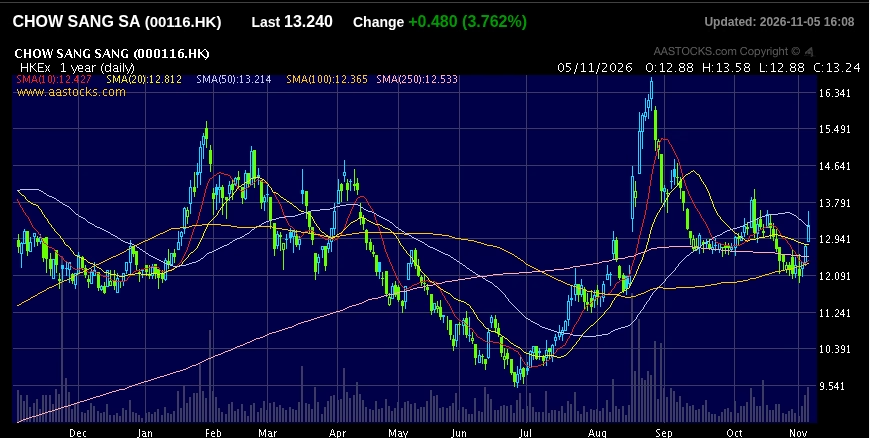
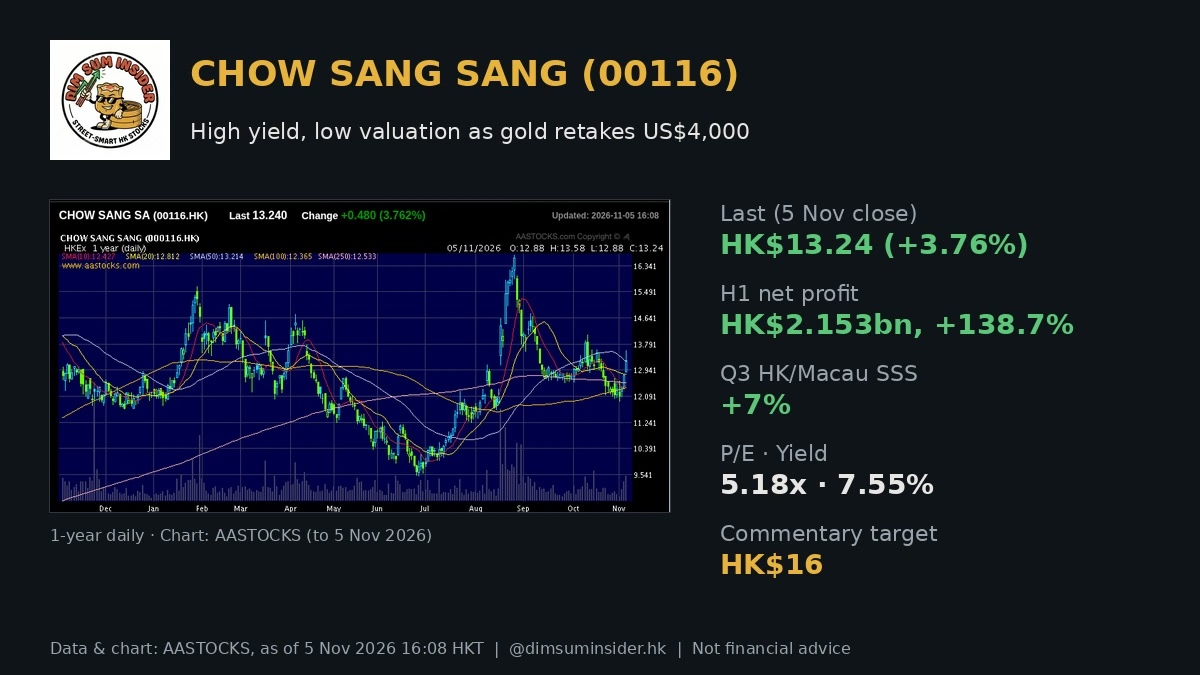
    Chow Sang Sang (00116) one-year daily chart on AASTOCKS
    Source: AASTOCKS, as of 5 Nov 2026 16:08 HKT; 1-year daily chart

    The AASTOCKS one-year daily chart shows a spike to about HK$15.5 in February, a slide to the HK$9.48 low in early July, then a sharp rally to HK$16.69 in late August. The stock then pulled back and spent October drifting around HK$12–13 before Thursday’s jump.

    • Moving averages. The close of 13.24 is above SMA10 12.427, SMA100 12.365, SMA250 12.533, SMA20 12.812 and, just, SMA50 13.214.
    • Momentum. RSI(14) is 57.2, firm but not overbought. Thursday’s intraday high was HK$13.58.
    • Support. HK$12.81 (SMA20), then HK$12.37–12.53 (SMA100/SMA250), then HK$11.93 (Monday’s low).
    • Resistance. HK$13.58 (day high), then around HK$14.6 (September rebound zone), then HK$16.0 (commentary target) and HK$16.69 (52-week high).

    Risks

    • Gold price. A fresh fall in gold could hit margins and force inventory write-downs; the first-half profit surge was partly gold-driven.
    • Tough comparisons. A +138.7% profit jump sets a high base for next year.
    • Consumer demand. Mainland spending and Hong Kong tourist flows can turn quickly.
    • Store network. Fewer stores (−37 in Q3) must be offset by higher sales per store.
    • Just above SMA50. A close back below HK$13.21 would weaken the breakout.
    • Estimates can change. Forward P/E, yield and targets are views, not guarantees.

    The DimSumInsider take

    Chow Sang Sang combines record profits, positive same-store sales across regions and a sub-book valuation with a 7.6% yield. Gold is the key variable, but the stock already priced in much of the pullback. We agree with the market commentary notes’ stance: accumulating at current prices looks reasonable, with HK$16 as the target. We would want the price to hold above SMA20 (HK$12.81) and would reassess below the HK$11.93 low.

    FAQ

    What were Chow Sang Sang’s H1 2026 results?

    Revenue rose 16.7% to HK$12.878bn and net profit rose 138.7% to HK$2.153bn. The first interim dividend rose 33.3% to 28 cents.

    How did Chow Sang Sang trade in Q3 2026?

    Retail sales rose 3%. Hong Kong and Macau same-store sales rose 7%, mainland same-store sales rose 4%, and Taiwan and other regions also grew. There were 739 points of sale at end-September, 37 fewer than at end-June.

    How does the gold price affect Chow Sang Sang?

    Higher gold lifts revenue and inventory gains but can deter buyers. A falling price can squeeze margins and trigger write-downs, but it also brings price-sensitive shoppers back.

    What is Chow Sang Sang’s valuation?

    According to AASTOCKS as of the 2026/11/05 close: HK$13.24, P/E 5.18x (TTM 3.00x), P/B 0.62x, yield 7.55% (TTM 8.08%) and market cap HK$8.89B. Market commentary notes put the forward P/E at about 3x and the forward yield near 10%.

    What levels matter for 00116?

    Support is at HK$12.81, then HK$12.37–12.53, then HK$11.93. Resistance is at HK$13.58, then about HK$14.6, then HK$16.0 and HK$16.69.


    Disclaimer: For information only. Based on public market commentary notes, company results and operating updates as reported, World Gold Council data, and AASTOCKS data as of 2026/11/05 16:08 HKT (market Closed); data may be delayed. Forward P/E, yields and targets are forward-looking estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
  • Yankuang Energy (01171): Coal Squeeze Lifts Profits, Buy in Tranches

    Yankuang Energy (01171): Coal Squeeze Lifts Profits, Buy in Tranches

    Yankuang Energy (01171), listed as YANKUANG ENER on AASTOCKS, rose 1.54% to HK$11.19 on Wednesday 4 Nov. China’s coal market has tightened: national output is down, prices have climbed for most of the year, and the heating season is starting. This Yankuang Energy 01171 stock analysis looks at whether higher coal and coal-chemical margins, shown in a 55.9% jump in nine-month profit, make the stock worth building into.

    Market commentary notes see the valuation as reasonable and suggest accumulating in tranches, with a technical target near HK$13.6. We broadly agree: earnings momentum is strong and the multiple is below its own history, but the share price is still under its 50-, 100- and 250-day averages, so staged buying makes sense.

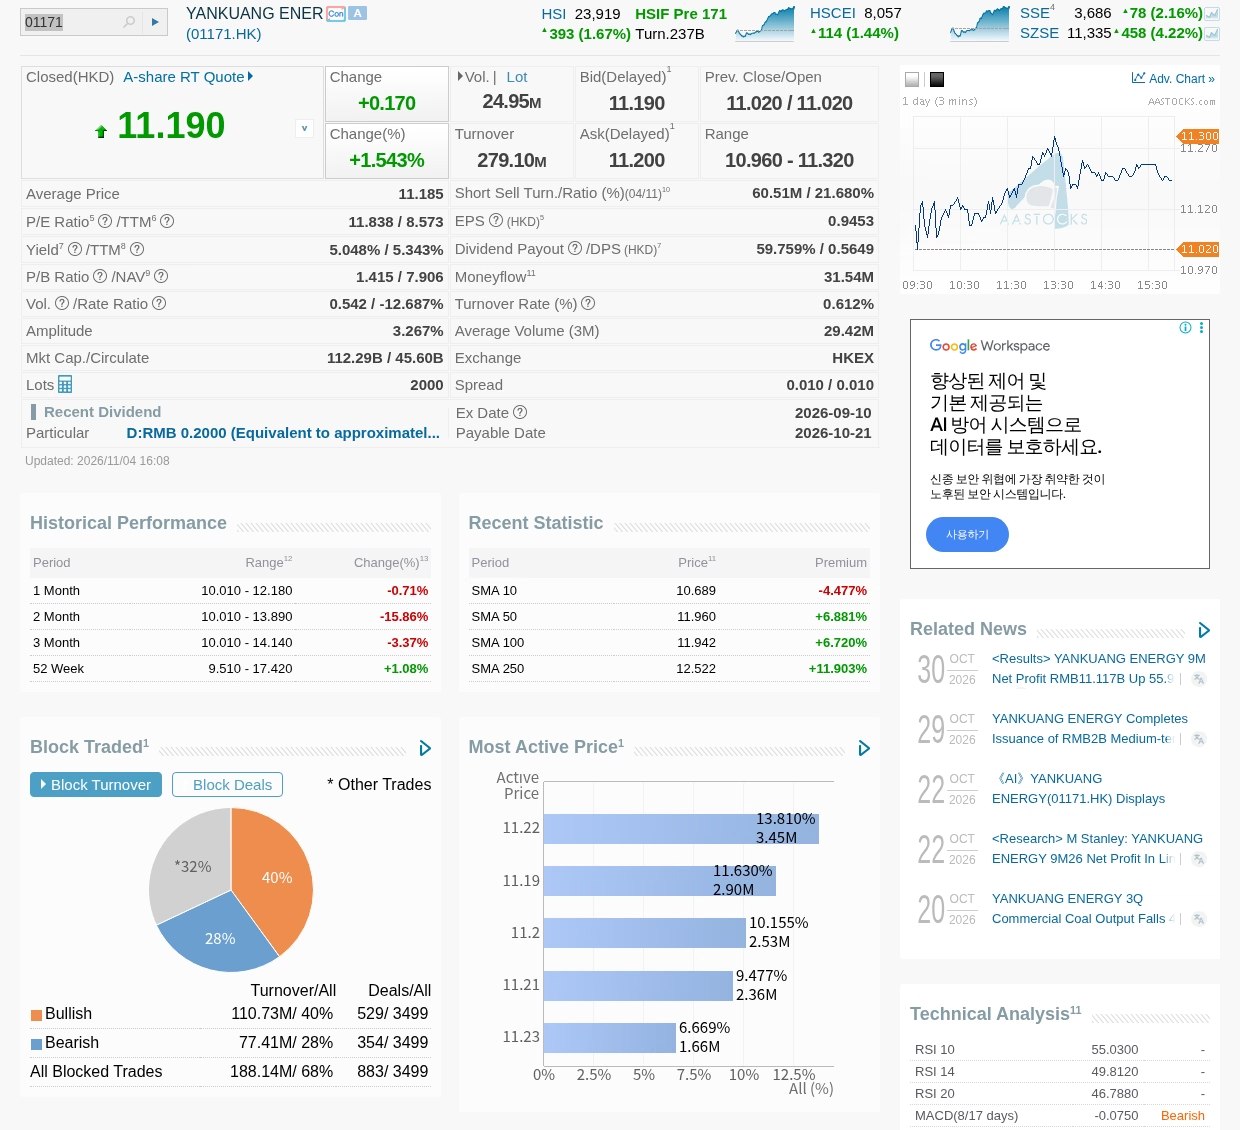
    Yankuang Energy (01171) detailed quote on AASTOCKS, 4 Nov 2026 16:08 HKT
    Source: AASTOCKS, as of 4 Nov 2026 16:08 HKT

    Key takeaways

    • Supply is shrinking. National Bureau of Statistics (NBS) data show China’s above-scale raw coal output was about 3.45bn tonnes in 9M 2026, down 3.5% YoY, after safety inspections and capacity checks idled many mines.
    • Prices are up. Market commentary notes say the Qinhuangdao 5,500 kcal thermal coal price moved back above RMB 1,000/t in October for the first time in three years, with a peak year-to-date gain of nearly 50%.
    • Industry profits jumped. NBS figures cited in the notes put 9M revenue of coal mining and washing at RMB 2.1trn (+11.9%) and profit at RMB 353.04bn (+57%).
    • Yankuang’s 9M print. Revenue RMB 117.5bn (+11.3%), gross margin 33.1% (+3.4 ppt), profit RMB 11.12bn (+55.9%), adjusted profit RMB 8.54bn (+31.1%).
    • Valuation. AASTOCKS shows P/E 11.84x (TTM 8.57x), P/B 1.42x and yield 5.05% (TTM 5.34%). Commentary notes estimate a forward P/E of about 5.9x versus a 5-year median of 7x.
    • Commentary stance. Valuation reasonable; accumulate in tranches; technical target about HK$13.6.

    China coal market: supply contraction meets the heating season

    The main driver this year has been supply. NBS data show 9M 2026 above-scale raw coal output of about 3.45bn tonnes, down 3.5% from a year earlier. Safety incidents in core producing regions led to strict safety checks and capacity reviews, and a large number of mines stopped for rectification.

    With supply and demand tightly balanced, thermal and coking coal prices have trended higher since the start of the year. Because prices rose much faster than output fell, coal miners’ revenue and profit both expanded: NBS figures for the first three quarters show coal mining and washing revenue of RMB 2.1trn (+11.9%) and profit of RMB 353.04bn (+57%).

    Heading into November:

    • Demand support. Cold air has hit the mainland, coastal power plants and northern regions have started winter stockpiling, and coal chemicals keep steady demand.
    • Supply returning slowly. Mines that were stopped are gradually restarting, and the National Energy Administration has rolled out measures to raise output. September’s output decline narrowed from August, and daily output is back above 12m tonnes.

    Our read: the heating-season restocking should hold prices up near term, but recovering supply is the main thing that could cap further gains.

    Yankuang Energy 9M 2026 results

    Yankuang is a Shandong Energy group subsidiary. It mines and sells coal, makes and sells coal chemicals, and runs logistics, equipment and power businesses. Its mining bases are in Shandong, Shaanxi–Inner Mongolia and Australia, where subsidiary Yancoal Australia (03668) is one of the country’s largest coal exporters.

    Item9M 2026Change
    RevenueRMB 117.5bn+11.3% YoY
    Coal revenueRMB 74.6bn (63.5% of total)+16.4%
    Coal-chemical revenueRMB 20.06bn (17.1% of total)+8.3%
    Gross margin33.1%+3.4 ppt
    ProfitRMB 11.12bn+55.9%
    Adjusted profitRMB 8.54bn+31.1%
    Source: company results as reported in market commentary notes.

    Coal unit economics

    Coal metric9M 2026Change
    Coal output132 Mt−3%
    Coal sales126 Mt−0.3%
    Own-produced coal sales120 Mt−1.3%
    Average coal selling priceRMB 591.88/t+16.7%
    Own-produced coal average priceRMB 587.8/t+16.8%
    Coal segment gross margin36.1%+4.8 ppt
    Source: company results as reported in market commentary notes.

    The company managed output to match the market, then raised its coal washing rate to sell more higher-value washed coal. Prices did the work: volumes were flat to slightly lower, but a 16–17% price gain pushed the coal margin up almost 5 points.

    Coal-chemical unit economics

    Coal-chemical metric9M 2026Change
    Product output and sales—Slightly lower YoY
    Average selling priceRMB 3,180/t+10.5%
    Unit cost—+5.8%
    Unit gross profitRMB 938/t+23.7%
    Source: company results as reported in market commentary notes.

    Using its own coal as feedstock cuts out middlemen and raw-material price risk. Unit costs of key products such as methanol and acetic acid fell sharply YoY according to the notes, though the segment’s overall unit cost rose 5.8%. With prices up 10.5%, unit gross profit rose 23.7%. Yankuang’s coal-chemical base has total capacity of more than 10m tonnes, including China’s first million-tonne indirect coal liquefaction demonstration unit.

    Growth projects

    • Won the Hongzhun coal mine tender, adding 406m tonnes of quality resources, including scarce high-grade coking coal.
    • Mine construction at Youfangliang and Yangjiaping is progressing; the Xinjiang 800,000-tonne olefins project is under full construction.
    • Proposed acquisition of Shandong Energy power assets, plus thermal, wind, solar and storage build-out.

    Yankuang Energy 01171 stock analysis: valuation

    MetricYankuang Energy (01171)
    Last price (2026/11/04 close)HK$11.190
    Day change+HK$0.170 (+1.543%)
    Prev close / openHK$11.020 / HK$11.020
    Day rangeHK$10.960 – 11.320
    52-week rangeHK$9.510 – 17.420
    Market cap / circulatingHK$112.29B / HK$45.60B
    P/E / TTM P/E11.838x / 8.573x
    P/B (NAV HK$7.906)1.415x
    Dividend yield / TTM5.048% / 5.343% (DPS HK$0.5649)
    Volume / turnover24.95M / HK$279.10M
    Data: AASTOCKS, updated 2026/11/04 16:08 HKT, market Closed; quotes delayed.
    Market commentary notesFigure
    5-year median P/E7x
    Forward P/E estimate~5.9x
    Position in band~0.4 standard deviation below median
    Valuation viewReasonable
    StrategyAccumulate in tranches
    Technical target~HK$13.6 (early-September high), ~21.5% above HK$11.19
    Source: market commentary notes (forward-looking views and estimates, not AASTOCKS data).

    What the numbers tell us (our analysis):

    • Earnings are catching up with the price. The AASTOCKS trailing P/E of 8.57x is backward-looking. The ~5.9x forward estimate assumes the higher 2026 earnings run-rate holds, which depends on coal prices.
    • Income support. A 5.05% yield (5.34% TTM) pays holders to wait. AASTOCKS lists the latest dividend as RMB 0.20, ex-date 2026-09-10.
    • Well off the highs. At HK$11.19 the stock is about 36% below its 52-week high of HK$17.42 and 18% above the HK$9.51 low.

    Technical analysis: back above the short-term averages

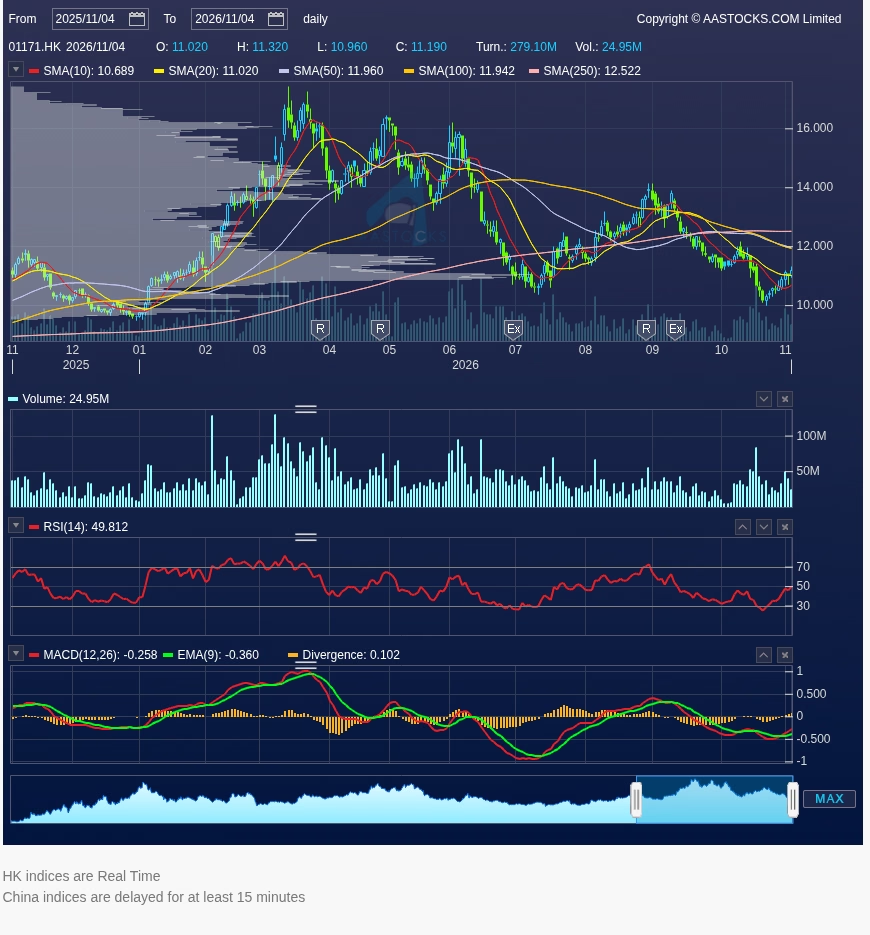
    Yankuang Energy (01171) one-year daily chart on AASTOCKS
    Source: AASTOCKS, as of 4 Nov 2026 16:08 HKT; 1-year daily chart

    The AASTOCKS one-year daily chart (4 Nov 2025 to 4 Nov 2026) shows a rally to the HK$17.42 high in spring, a slide through the summer, a recovery to around HK$14 in early September, then a drop to near HK$10 in late October. The stock has bounced since.

    • Moving averages. The price of 11.19 is above SMA10 10.689 and SMA20 11.020, but below SMA100 11.942, SMA50 11.960 and SMA250 12.522.
    • Momentum. RSI(14) is 49.8, neutral. MACD(12,26) is −0.258 against a signal of −0.360 (divergence +0.102), a bullish crossover below zero. Commentary notes also see negative momentum fading and say a break above the top of the falling channel could open a run at the early-September high of about HK$13.6.
    • Support. HK$11.02 (SMA20 and prev close), then HK$10.69 (SMA10), then the 1-month low of HK$10.01.
    • Resistance. HK$11.32 (day high), then HK$11.94–11.96 (SMA100/SMA50), then HK$12.52 (SMA250), then HK$13.6.

    Risks

    • Supply comes back. Restarting mines and NEA measures to raise output could cool prices after the heating season.
    • Coal price sensitivity. Most of the profit gain came from price, not volume; a price reversal would hit margins quickly.
    • Volumes are soft. Coal output fell 3% and coal-chemical volumes slipped in 9M.
    • Project and deal risk. Large capex (Hongzhun, Xinjiang olefins, power assets) carries cost and execution risk.
    • Trend not yet repaired. The price is still below SMA50, SMA100 and SMA250.
    • Estimates can change. Forward P/E and targets are views, not guarantees.

    The DimSumInsider take

    Yankuang is a direct play on tighter Chinese coal supply, with coal chemicals adding a second margin lever. 9M profit up 55.9% on a 16.7% higher coal price shows the operating leverage. We agree with the commentary notes’ stance: valuation is reasonable and buying in tranches suits a cyclical name. We would add on a close above SMA50 (HK$11.96), treat HK$13.6 as the first target, and reassess below the HK$10.01 October low.

    FAQ

    Why are China coal prices rising in 2026?

    Supply has shrunk. NBS data show 9M above-scale raw coal output down 3.5% to about 3.45bn tonnes after safety checks closed many mines, while heating-season stockpiling adds demand.

    What were Yankuang Energy’s 9M 2026 results?

    Revenue rose 11.3% to RMB 117.5bn, gross margin rose 3.4 points to 33.1%, profit rose 55.9% to RMB 11.12bn, and adjusted profit rose 31.1% to RMB 8.54bn.

    How much does Yankuang make per tonne of coal chemicals?

    The average selling price rose 10.5% to RMB 3,180/t, and unit gross profit rose 23.7% to RMB 938/t.

    What is Yankuang Energy’s valuation?

    According to AASTOCKS as of the 2026/11/04 close: HK$11.19, P/E 11.84x (TTM 8.57x), P/B 1.42x, yield 5.05% and market cap HK$112.29B. Commentary notes estimate a forward P/E of about 5.9x versus a 5-year median of 7x.

    What levels matter for 01171?

    Support is at HK$11.02, then HK$10.69, then HK$10.01. Resistance is at HK$11.32, then HK$11.94–11.96, then HK$12.52, then HK$13.6.


    Disclaimer: For information only. Based on public market commentary notes, company results as reported, NBS data, and AASTOCKS data as of 2026/11/04 16:08 HKT (market Closed); data may be delayed. Forward P/E and targets are forward-looking estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
  • China Life (02628): SFISF Restart Puts Insurers Back in Play

    China Life (02628): SFISF Restart Puts Insurers Back in Play

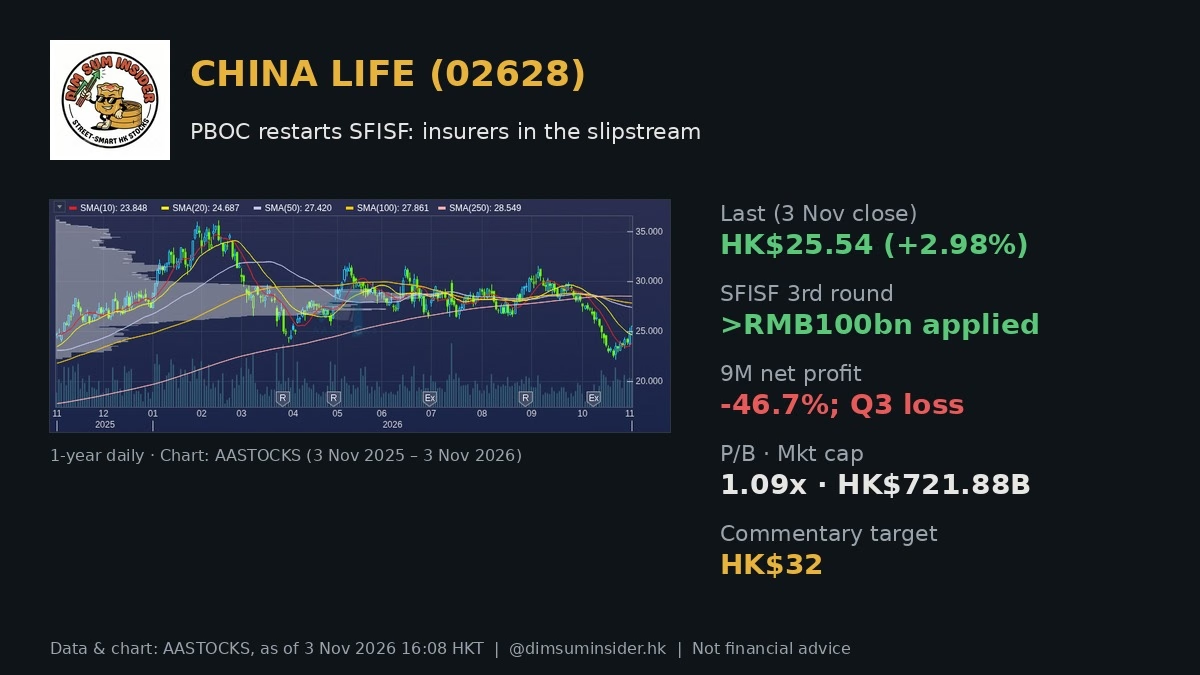
    China Life Insurance (02628), listed as CHINA LIFE on AASTOCKS, rose 2.98% to HK$25.54 on Tuesday 3 Nov, after a 3.9% gain to HK$24.80 the session before. The trigger is policy: the PBOC has restarted its Securities, Funds and Insurance companies Swap Facility (SFISF), and the third operation drew reported applications of more than RMB 100bn. This China Life 02628 stock analysis asks whether that liquidity support can outweigh a nine-month profit drop of 46.7% and a Q3 loss.

    Market commentary notes, which suggested buying at HK$26 in June, say holders can keep the stock and new buyers can buy at the current level, with a target of HK$32. We think the SFISF story is a real tailwind, but China Life’s earnings now move with the A-share market, so the stock is a leveraged bet on mainland equities holding up.

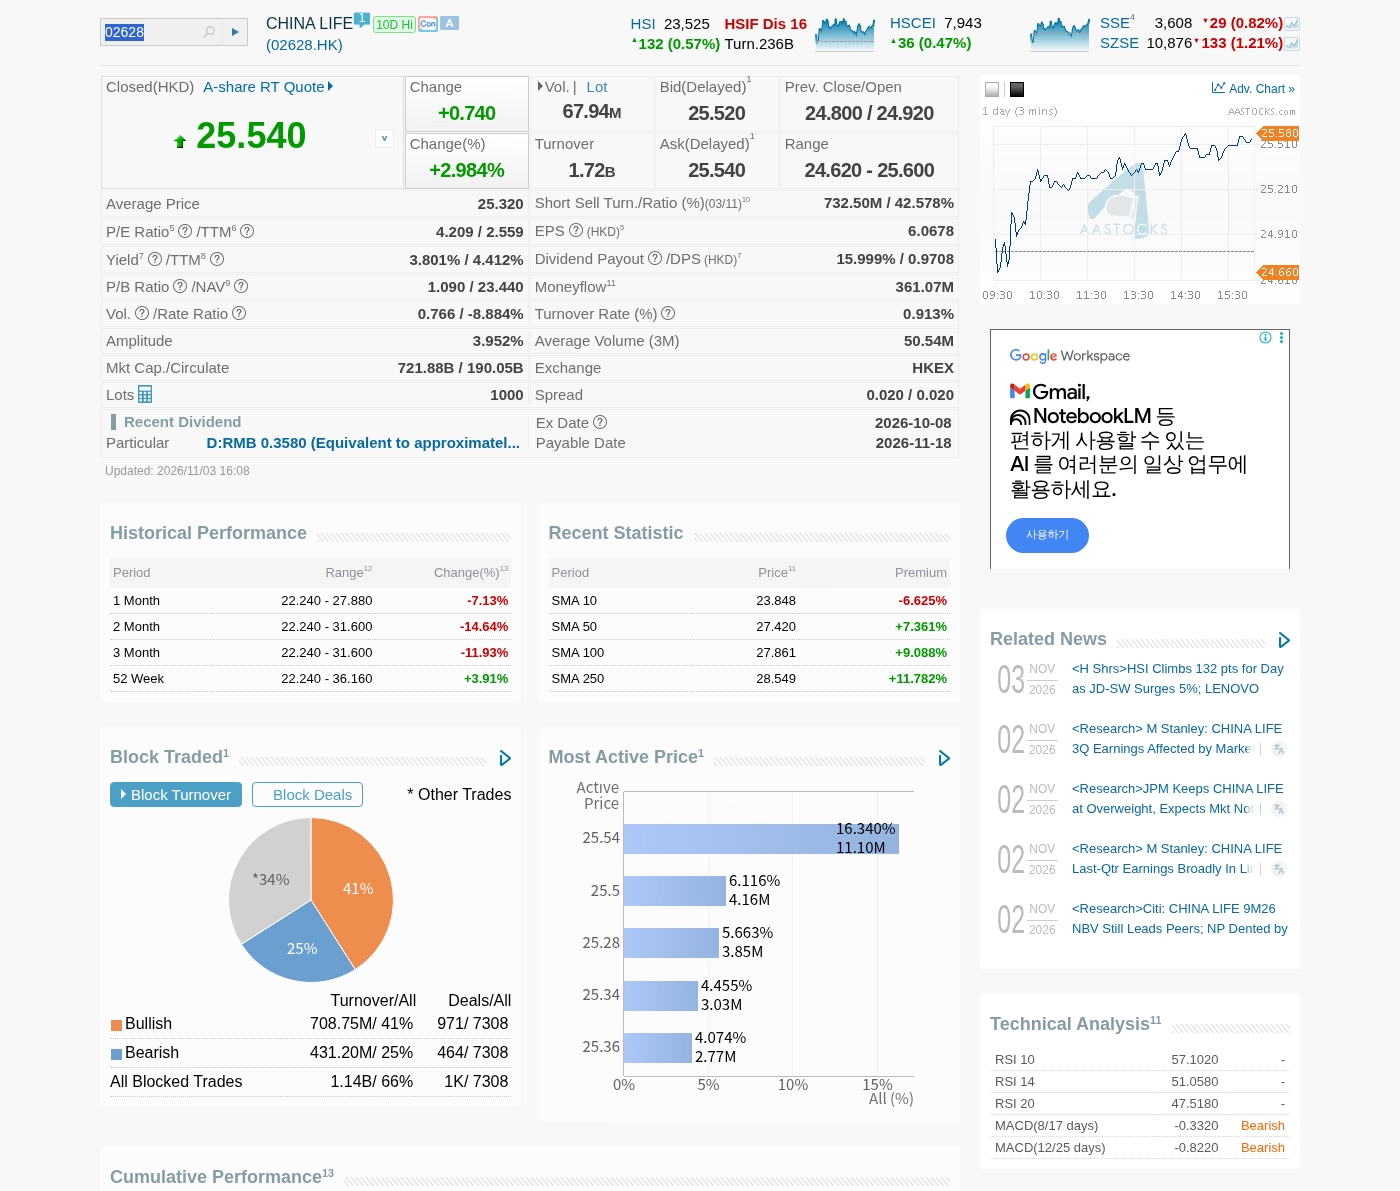
    China Life (02628) detailed quote on AASTOCKS, 3 Nov 2026 16:08 HKT
    Source: AASTOCKS, as of 3 Nov 2026 16:08 HKT

    Key takeaways

    • SFISF is back. The PBOC has started a third SFISF operation. Market commentary notes report 31 institutions applied for more than RMB 100bn, about double the RMB 50bn and RMB 55bn of the two earlier rounds.
    • Insurers benefit. Brokers and insurers are the facility’s users. Insurers are also being officially encouraged to raise equity allocations, which ties their results more closely to the stock market.
    • Profit hit by A-shares. China Life’s 9M net profit fell 46.7% to RMB 89.43bn, and Q3 alone was a loss of RMB 45.1bn, mainly due to A-share swings.
    • The core business is growing. 9M new business value rose 13%, the strongest among peers according to Morgan Stanley (as cited in the notes). Base (operating) profit rose 15.8% to RMB 94bn.
    • Valuation. AASTOCKS shows P/E 4.21x (TTM 2.56x), P/B 1.09x (NAV HK$23.44), yield 3.80% (TTM 4.41%) and a market cap of HK$721.88B.
    • Commentary stance. Holders keep; new buyers can buy at the current level; target HK$32.

    What is the SFISF? A quick explainer

    The Securities, Funds and Insurance companies Swap Facility (SFISF) was created by the People’s Bank of China in October 2024. It is one of two market-support tools launched then, and is aimed at non-bank financial firms.

    • How it works. Eligible brokers, fund managers and insurers pledge less-liquid assets they hold, such as bonds, equity ETFs and CSI 300 constituent shares, to the PBOC. In return they receive highly liquid, high-grade assets such as treasury bonds and central bank bills.
    • What the cash is for. Those high-grade assets can be pledged or sold to raise funding, but the rules say the money can only be used to invest in the stock market.
    • Why it exists. The aim is to unlock liquidity in non-bank institutions and improve their ability to buy and hold stocks and to absorb market shocks.
    • Track record. The PBOC ran two earlier operations, in October 2024 and January 2025. Market commentary notes point out that the Shanghai Composite rose by a decent margin after both.
    • This round. The third operation drew reported applications of more than RMB 100bn from 31 institutions, versus RMB 50bn and RMB 55bn in the first two. Commentary notes read the larger size as stronger support for the market.

    Why insurers like China Life benefit

    Brokers gain in an obvious way: more market activity and cheaper funding for equity positions. For insurers, the link is newer. Regulators have been encouraging insurers to put more of their assets into equities, so the relationship between stock market performance and insurers’ results has become tighter. If a bigger SFISF round helps steady the A-share market, insurers’ investment returns, and therefore reported profits, should benefit too.

    The same link works in reverse. China Life’s Q3 loss shows how fast a weak A-share market now flows through to the income statement.

    China Life 9M results at a glance

    Item9M 2026Change
    Net profitRMB 89.43bn−46.7% YoY
    Q3 net profitLoss of RMB 45.1bnMainly due to A-share falls
    New business value (NBV)—+13% YoY
    Base (operating) profitRMB 94bn+15.8% YoY
    Source: company results as reported in market commentary notes, citing a Morgan Stanley research note for NBV and base profit.

    The split is clear. The investment line, which is exposed to A-share moves, drove the profit fall. The insurance business itself is doing well: NBV growth of 13% is, according to Morgan Stanley, the best among peers. Base profit of RMB 94bn (+15.8%) is the figure commentary notes link to dividend capacity. Morgan Stanley maintains a Buy on China Life H shares with a target of HK$38.8 (as cited in the notes).

    China Life 02628 stock analysis: valuation

    MetricChina Life (02628)
    Last price (2026/11/03 close)HK$25.540
    Day change+HK$0.740 (+2.984%)
    Prev close / openHK$24.800 / HK$24.920
    Day rangeHK$24.620 – 25.600
    52-week rangeHK$22.240 – 36.160
    Market capHK$721.88B
    P/E / TTM P/E4.209x / 2.559x
    P/B (NAV HK$23.44)1.090x
    Dividend yield / TTM3.801% / 4.412% (DPS HK$0.9708)
    Volume / turnover67.94M / HK$1.72B
    Data: AASTOCKS, updated 2026/11/03 16:08 HKT, market Closed; quotes delayed.
    Commentary checkpointsFigure
    Earlier callSuggested buying at HK$26 in June
    HoldersKeep holding
    New buyersCan buy at the current level
    TargetHK$32 (~25% above HK$25.54)
    Broker view citedMorgan Stanley: Buy, target HK$38.8
    Source: market commentary notes (forward-looking views and estimates, not AASTOCKS data).

    What the numbers tell us (our analysis):

    • Low P/E, volatile earnings. A trailing P/E of 2.56x reflects a strong earnings base that is now shrinking. The 46.7% profit drop means trailing figures flatter the stock.
    • Close to book. At 1.09x NAV, the market is not paying much of a premium for the growing new-business franchise.
    • Income support. A 3.80% yield (4.41% TTM) gives holders something while they wait. AASTOCKS lists the latest dividend as RMB 0.358, ex-date 2026-10-08.
    • Back near the June entry. The price is just below the HK$26 level in the earlier call, so the original thesis has not made money yet.

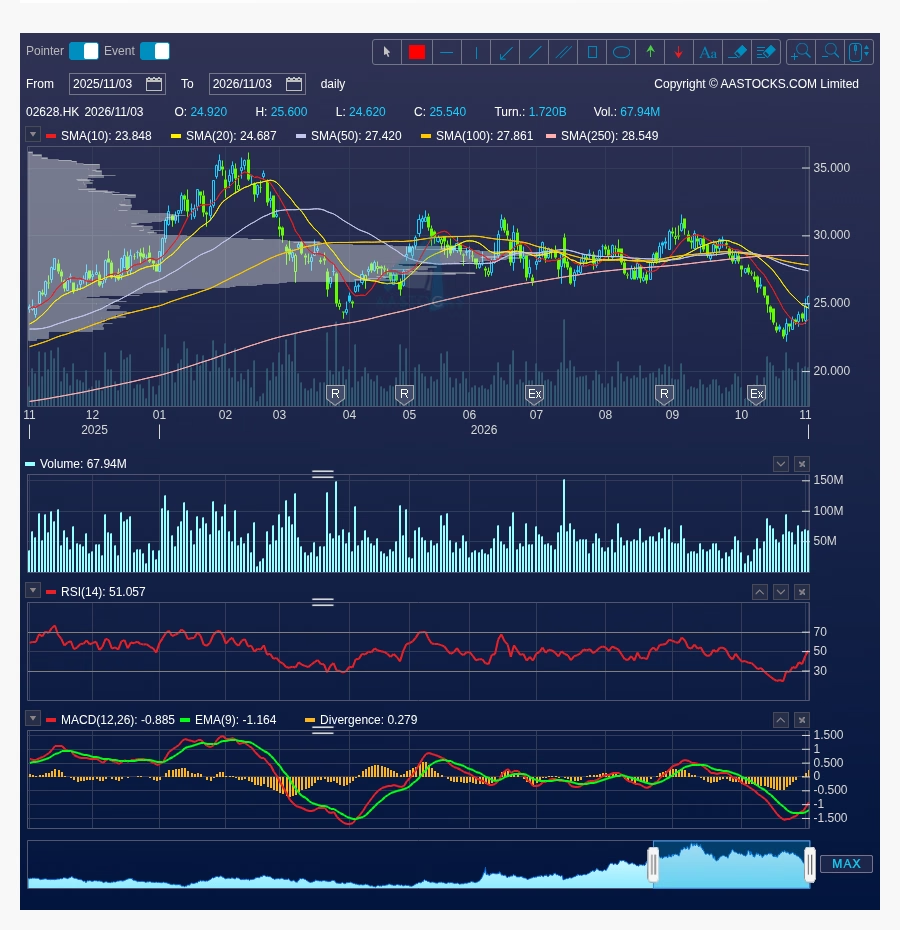
    Technical analysis: rebound from the October low

    China Life (02628) one-year daily chart on AASTOCKS
    Source: AASTOCKS, as of 3 Nov 2026 16:08 HKT; 1-year daily chart

    The AASTOCKS one-year daily chart (3 Nov 2025 to 3 Nov 2026) shows a peak near HK$36.16 in February, a long range around HK$27–31 through the summer, and a sharp drop in October to the 52-week low of HK$22.24. The stock has rebounded on two strong days.

    • Moving averages. The price of 25.54 is back above SMA10 23.848 and SMA20 24.687, but still below SMA50 27.420, SMA100 27.861 and SMA250 28.549.
    • Momentum. RSI(14) is 51.1, neutral. MACD(12,26) is −0.885 against a signal of −1.164 (divergence +0.279). That is a bullish crossover from below zero: momentum is improving, but the trend has not turned positive yet.
    • Support. HK$24.6–24.7 (day low and SMA20), then SMA10 23.85, then the HK$22.24 low.
    • Resistance. HK$25.60 (day high), HK$26 (the June entry), then HK$27.4–28.5 (SMA50/100/250), then the commentary’s HK$32 target.

    Risks

    • A-share sensitivity. Q3 showed that a weak A-share market can push China Life into a quarterly loss. Higher equity allocation makes this stronger.
    • Policy may not be enough. Earlier SFISF rounds helped sentiment, but a liquidity tool does not guarantee lasting gains.
    • Low interest rates. Falling bond yields pressure investment returns and the spread on long-dated liabilities.
    • Trend still down. The price is below SMA50, SMA100 and SMA250. A failure around HK$26–27.4 would keep the downtrend intact.
    • Estimates can change. Broker targets and commentary targets are views, not guarantees.

    The DimSumInsider take

    China Life is a clean way to express a view on mainland equities. The SFISF restart, at about double the size of earlier rounds, adds support at a time when the stock has just bounced off its 52-week low. The core business is healthy, with NBV up 13% and base profit up 15.8%, while reported profit swings with the A-share market. We agree with the commentary’s stance: holders keep, and new money can start at the current level. We would look for a close above SMA50 (HK$27.42) as confirmation, treat HK$32 as the target, and reassess if the price falls back below SMA10 (HK$23.85).

    FAQ

    What is the SFISF?

    It is the PBOC’s Securities, Funds and Insurance companies Swap Facility, launched in October 2024. Eligible brokers, funds and insurers swap bonds, equity ETFs and CSI 300 shares for treasury bonds or central bank bills, and the funding raised can only be used to invest in stocks.

    Why does the SFISF matter for China Life?

    Insurers are users of the facility and are being encouraged to hold more equities. A stronger A-share market supports insurers’ investment returns and profits.

    What were China Life’s 9M 2026 results?

    Net profit fell 46.7% to RMB 89.43bn, and Q3 was a loss of RMB 45.1bn, mainly due to A-share swings. New business value rose 13% and base profit rose 15.8% to RMB 94bn.

    What is China Life’s valuation?

    According to AASTOCKS as of the 2026/11/03 close: HK$25.54, P/E 4.21x (TTM 2.56x), P/B 1.09x, yield 3.80% (TTM 4.41%) and market cap HK$721.88B.

    What levels matter for 02628?

    Support is at HK$24.6–24.7, then HK$23.85, then HK$22.24. Resistance is at HK$25.60, then HK$26, then HK$27.4–28.5, then HK$32.


    Disclaimer: For information only. Based on public market commentary notes, company results and broker views as reported, and AASTOCKS data as of 2026/11/03 16:08 HKT (market Closed); data may be delayed. SFISF application figures are as reported, and targets are forward-looking estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
  • Shanghai Petrochemical (00338): Refining Spreads Power a Profit Turnaround

    Shanghai Petrochemical (00338): Refining Spreads Power a Profit Turnaround

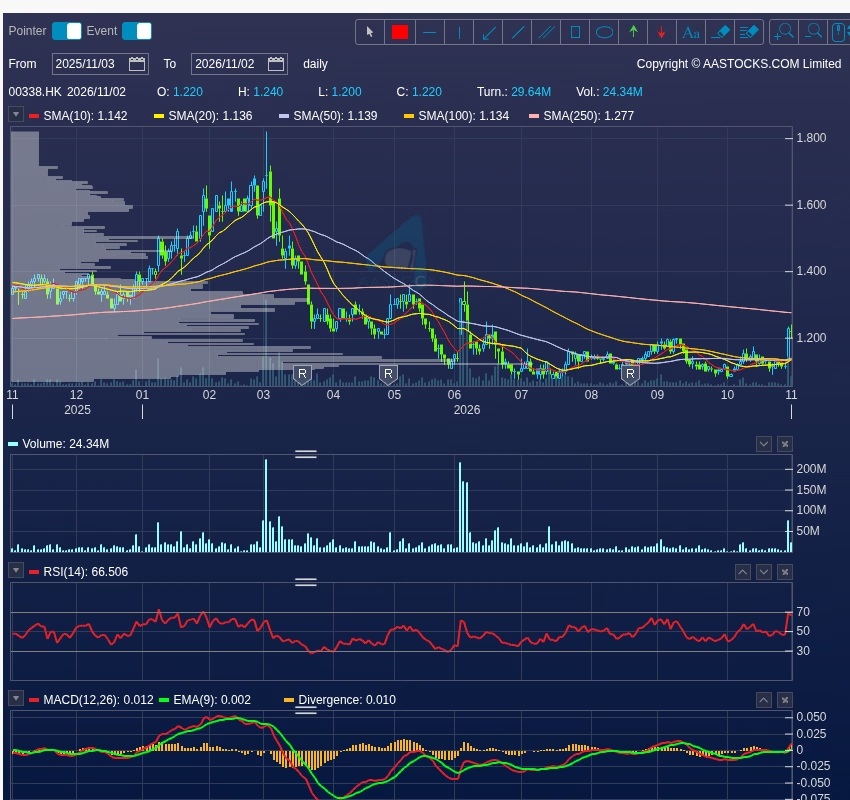
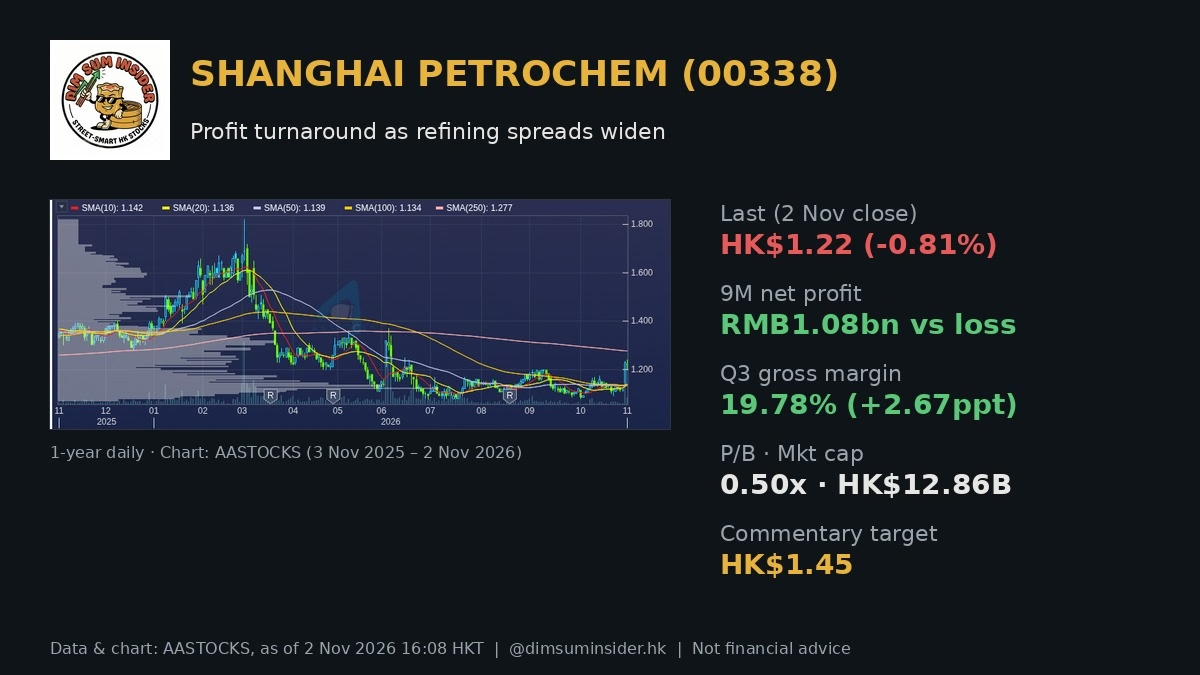
    Sinopec Shanghai Petrochemical (00338), listed as SHANGHAI PECHEM on AASTOCKS, jumped 10.3% to HK$1.23 on Friday 30 Oct after its nine-month results, then eased 0.8% to HK$1.22 on Monday 2 Nov. This Shanghai Petrochemical 00338 stock analysis asks one question: is this a real margin recovery or a one-quarter spike? The stock trades at 0.50x book and still shows “No Profit” on a trailing basis, while Q3 profit jumped about 24.6 times year on year.

    Market commentary notes see a recovery that is gathering pace. Their view: accumulate near HK$1.20, with a first target of HK$1.45. We think the turnaround is real. How long it lasts depends on refining spreads that are being held up by geopolitics.

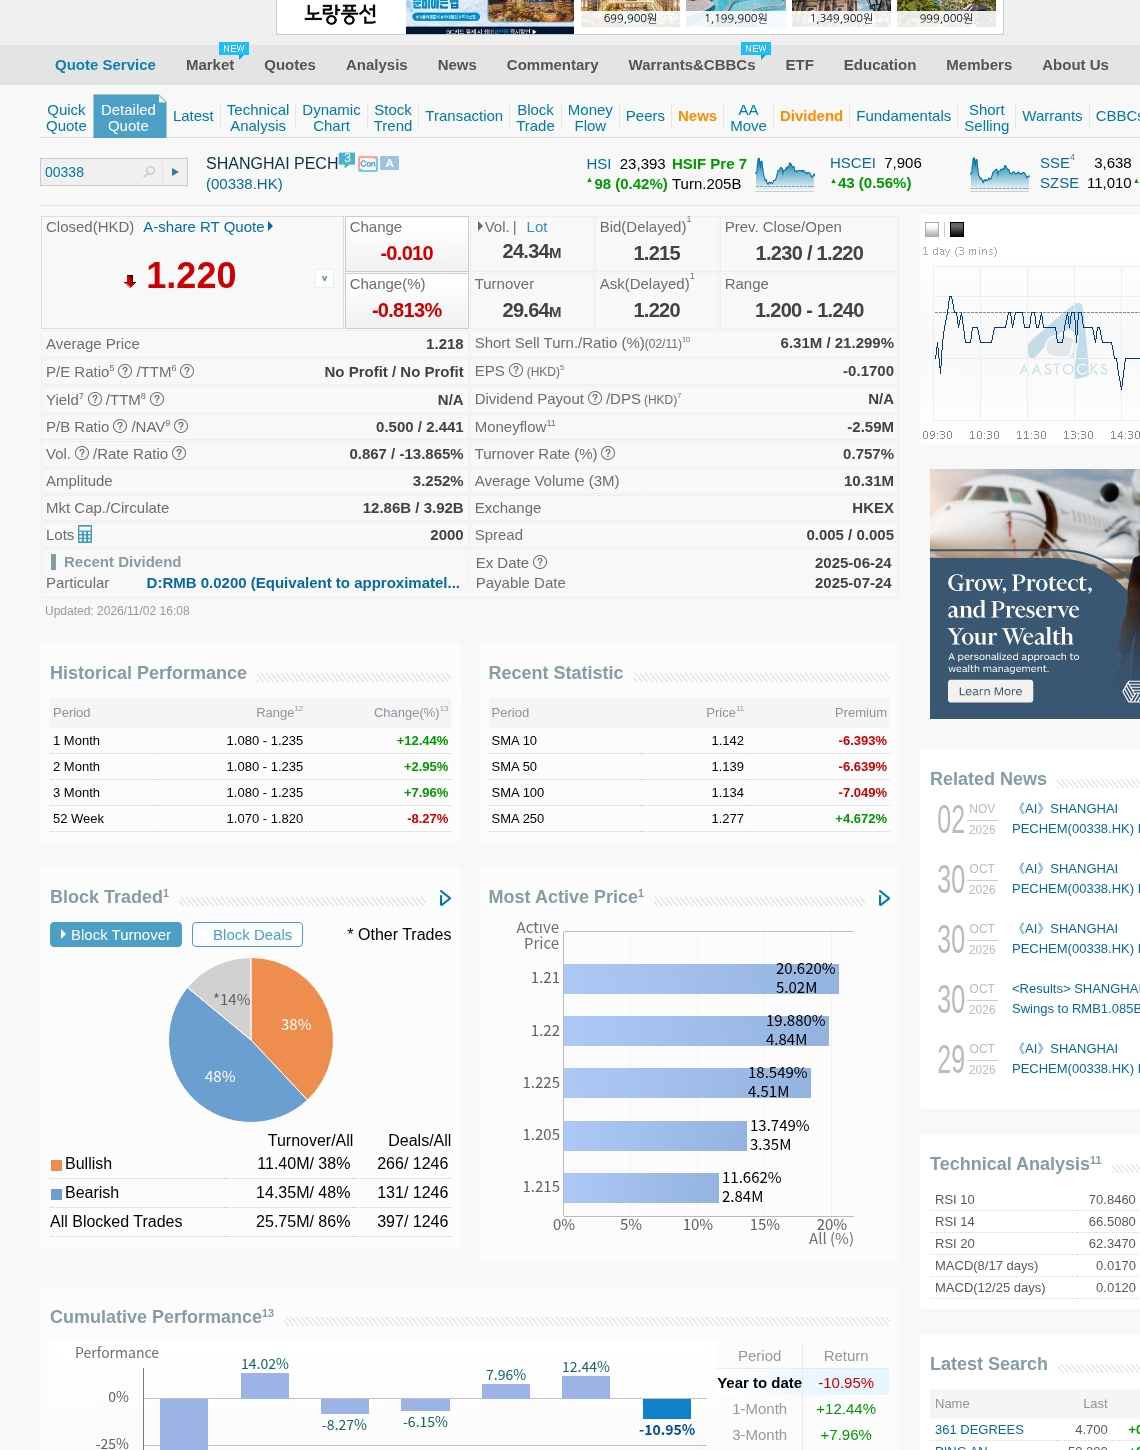
    Shanghai Petrochemical (00338) detailed quote on AASTOCKS, 2 Nov 2026 16:08 HKT
    Source: AASTOCKS, as of 2 Nov 2026 16:08 HKT

    Key takeaways

    • Back in profit. 9M net profit was RMB 1.08bn, against a loss of RMB 0.43bn a year earlier. Recurring profit was RMB 1.16bn (loss of RMB 0.39bn a year ago).
    • Q3 drove it. Q3 revenue rose 7.9% to RMB 20.86bn and profit was RMB 0.78bn, up about 24.6x year on year. That is about 2.6 times H1’s RMB 0.30bn profit.
    • Margins widened. Q3 gross margin was 19.78% (+2.67 ppt YoY, +3.92 ppt QoQ). Net margin was 3.63% (+3.47 ppt YoY, +4.26 ppt QoQ).
    • Spreads, not volume. Better refining and chemical product spreads did the work, helped by refinery outages linked to geopolitics.
    • Cheap on book. AASTOCKS shows P/B 0.50 (NAV HK$2.441) and a market cap of HK$12.86B. Trailing P/E still shows “No Profit”.
    • Price action. Friday +10.3% to HK$1.23, Monday −0.8% to HK$1.22. The 52-week range is HK$1.07–1.82.

    9M and Q3 results at a glance

    Item9M 2026Year earlierChange
    RevenueRMB 59.85bn—+1.7% YoY
    Net profitRMB 1.08bnLoss RMB 0.43bnTurned to profit
    Recurring net profitRMB 1.16bnLoss RMB 0.39bnTurned to profit
    Gross margin18.71%—+1.84 ppt
    Net margin1.74%—+2.47 ppt
    ItemQ3 2026Change
    RevenueRMB 20.86bn+7.9% YoY
    Net profitRMB 0.78bn~24.6x YoY; ~2.6x H1 profit
    Gross margin19.78%+2.67 ppt YoY, +3.92 ppt QoQ
    Net margin3.63%+3.47 ppt YoY, +4.26 ppt QoQ
    Source: company results as reported in market commentary notes. H1 2026: revenue RMB 38.992bn (−1.34% YoY), profit RMB 0.30bn vs a loss of RMB 0.462bn.

    Margin recovery: the quarter that changed the story

    H1 was barely profitable: revenue slipped 1.34% and profit was only RMB 0.30bn. Q3 changed that. Revenue grew 7.9%, but profit rose far faster, because the gross margin gained almost 4 ppt in a single quarter. For a refiner this is operating leverage at work. Feedstock is most of the cost base, so a few points of spread drop almost straight to the bottom line.

    Commentary notes describe this as the company getting out of its “high cost, low margin” bind. The recurring profit (RMB 1.16bn) is higher than the headline figure, so the improvement is not driven by one-off gains. A 1.74% nine-month net margin is still thin, though. The business stays very sensitive to spreads in both directions.

    Refining spreads and geopolitical supply drivers

    The main driver is outside the company’s control. According to market commentary notes:

    • Refinery damage. The US–Iran conflict and the Russia–Ukraine war have damaged refining facilities. Goldman Sachs estimates refinery outages of about 5.8 million barrels a day (an analyst estimate, not a verified figure).
    • Low inventories. Refined product inventories are low, so supply is tight and unlikely to ease in the short term.
    • Refining recovers slowly. Analysts note that even if the conflicts ease, refining capacity is likely to recover last. Oilfields can restart once transport resumes, but damaged refineries take a long time to repair. That should keep product prices high in the near to medium term.

    For a mainland refiner that is still running, this is a favourable setup: crude is available while product cracks stay wide. The flip side is that the tailwind comes from disruption. A faster-than-expected repair cycle or a ceasefire-driven drop in prices could narrow spreads quickly.

    Shanghai Petrochemical 00338 stock analysis: valuation

    MetricShanghai Petrochemical (00338)
    Last price (2026/11/02 close)HK$1.220
    Day change−HK$0.010 (−0.813%)
    Prev close / openHK$1.230 / HK$1.220
    Day rangeHK$1.200 – 1.240
    52-week rangeHK$1.070 – 1.820
    Market capHK$12.86B
    P/E / TTM P/ENo Profit / No Profit
    P/B (NAV HK$2.441)0.500x
    Dividend yieldN/A (last div RMB 0.02, ex 2025-06-24)
    Volume / turnover24.34M / HK$29.64M
    Data: AASTOCKS, updated 2026/11/02 16:08 HKT, market Closed; quotes delayed.
    Commentary checkpointsFigure
    Forward P/E~10x
    DividendFinal dividend expected to resume after profit recovery
    Entry zoneAccumulate on dips near HK$1.20
    First targetHK$1.45 (~19% above HK$1.22)
    Source: market commentary notes (forward-looking views and estimates, not AASTOCKS data).

    What the numbers tell us (our analysis):

    • Trailing vs forward. Trailing earnings are still negative (EPS −0.17 on AASTOCKS), so trailing P/E means nothing here. The ~10x forward figure assumes the Q3 run rate holds.
    • Book value is the anchor. At 0.50x NAV, the market is still pricing the company as a loss-maker. A sustained return to profit is what would close that gap.
    • The dividend is the catalyst. No dividend has been paid on the latest numbers. A resumed final dividend would be a clear signal for income investors.

    Technical analysis: breaking out of the base

    Shanghai Petrochemical (00338) one-year daily chart on AASTOCKS
    Source: AASTOCKS, as of 2 Nov 2026 16:08 HKT; 1-year daily chart

    The AASTOCKS one-year daily chart (3 Nov 2025 to 2 Nov 2026) shows a run to about HK$1.82 in March and a slide to a two-year low near HK$1.07. Since around July the stock has traded in a HK$1.07–1.20 box. Friday’s jump took it to the top of that box, and it held most of the gain on Monday.

    • Moving averages. The price of 1.22 is above SMA10 1.142, SMA20 1.136, SMA50 1.139 and SMA100 1.134, which are all bunched together. It is still below SMA250 1.277.
    • Momentum. RSI(14) is 66.5, close to overbought (RSI10 is 70.8). MACD(12,26) is 0.012 against a signal of 0.002, so the crossover is bullish.
    • Support. HK$1.20 (top of the box and the Monday low), then HK$1.13–1.14 (the SMA cluster), then HK$1.07.
    • Resistance. HK$1.24 (Monday high), then HK$1.277 (SMA250), then the commentary’s HK$1.45 target.

    Risks

    • Spread reversal. If geopolitical tension eases or repaired refineries come back faster than expected, crack spreads could compress quickly.
    • Crude cost spikes. A sharp rise in crude without matching product prices would squeeze margins again.
    • Thin margins. A 1.74% nine-month net margin leaves little buffer.
    • Policy and pricing. Mainland fuel pricing and the policy environment can cap how much of the spread is captured.
    • Technical risk. RSI is near overbought after a 10% day, and the stock is still below SMA250. A drop back into the box would weaken the breakout.
    • Dividend uncertainty. A resumed final dividend is an expectation, not an announcement.

    The DimSumInsider take

    Shanghai Petrochemical’s Q3 shows how quickly a refiner’s earnings can turn when spreads move. Profit rose about 24.6x, gross margin gained nearly 4 ppt in a quarter, and recurring profit is ahead of the headline number. At 0.50x book, the market is not yet paying for the recovery. Our approach is in line with the commentary: build positions near HK$1.20, look for a close above SMA250 (HK$1.277) as confirmation, and treat HK$1.45 as the first target. Cut if the price falls back below the HK$1.13 moving-average cluster. Keep watching refining spreads. They drove the turnaround, and they are also the main risk.

    FAQ

    What were Shanghai Petrochemical’s 9M 2026 results?

    Revenue was RMB 59.85bn (+1.7% YoY). Net profit was RMB 1.08bn, against a loss of RMB 0.43bn a year earlier. Recurring profit was RMB 1.16bn. Gross margin was 18.71% and net margin 1.74%.

    Why did 00338 jump 10.3%?

    The nine-month results released on Friday showed Q3 profit of RMB 0.78bn, up about 24.6x year on year. The shares rose 10.3% to HK$1.23, then fell 0.8% to HK$1.22 on Monday.

    What is Shanghai Petrochemical’s valuation?

    According to AASTOCKS as of 2026/11/02 close: HK$1.22, P/B 0.50, market cap HK$12.86B, and a trailing P/E of “No Profit”. Market commentary notes put the forward P/E at about 10x.

    What levels matter for 00338?

    Support is at HK$1.20, then HK$1.13–1.14, then HK$1.07. Resistance is at HK$1.24, then HK$1.277 (SMA250), then HK$1.45.


    Disclaimer: For information only. Based on public market commentary notes, company results as reported, and AASTOCKS data as of 2026/11/02 16:08 HKT (market Closed); data may be delayed. The refinery-outage figure is a third-party analyst estimate, and forward figures are estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
  • 361 Degrees (01361): Retail Outruns ANTA and FILA, a Cheap Re-Rating Bet

    361 Degrees (01361): Retail Outruns ANTA and FILA, a Cheap Re-Rating Bet

    361 Degrees (01361), listed as 361 DEGREES on AASTOCKS, closed at HK$4.675 on Friday 30 Oct, up HK$0.130 (+2.86%). This 361 Degrees 01361 stock analysis asks the alpha question. In a quarter when the big China sportswear names went backwards, 361 kept growing. At about 6.6x earnings, 0.86x book and a ~6.8% trailing yield, is that enough to earn a re-rating?

    Market commentary notes argue it is: retail is outrunning peers, the super-store rollout is pulling in genuinely new customers, and discounts are holding. Their view is that the risk-reward is favourable. The stock does not have to rally hard, but the downside looks limited. We broadly agree, with two caveats: the RMB and a high base.

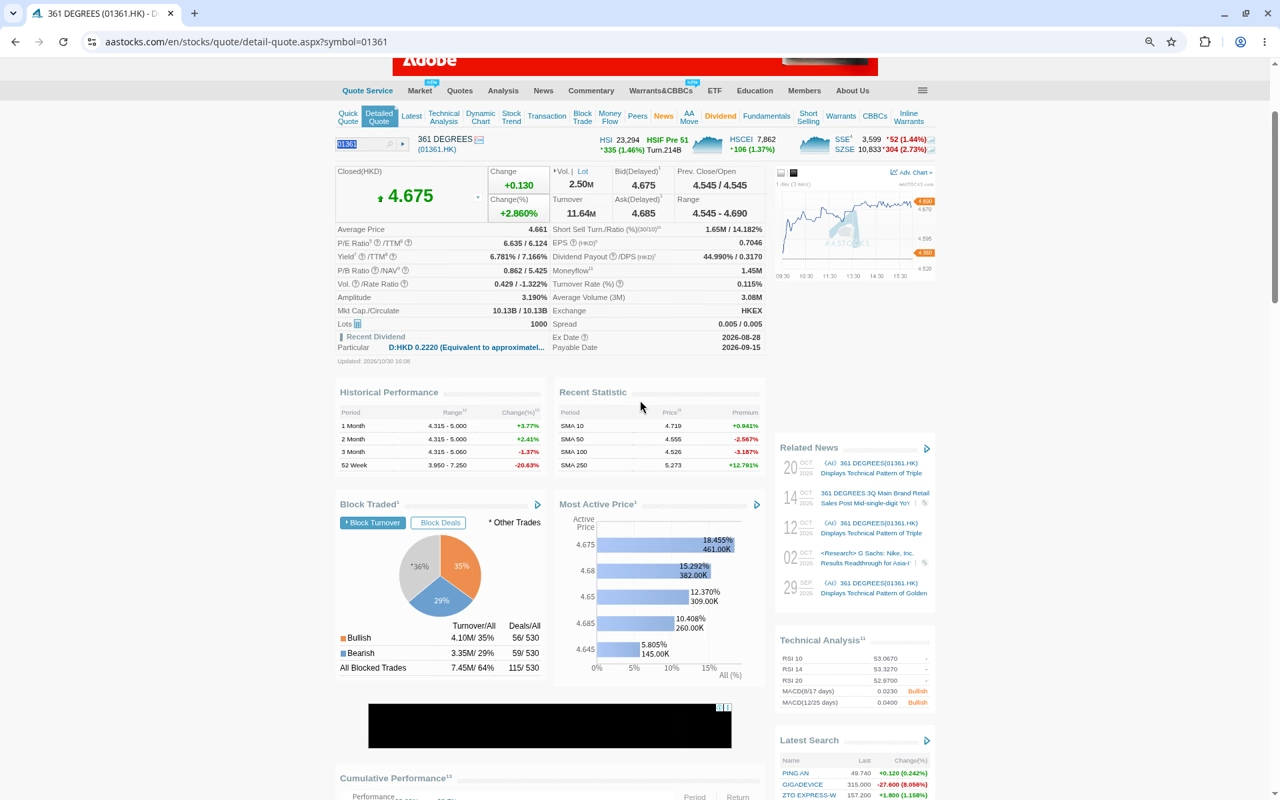
    361 Degrees (01361) detailed quote on AASTOCKS, 30 Oct 2026 16:08 HKT
    Source: AASTOCKS, as of 30 Oct 2026 16:08 HKT

    The news in brief

    • Q3 retail sales. Main-brand and kids offline retail both grew at a mid-single-digit rate. E-commerce grew at a mid-to-high single-digit rate.
    • Peers went the other way. In the same week, the ANTA brand (02020) fell by a mid-single digit and FILA fell by a low-single digit. Li Ning (02331) and Xtep (01368) were expected to report slight declines.
    • Super stores. 21 opened in Q3, for 208 on the mainland, and the full-year opening target was hit early. The share of new customers at these stores rose from about 65% to 75%, so three in every four shoppers are new to the brand.
    • Discount and inventory. The offline discount was about 30% off, a touch deeper than roughly 29% off in Q2. The inventory-to-sales ratio held at 4.5–5x.
    • Overseas. Management targets overseas at about 30% of revenue within 3–5 years. Overseas retail grew about 80% in H1, but it is expected to be only 4–5% of revenue for the full year.
    • Friday close (AASTOCKS, 30 Oct 2026 16:08 HKT). Last HK$4.675, open/prev close 4.545, day range 4.545–4.690, volume 2.50M, turnover HK$11.64M. Market Closed.

    Why the super-store number matters more than the store count

    Store openings are easy to count and easy to over-read. In a crowded market, the real risk for a sportswear brand is fighting rivals for the same customers until the only lever left is the discount. A 75% new-customer share at the super stores suggests 361 is widening its customer base, not just moving existing customers between channels. Tier-1 and tier-2 mall space is expensive, but if it brings in people who were not 361 customers before, it counts as investment rather than cost.

    The discount data backs this up. Basketball was the most competitive category in Q3 and international brands were marking down harder, yet 361’s offline discount moved only from about 29% to about 30% off, and inventory stayed at 4.5–5x sales. Commentary notes read this as a company that is not buying sales with price. The real warning would be heavy markdowns to clear stock in Q4.

    Overseas: an option, not the thesis

    The overseas story gets the market excited: a former Nike executive has joined, 361 has sponsored five straight Asian Games, and it had a booth at the Berlin Marathon. But at 4–5% of revenue, even a doubling next year adds only a few percentage points to group sales. Treat it like a call option: worth something, but don’t count on too much.

    Policy tailwind, with a lag

    At the end of September, the State Council General Office issued guidance on using sports events to boost consumption (5 areas, 17 tasks). It includes co-branded and licensed event merchandise and faster upgrades of smart wearables. July’s national fitness plan aims to lift regular exercise participation to 40% and sports venue area per person from 3.11 to 4 square metres. More venues and events should mean more shoe sales over time, but policy usually takes 18 months or more to show up in retail sales.

    361 Degrees 01361 stock analysis: valuation and key numbers

    Metric361 Degrees (01361)
    Last price (30 Oct 16:08)HK$4.675
    Day change+HK$0.130 (+2.860%)
    Prev close / openHK$4.545 / HK$4.545
    Day rangeHK$4.545 – 4.690
    52-week rangeHK$3.950 – 7.250
    Market capHK$10.13B
    P/E / TTM P/E (EPS 0.7046)6.635x / 6.124x
    P/B (NAV HK$5.425)0.862x
    Dividend yield / TTM / DPS6.781% / 7.166% / HK$0.317
    Payout44.99%
    SMA 10 / 20 / 504.719 / 4.605 / 4.555
    SMA 100 / 2504.526 / 5.273
    RSI 1453.3
    MACD (12,26) / signal / div0.042 / 0.049 / −0.007
    Volume / turnover2.50M / HK$11.64M
    Data: AASTOCKS, updated 30 Oct 2026 16:08 HKT, market Closed; quotes delayed. SMA20 and MACD(12,26,9) from the AASTOCKS daily chart.
    Commentary and forecast checkpointsFigure
    Share price when Q3 update was releasedHK$4.6 – 4.9
    Forecast P/E (consensus-style)5.46x
    Forecast P/B0.71x
    Payout (maintained)~45%
    Forecast dividend yield~8.25%
    Relative-strength screenAmong the ~5.2% of stocks classed “strong”; RS score 60
    1-month performance vs Hang Seng Index+13.7 ppt
    Commentary stanceRisk-reward favourable; no target price
    Source: figures cited in market commentary notes (forward-looking estimates); AASTOCKS for the quote table.

    What the numbers tell us (our analysis):

    • Trailing vs forward. AASTOCKS shows 6.6x P/E (TTM 6.1x) on reported earnings. The commentary’s 5.46x is a forecast, which assumes earnings keep growing. Either way, it is a single-digit multiple.
    • Yield: 6.8% now, ~8% forecast. AASTOCKS shows 6.78% (TTM 7.17%) on DPS HK$0.317 with a ~45% payout. The ~8.25% is the commentary’s forecast yield and is not an AASTOCKS figure. Even with zero earnings growth, a yield near 7% is hard to find in Hong Kong.
    • Below book. P/B 0.86x (the forecast is 0.71x) for a company whose sales are still growing while peers shrink.
    • Small cap, thin trading. A market cap of HK$10.1B and turnover of about HK$11.6M a day mean liquidity is a real constraint for larger buyers.

    Technical analysis: back above the 20-day line

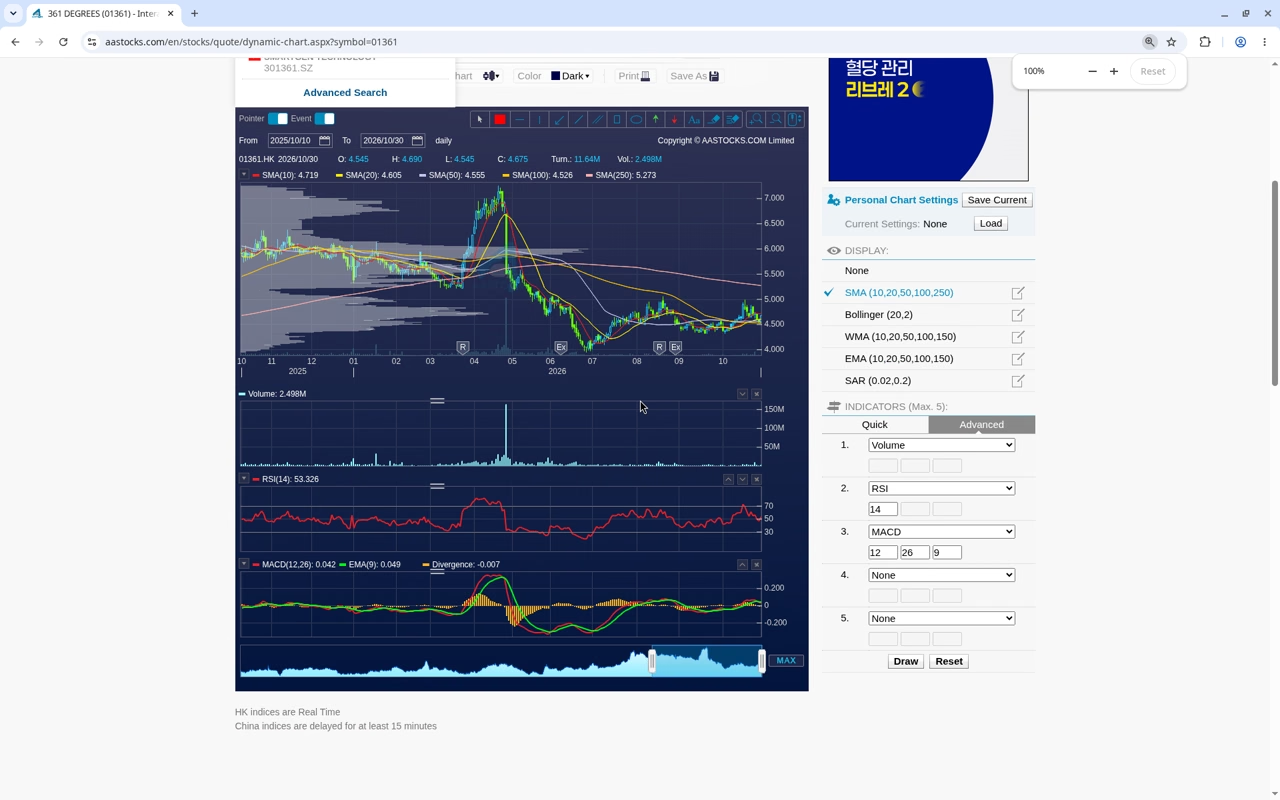
    361 Degrees (01361) one-year daily chart on AASTOCKS
    Source: AASTOCKS, as of 30 Oct 2026 16:08 HKT; 1-year daily chart

    The AASTOCKS one-year daily chart (10 Oct 2025 to 30 Oct 2026) shows a spike to about HK$7.25 in April/May, a sharp drop and a low of about HK$3.95 in late June/July, and then a base in the HK$4.3–5.0 range. Friday’s close of 4.675 sits above SMA20 4.605, SMA50 4.555 and SMA100 4.526, but just below SMA10 4.719 and well below SMA250 5.273.

    • Momentum is neutral to positive. RSI(14) is 53.3. MACD (0.042) is just under its signal line (0.049), a small negative divergence of −0.007, so the trend is flattening, not turning down.
    • Support. HK$4.53–4.61 (SMA100, SMA50 and SMA20 bunched together), then the Friday low/open at 4.545, then the HK$3.95 52-week low.
    • Resistance. HK$4.69–4.72 (day high and SMA10), then the ~HK$5.0 ceiling of the range, then HK$5.27 (SMA250). A close above the 250-day line would confirm a re-rating.

    Bull case vs bear case

    Bull case

    • Retail grew while ANTA brand, FILA, Li Ning and Xtep fell or were guided lower.
    • 75% of super-store customers are new, and the full-year store target was reached early.
    • Discounts and inventory are stable, with no price war.
    • About 6.6x P/E, 0.86x book and a 6.8% yield (TTM 7.2%), with a ~8.25% forecast in commentary.
    • A relative-strength screen ranks it among the strongest ~5% of stocks; it is up 13.7 ppt vs the HSI over a month.
    • The State Council sports-consumption guidance and the fitness plan support demand in the medium term.

    Bear case

    • RMB risk: earnings are in RMB and the shares trade in HKD, so a weaker yuan can make “cheap” an illusion.
    • High base: the main brand grew double digits in Q3 last year. If Q4 slows to low-single digits, it becomes a demand problem.
    • Consumer stocks are out of favour, and a stock can stay range-bound for a long time.
    • Overseas is still only 4–5% of revenue.
    • Low liquidity, and the price is still below SMA250.

    Levels to watch

    1. HK$3.95 (52-week low). A break would void the base.
    2. HK$4.53–4.61 (SMA100/50/20 cluster). The key trend support.
    3. HK$4.69–4.72 (day high / SMA10). The first hurdle.
    4. ~HK$5.0 (range top). A breakout would open up the re-rating.
    5. HK$5.27 (SMA250). Trend confirmation.
    6. Fundamentals. Q4 retail growth (mid-single digit vs low-single digit), discount depth, the RMB and the final dividend.

    The DimSumInsider take

    361 Degrees is a cheap, high-yield consumer name that is outgrowing its peers. Investors are also getting a small overseas option on top. The data that matters is the 75% new-customer share at super stores and a discount that barely moved in a brutal quarter. At roughly 6.6x trailing earnings and 0.86x book, with a yield near 7%, the market is pricing it as an ex-growth name. Our approach: accumulate on dips into the HK$4.53–4.61 moving-average cluster, add on a close above HK$5.0, and cut if HK$3.95 breaks. Watch the Q4 update closely, because low-single-digit growth would weaken the thesis.

    FAQ

    How did 361 Degrees’ Q3 retail sales compare with peers?

    Main-brand and kids offline retail grew at a mid-single-digit rate, and e-commerce at a mid-to-high single-digit rate. The ANTA brand fell by a mid-single digit, FILA by a low-single digit, and Li Ning and Xtep were expected to decline slightly.

    What are 361 Degrees super stores?

    They are large-format stores. 21 opened in Q3, bringing the mainland total to 208, and the full-year target was reached early. About 75% of their customers are new to the brand, up from about 65%.

    What is 361 Degrees’ dividend yield?

    AASTOCKS shows 6.781% (TTM 7.166%) on DPS of HK$0.317 with a ~45% payout, as of 30 Oct 2026 16:08 HKT. Market commentary notes forecast a yield of about 8.25%.

    What are the key 361 Degrees valuation numbers?

    At HK$4.675 (AASTOCKS, 30 Oct 2026, market Closed): P/E 6.635x (TTM 6.124x), P/B 0.862x, market cap HK$10.13B. Consensus-style forecasts put the forward P/E at about 5.46x and P/B at 0.71x.

    What levels matter for 01361?

    Support is at HK$4.53–4.61 (SMA100/50/20), then HK$4.545, then the 52-week low of HK$3.95. Resistance is at HK$4.69–4.72, then about HK$5.0, then HK$5.27 (SMA250).


    Disclaimer: For information only. Based on public market commentary notes, company operating updates as reported, and AASTOCKS data as of 30 Oct 2026 16:08 HKT (market Closed); data may be delayed. Forecast figures are estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
  • Ping An (02318): Core Profit Steady Behind a −93.7% Headline — Keep Holding

    Ping An (02318): Core Profit Steady Behind a −93.7% Headline — Keep Holding

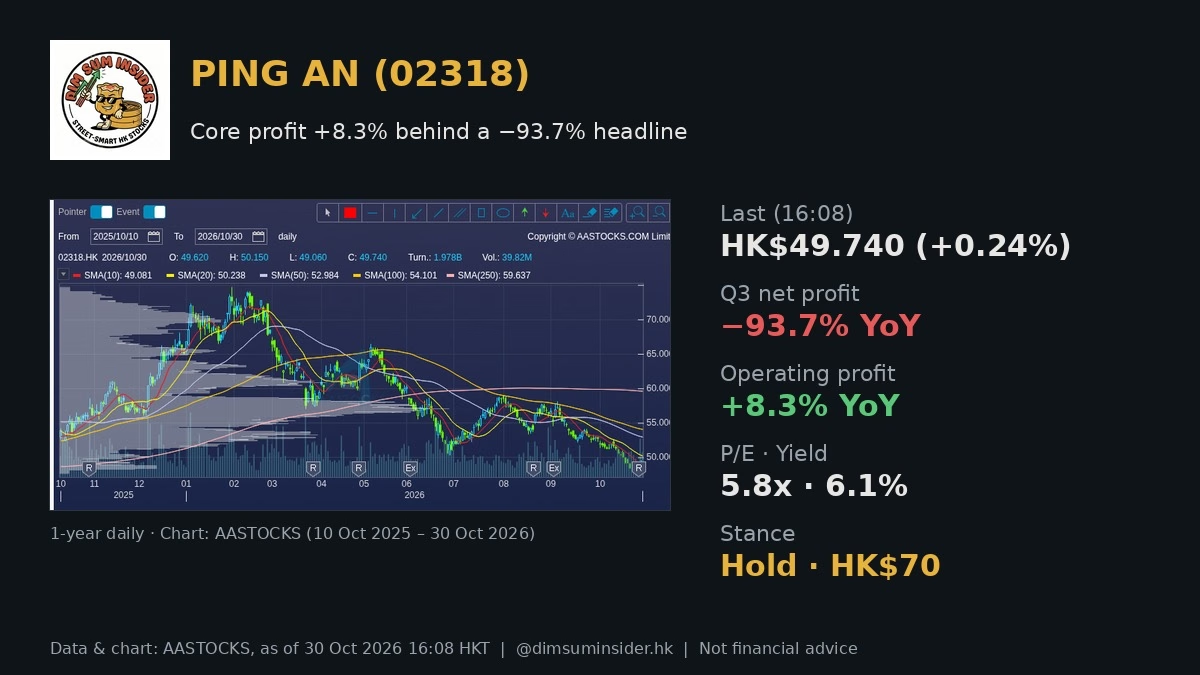
    Ping An Insurance (02318) — PING AN on AASTOCKS — closed at HK$49.740 on 30 Oct (+0.120 / +0.242%) after a +2.56% pop to HK$49.62 the session before. This Ping An 02318 stock analysis asks the alpha question: when Q3 net profit collapses 93.7% but after-tax operating profit grows 8.3%, is the headline a value trap or a mark-to-market noise opportunity at roughly 5.8x earnings and a ~6% yield?

    Market commentary notes read the print as “core business steady”: the net-profit hit came from fair-value losses as China’s A-share market corrected in Q3, not from the insurance engine. Their stance is to keep holding, with a medium-term target of HK$70. Broker research from Morgan Stanley stays Overweight with a HK$85 target. Our view is close to theirs: own the operating profit and the dividend, but accept that the chart is still in a downtrend channel and needs repair.

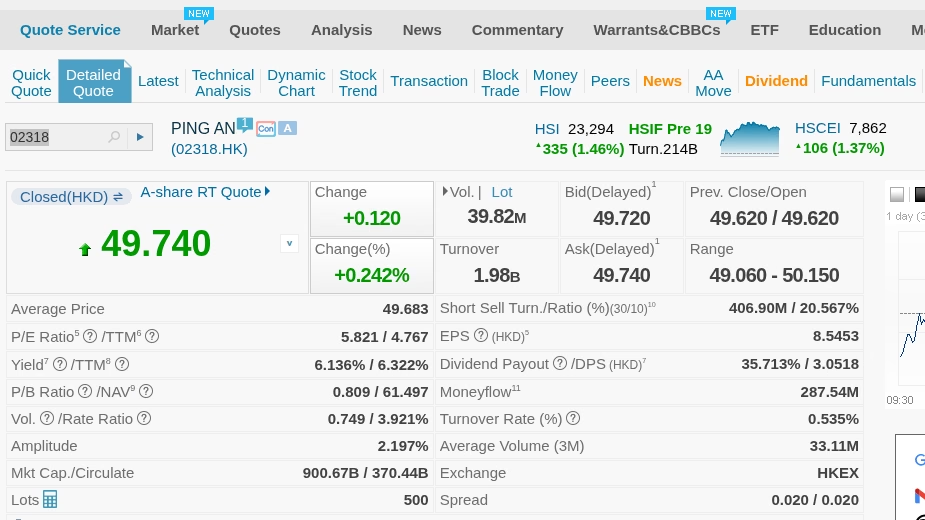
    Ping An (02318) detailed quote on AASTOCKS, 30 Oct 2026 16:08 HKT
    Source: AASTOCKS, as of 30 Oct 2026 16:08 HKT

    The news in brief

    • Q3 headline (RMB). Revenue about 1,530億 = RMB 153.0bn (−54% YoY); net profit 40.60億 = RMB 4.06bn (−93.7% YoY), mainly from fair-value losses on equity holdings as A-shares corrected.
    • 9M (RMB). Revenue 7,281.34億 = RMB 728.13bn (−12.6%); net profit 966.45億 = RMB 96.65bn (−27.3%), versus +36.1% at the H1 stage.
    • The number that matters. Q3 after-tax operating profit about RMB 41.7bn; 9M operating profit about RMB 125.9bn, both +8.3% YoY. Strip out short-term investment swings and the core business grew.
    • Franchise. The “integrated finance + health care and elderly care” model spans life and health, P&C, pensions, banking, asset management, trust and securities. About 256m customers at end-September; 99% 12-month retention for customers holding 3+ product categories.
    • Broker view. Morgan Stanley calls Q3 operating profit resilient, attributes a weaker single-quarter new business value (VNB) print mainly to a high base, expects mid-single-digit full-year DPS growth, is confident in medium-term double-digit VNB growth, and keeps Overweight, TP HK$85.
    • Friday close (AASTOCKS, 30 Oct 2026 16:08 HKT). Last HK$49.740, open/prev close 49.620, day 49.060–50.150, volume 39.82M, turnover HK$1.98B. Hang Seng Index 23,294 (+1.46%). Market Closed.

    Why a −93.7% profit print is not a broken insurer

    Under IFRS 17 / IFRS 9, a big chunk of an insurer’s equity book is marked through profit and loss. When A-shares fall in a quarter, reported net profit swings hard, and Ping An’s Q3 is a textbook case. Operating profit is the metric management and analysts use to strip that noise out, and it rose 8.3% in both Q3 and 9M.

    That is why the dividend debate matters more than the headline. Ping An’s dividend policy is tied to operating profit, not reported net profit, so a resilient operating line plus Morgan Stanley’s mid-single-digit DPS growth call supports a yield floor around 6% at current prices.

    What still has to go right

    1. A-shares stabilise. Another quarter of equity correction means more fair-value noise and more negative headlines, even if operating profit holds.
    2. VNB growth resumes. The high-base excuse covers one quarter; the medium-term double-digit VNB thesis needs proof in 2027.
    3. Dividend delivered. Mid-single-digit DPS growth keeps the yield case intact; a cut would break it.
    4. Technical repair. Reclaim SMA20 50.24, then SMA50 52.98, to escape the downtrend channel.

    Ping An 02318 stock analysis: valuation and key numbers

    MetricPing An (02318)
    Last price (30 Oct 16:08)HK$49.740
    Day change+HK$0.120 (+0.242%)
    Prev close / openHK$49.620 / HK$49.620
    Day rangeHK$49.060 – 50.150
    52-week rangeHK$47.680 – 74.700
    Market cap / circulating (H)HK$900.67B / 370.44B
    P/E / TTM P/E (EPS HK$8.5453)5.821x / 4.767x
    P/B (NAV HK$61.497)0.809x
    Dividend yield / TTM / DPS6.136% / 6.322% / HK$3.0518
    Payout35.713%
    SMA 10 / 20 / 5049.081 / 50.238 / 52.984
    SMA 100 / 25054.101 / 59.637
    RSI 1440.864
    MACD (12,26) / signal / div−1.146 / −1.229 / 0.083
    Volume / turnover39.82M / HK$1.98B
    Short-sell ratio (30/10)20.567%
    Data: AASTOCKS, updated 30 Oct 2026 16:08 HKT, market Closed; quotes delayed. SMA20, RSI and MACD from the AASTOCKS daily chart.
    Results and commentary checkpointsFigure
    Q3 revenue / YoY~RMB 153.0bn / −54%
    Q3 net profit / YoYRMB 4.06bn / −93.7%
    9M revenue / YoYRMB 728.13bn / −12.6%
    9M net profit / YoYRMB 96.65bn / −27.3% (H1: +36.1%)
    Q3 / 9M after-tax operating profit~RMB 41.7bn / ~RMB 125.9bn (both +8.3%)
    Customers (end-Sep)~256m
    12-month retention, 3+ categories99%
    Morgan StanleyOverweight, TP HK$85
    Commentary PE / yield~5.8x trailing; 6.15% trailing, ~6.5% expected
    Commentary stanceKeep holding; medium-term target HK$70
    Source: figures cited in market commentary notes and Morgan Stanley broker research; AASTOCKS for the quote table. 億 = 100m: 40.60億 = RMB 4.06bn; 966.45億 = RMB 96.645bn.

    What the numbers tell us (our analysis):

    • The PE figures line up. Commentary’s ~5.8x trailing PE matches AASTOCKS’ headline P/E 5.821x. AASTOCKS also shows a lower TTM P/E of 4.767x; we quote both and anchor on 5.8x.
    • The yield is roughly the same too. Commentary cites 6.15% trailing; AASTOCKS shows 6.136% (TTM 6.322%) on DPS HK$3.0518. The ~6.5% forward figure is the commentary’s estimate, not an AASTOCKS print.
    • Below book. P/B 0.81x against NAV HK$61.50 prices in a lot of bad news for a franchise growing operating profit 8%.
    • Payout has room. A ~36% payout leaves space for the DPS growth Morgan Stanley expects.
    • Shorts are active. A 20.6% short-sell ratio means rallies will be contested.

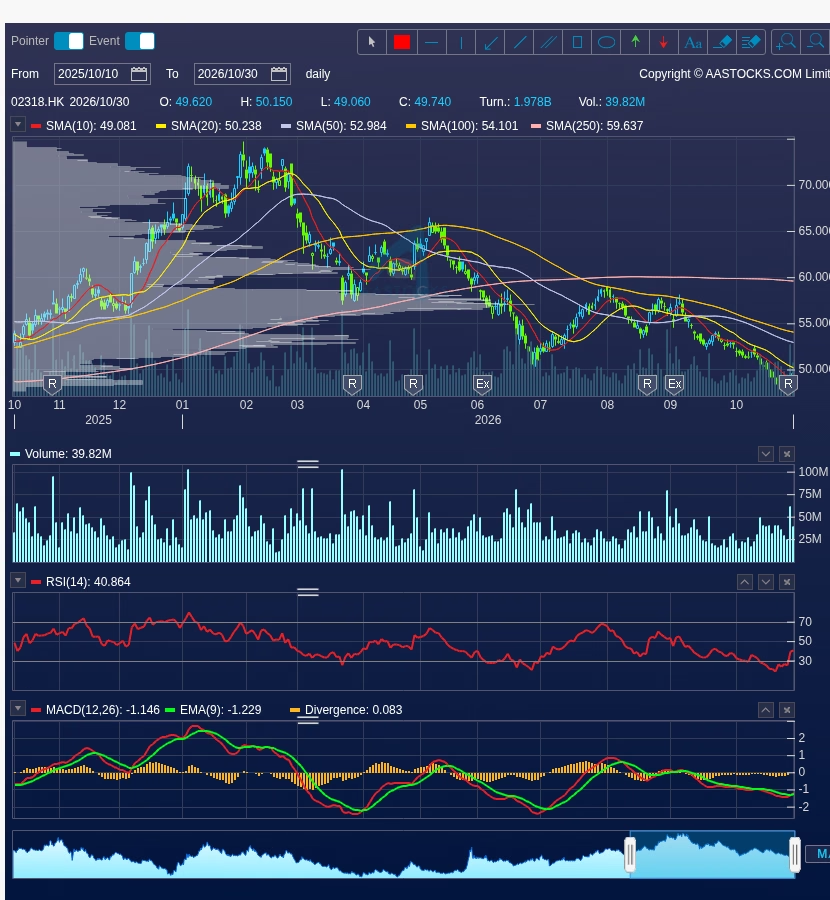
    Technical analysis: still inside the downtrend channel

    Ping An (02318) one-year daily chart on AASTOCKS
    Source: AASTOCKS, as of 30 Oct 2026 16:08 HKT; 1-year daily chart

    The AASTOCKS one-year daily chart (10 Oct 2025 to 30 Oct 2026) shows a run from the mid-50s to a high near HK$74.70 in early 2026, then a steady staircase of lower highs and lower lows into the high-40s. The price sits just above SMA10 49.08 but below SMA20 50.24, SMA50 52.98, SMA100 54.10 and SMA250 59.64, a fully bearish moving-average stack.

    • Momentum is basing. RSI(14) 40.9 has turned up from the low-30s, and MACD (−1.146) has just crossed above its signal (−1.229) with a positive divergence of +0.083. That is an early turn, not a trend change.
    • Support. The 52-week low HK$47.68 is the line that matters; the day low 49.06 comes first.
    • Resistance. HK$50.15–50.24 (day high / SMA20), then HK$52.98 (SMA50) and ~54.1 (SMA100). A close above SMA50 would be the first real break of the channel.

    Bull case vs bear case

    Bull case

    • Operating profit +8.3% in Q3 and 9M; the net-profit collapse is mark-to-market noise.
    • About 5.8x PE, 0.81x book and a ~6.1% yield (commentary expects ~6.5%).
    • Morgan Stanley Overweight, TP HK$85; mid-single-digit DPS growth; double-digit VNB growth medium term.
    • A cross-selling franchise: 256m customers, 99% retention for 3+ category holders.
    • MACD bullish crossover and RSI rising from oversold territory near the 52-week low.

    Bear case

    • A-share weakness keeps hitting reported profit; headlines stay ugly.
    • Single-quarter VNB was weak; the high-base explanation needs confirming next year.
    • Fully bearish SMA stack; the downtrend channel since early 2026 is intact.
    • Short-sell ratio above 20%.
    • China rates and the property/credit backdrop weigh on investment yields.

    Levels to watch

    1. HK$47.68 (52-week low). A break would invalidate the base and open new lows.
    2. HK$49.06–49.08 (day low / SMA10). Near-term pivot.
    3. HK$50.15–50.24 (day high / SMA20). First repair level.
    4. HK$52.98 (SMA50). Channel-break confirmation.
    5. HK$54.1 / 59.6 (SMA100 / SMA250). Heavier supply on the way to the HK$70 medium-term target.
    6. Fundamentals. A-share direction, Q4 VNB and the final DPS.

    The DimSumInsider take

    Ping An is a value-and-yield hold with a mark-to-market headache, not a broken story. The franchise grew after-tax operating profit 8.3% while the A-share correction wiped out reported Q3 profit. At 5.8x earnings, 0.81x book and a ~6% yield backed by operating profit, the commentary’s keep-holding call and HK$70 medium-term target look reasonable, and Morgan Stanley’s HK$85 is the upside case. Our approach: hold core positions while HK$47.68 holds, add on a close above SMA50 (HK$52.98), and collect the dividend while waiting. The edge here is patience, because the market is pricing the noise and not the engine.

    FAQ

    Why did Ping An’s Q3 net profit fall 93.7%?

    Mainly fair-value losses on equity investments as China’s A-share market corrected in Q3. After-tax operating profit, which strips out short-term investment swings, rose 8.3% to about RMB 41.7bn.

    Is Ping An’s dividend safe?

    The dividend is linked to operating profit, which is growing. Morgan Stanley expects mid-single-digit full-year DPS growth. AASTOCKS shows a 6.136% yield (TTM 6.322%) with a ~36% payout.

    What are the key Ping An valuation numbers?

    At AASTOCKS 16:08 HKT on 30 Oct 2026 (HK$49.740, market Closed): P/E 5.821x (TTM 4.767x), P/B 0.809x, yield 6.136%, market cap HK$900.67B. Commentary’s ~5.8x PE and 6.15% yield are consistent with this.

    What price targets are out there?

    Market commentary notes set a medium-term target of HK$70 with a keep-holding stance. Morgan Stanley rates Ping An Overweight with a HK$85 target.

    What levels matter for 02318?

    Support HK$49.06 then the 52-week low HK$47.68; resistance HK$50.24 (SMA20), HK$52.98 (SMA50), HK$54.1 (SMA100) and HK$59.6 (SMA250).


    Disclaimer: For information only. Based on public market commentary notes, Morgan Stanley broker research as reported, and AASTOCKS data as of 30 Oct 2026 16:08 HKT (market Closed); data may be delayed. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
  • GigaDevice (03986): AI Storage Rebound — Accumulate After Drawdown

    GigaDevice (03986): AI Storage Rebound — Accumulate After Drawdown

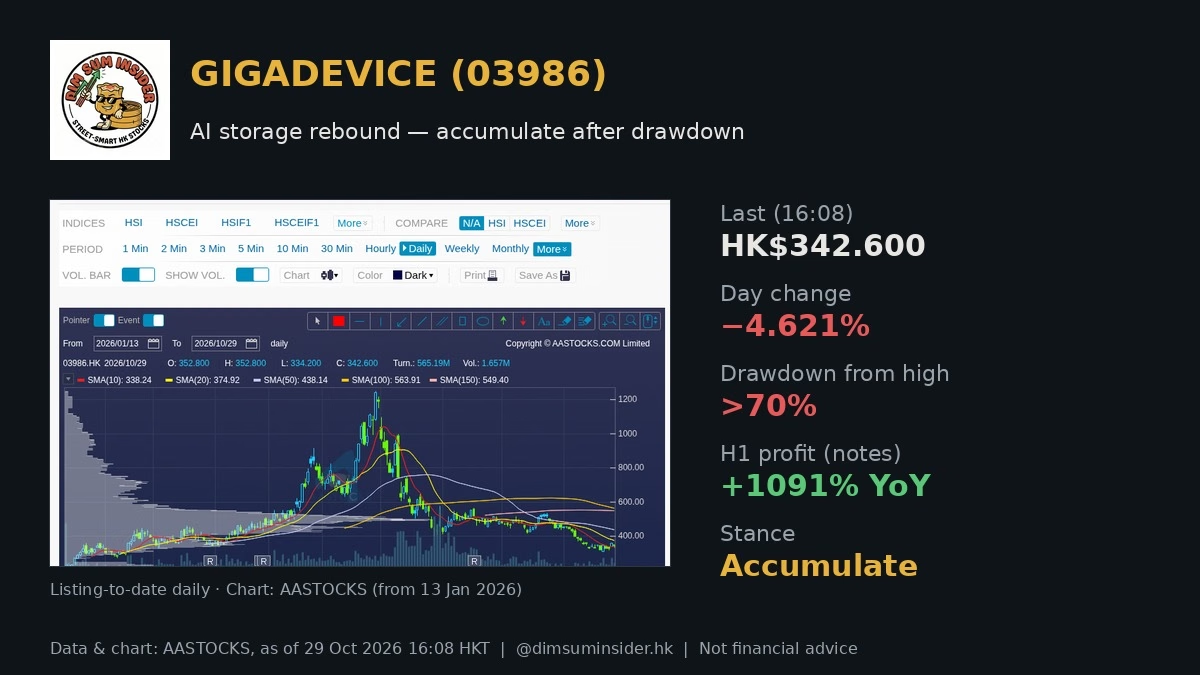
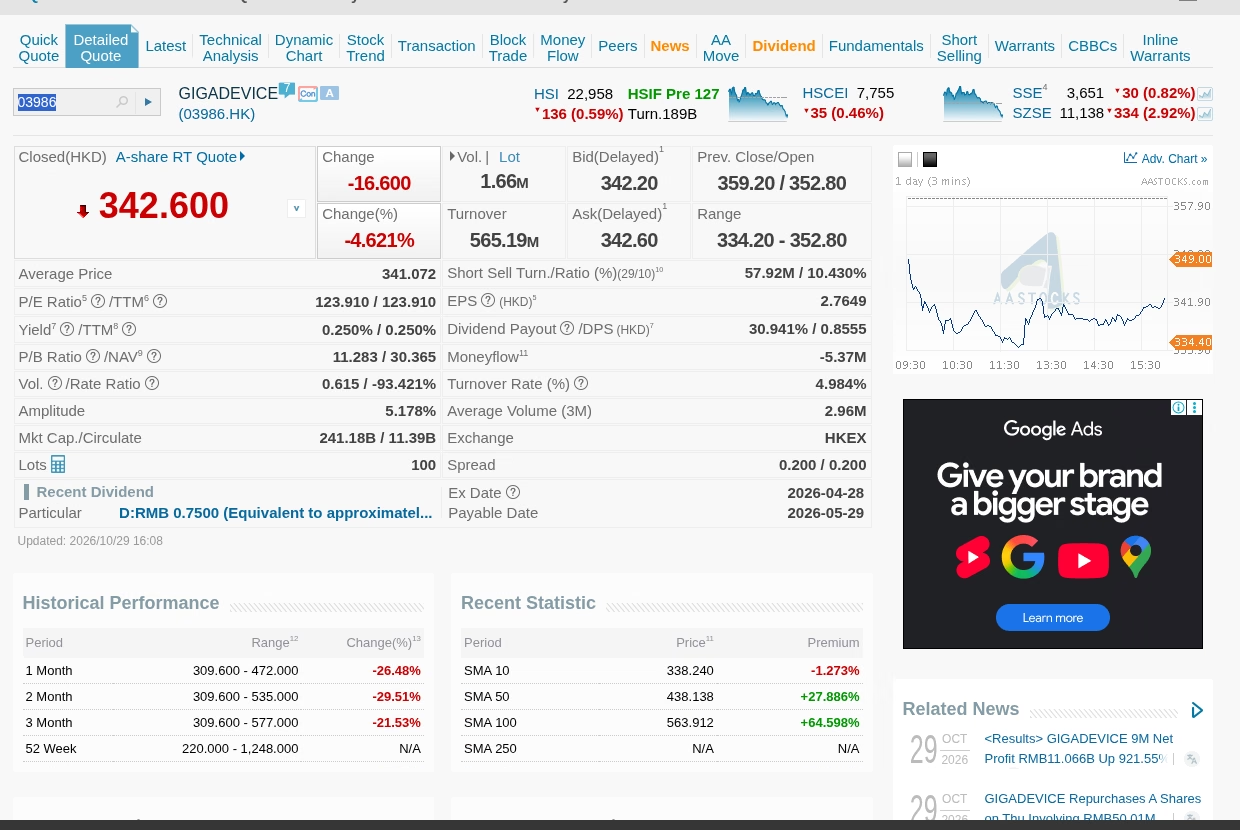
    GigaDevice (03986) — English name GIGADEVICE on AASTOCKS — closed at HK$342.600 on 29 Oct (−16.600 / −4.621%), giving back part of the prior session’s ~10% rebound that left the previous close at HK$359.20. This GigaDevice 03986 stock analysis asks the alpha question: after a >70% slide from the ~HK$1,248 high toward the ~300 area, with H1 revenue +178.7% and net profit +1091%, and AI demand lifting specialty-memory prices, is the bounce a stage-accumulate setup — or just a bear-market rally under a still-elevated H-share multiple?

    Market commentary notes flag the storage-chip leader’s rebound after roughly four months of tech adjustment, cite an SK Hynix shortage narrative through 2030, and argue a staged accumulate after the deep drawdown. For the HK listing, AASTOCKS shows TTM P/E 123.9x and P/B 11.3x — not the ~27.7x figure that appears in some commentary (that may refer to a different share class or basis; see dual-listing note below). Stance can still be staged accumulate into the growth story, with eyes open on the high H-share multiple and soft technicals.

    GigaDevice (03986) detailed quote on AASTOCKS, 29 Oct 2026 16:08 HKT
    Source: AASTOCKS, as of 29 Oct 2026 16:08 HKT

    The news in brief

    • Business. Designs, develops and sells specialty memory, MCUs, sensor chips and analog chips. Commentary ties the rebound thesis to rapid AI growth lifting storage-chip prices.
    • H1 (RMB, 億 check). Revenue 115.66億 = RMB 11.566bn (+178.7% YoY); net profit 68.57億 = RMB 6.857bn (+1091% YoY). Near-term profit growth may slow, but AI demand is described as firm and longer-term potential constructive.
    • Tape / drawdown. From a high near ~1,248 toward ~300 — drawdown >70% amid AI-infra growth skepticism. Prior session bounced nearly 10% (prev close 359.20); today gave back −4.6% to 342.60.
    • Sector narrative (commentary). SK Hynix shortage expected through 2030 → sector stabilizing / rebounding after the multi-month tech adjustment.
    • Valuation (critical). Commentary cites TTM PE ~27.7x as reasonable vs semiconductor-design peers and concludes accumulate. AASTOCKS H-share (03986) TTM PE is 123.910 / P/B 11.283 — use that for the HK listing. Dual listing: A-share 603986 (SH) / H-share 03986 (HK, listed 13 Jan 2026). The ~27.7x figure may refer to a different share class or basis; do not treat HK TTM PE as 27.7x.
    • Thursday close (AASTOCKS, updated 29 Oct 2026 16:08 HKT). Last HK$342.600 (−16.600 / −4.621%), prev 359.20, open 352.80, day 334.20–352.80, vol 1.66M, turnover HK$565.19M. Market Closed. Chart history starts at listing 2026/01/13 (not a full calendar 1Y; SMA250 N/A).

    Why AI storage and the drawdown still matter

    GigaDevice is a China specialty-memory / MCU / sensor / analog design name — not a pure foundry story. Commentary’s point is that after a brutal multi-month tech washout, AI demand is again lifting storage prices, H1 prints were extreme (+178.7% / +1091%), and the stock has already paid a >70% drawdown from the mid-year spike. That is a margin-of-safety plus AI-storage demand frame after a correction — not a cheap H-share multiple story.

    The valuation overlay needs honesty: AASTOCKS H-share TTM PE 123.9x and P/B 11.3x are rich for a post-IPO H listing still under a year old. Commentary’s accumulate call leans on growth runway and the ~27.7x peer framing (likely another basis / A-share context). Our approach: respect the growth + drawdown case for staged buying, but size as if you are paying a high H-share multiple into a stock still below SMA50 / SMA100 with MACD bearish.

    What still has to go right

    1. AI storage prices stay firm. Specialty-memory ASP and volume need to keep validating the H1 surge as AI demand, not a one-off inventory flush.
    2. H-share multiple compresses into earnings. At 123.9x TTM, the accumulate thesis needs profit growth (or A/H basis clarity) to catch up — not just another bounce.
    3. Technical repair. Reclaim SMA20 374.92 then SMA50 438.14; a sustained break of the ~334 day-low / ~300 commentary zone would pause staged sizing until a new base forms.

    GigaDevice 03986 stock analysis: valuation and key numbers

    MetricGigaDevice (03986)
    Last price (29 Oct 16:08)HK$342.600
    Day change−HK$16.600 (−4.621%)
    Prev close / openHK$359.20 / HK$352.80
    Day rangeHK$334.20 – 352.80
    52-week rangeHK$220.000 – 1,248.000
    Market cap / circulateHK$241.18B / 11.39B
    P/E / TTM P/E (EPS 2.7649)123.910x / 123.910x
    P/B (NAV 30.365)11.283x
    Dividend yield / TTM / DPS0.250% / 0.250% / HK$0.8555
    Payout30.941%
    SMA 10 / 20 / 50338.24 / 374.92 / 438.14
    SMA 100 / 150 / 250563.91 / 549.40 / N/A
    RSI 1438.94
    MACD (12,26) / signal / div−33.735 / −35.311 / 1.577
    Volume / turnover1.66M / HK$565.19M
    Short-sell ratio (29/10, full day)10.430%
    Data: AASTOCKS, updated 29 Oct 2026 16:08 HKT, market Closed. English name: GIGADEVICE. SMA10/50/100 from quote panel; SMA20 374.92, SMA150 549.40 and MACD(12,26)/RSI from chart. Chart window: 2026/01/13–2026/10/29 (listing-to-date; not a full calendar 1Y). SMA250 N/A.
    Operating / commentary checkpointsFigure
    H1 revenue / YoYRMB 11.566bn / +178.7%
    H1 net profit / YoYRMB 6.857bn / +1091%
    Business mixSpecialty memory, MCU, sensors, analog
    AI / storage narrativeAI demand lifting storage-chip prices
    Drawdown from high~1,248 → ~300 (>70%)
    Sector noteSK Hynix shortage narrative through 2030
    Commentary TTM PE (notes)~27.7x — may be other class/basis
    HK H-share TTM PE (AASTOCKS)123.9x
    Dual listingA 603986 / H 03986 (listed 13 Jan 2026)
    Stance (commentary)Accumulate (staged after drawdown)
    Source: figures cited in market commentary notes; AASTOCKS for the quote table. 億 units converted: 115.66億 = RMB 11.566bn; 68.57億 = RMB 6.857bn.

    What the numbers tell us (our analysis):

    • H-share multiple is the risk, not the accumulate argument. AASTOCKS TTM P/E 123.9x / P/B 11.3x sit far above commentary’s ~27.7x framing — treat the HK listing as expensive growth, and assume the lower figure may be A-share or another basis.
    • Yield is not the floor. Trailing yield 0.25% (DPS HK$0.8555, payout ~31%) is incidental.
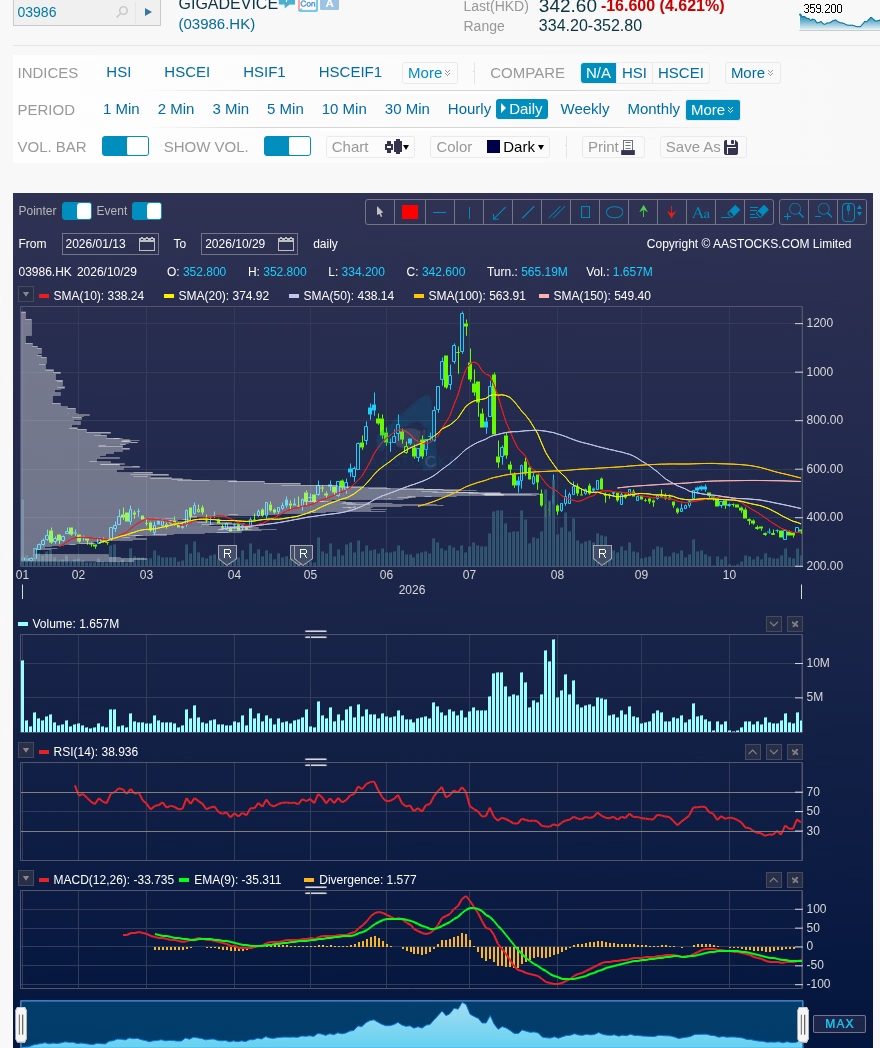
    • Price is under the medium SMAs, just above SMA10. Last 342.60 is slightly above SMA10 338.24, well below SMA20 374.92 / SMA50 438.14 / SMA100 563.91 / SMA150 549.40 — medium-term stack still bearish.
    • RSI is soft, not washed-out. RSI(14) ~38.9 is below mid-band — room for either a grind toward SMA20 or another shakeout under 334.
    • MACD still bearish, histogram improving. MACD −33.735 vs signal −35.311 (div +1.577) shows a less-negative histogram while both lines sit deep under zero — early constructive tell, not a trend flip.
    • Today’s −4.6% is a bounce giveback. Prior close 359.20 (~+10% session) failed to hold; vol 1.66M vs 3M avg 2.96M — not a panic flush, but not confirmed follow-through either.

    Technical analysis: listing-to-date mountain, not a full 1Y

    GigaDevice (03986) listing-to-date daily chart on AASTOCKS (from 13 Jan 2026)
    Source: AASTOCKS, as of 29 Oct 2026 16:08 HKT; chart from listing 13 Jan 2026, not full calendar 1Y

    The AASTOCKS daily chart only loads from the H-share listing on 2026/01/13 through 2026/10/29 (~9.5 months) — there is no full calendar 1-year history yet (SMA250 N/A; 1Y return N/A on the quote page). What it shows is a classic post-IPO mountain: IPO area / early base near the low-200s, a vertical run into the ~1,248 high, then a multi-month collapse back toward the ~300–350 band. Today’s bar (O/H/L/C 352.80 / 352.80 / 334.20 / 342.60) sits just above SMA10 and well under SMA20–150.

    • First job: hold above day low / ~300 zone, then reclaim SMA20. Near-term pivot is HK$334.20 (today’s low) and the commentary ~300 area; next resistance HK$374.92 (SMA20), then HK$438.14 (SMA50).
    • Heavier supply. SMA100 563.91 / SMA150 549.40 — the mid-year distribution zone.
    • Support. Day low HK$334.20, then the post-listing / 52w low area toward HK$220. A sustained break of the low-330s would pause the stage-accumulate sizing for us until a new base forms.
    • RSI ~38.9 is soft fuel; MACD div +1.577 is the early constructive tell, not yet a trend flip.

    Levels: first resistance HK$352.80 (day high / open) and HK$374.92 (SMA20); heavier HK$438.14 (SMA50) then ~550–564 (SMA150/100); support HK$334.20 then the ~300 / 220 band.

    Bull case vs bear case

    Bull case

    • H1 revenue +178.7% and net profit +1091% — extreme operating leverage into AI/storage demand.
    • Specialty memory + MCU + sensors + analog mix sits in the AI hardware stack, not just one product cycle.
    • >70% drawdown from ~1,248 toward ~300 resets a lot of froth after the mid-year spike.
    • SK Hynix shortage narrative through 2030 and sector rebound chatter after ~4 months of tech adjustment.
    • RSI soft (~38.9); MACD histogram improving (div +1.577); prior session showed a ~10% bounce is still possible.

    Bear case

    • H-share TTM PE 123.9x / P/B 11.3x — expensive even after the drawdown; commentary’s ~27.7x is not the HK listing print.
    • Price still below SMA20 / SMA50 / SMA100 / SMA150; absolute structure remains a post-spike collapse.
    • Today’s −4.6% giveback after the bounce shows overhead supply is real near 350–360.
    • Near-term profit growth may slow (per commentary); any AI-infra demand disappointment hits a high multiple hard.
    • Chart window is short (listed 13 Jan 2026) — limited SMA history; SMA250 N/A; “1Y chart” captions must say listing-to-date.

    Levels to watch

    1. HK$334.20 (day low). Near-term floor — hold vs break decides whether staged buying has a tape floor after the giveback.
    2. HK$352.80–359.20 (day high / prior close). Bounce-zone supply; reclaim needed to repair today’s −4.6%.
    3. HK$374.92 (SMA20). First medium-term repair level.
    4. HK$438.14 (SMA50). Intermediate trend repair after the multi-month slide.
    5. HK$549–564 (SMA150 / SMA100). Heavier moving-average supply from the mid-year distribution.
    6. AI storage ASP / H1→FY profit trajectory and A/H PE basis. Fundamental swing factors behind any accumulate thesis at 123.9x H-share TTM.

    The DimSumInsider take

    GigaDevice is an AI-storage / specialty-memory design name after a >70% drawdown from the ~1,248 high — not a cheap H-share multiple. The fundamental print (H1 rev +178.7%, profit +1091%) and the storage-shortage narrative support commentary’s accumulate frame, while AASTOCKS H-share TTM PE 123.9x / P/B 11.3x and a still-bearish SMA stack demand staged sizing and patience. Our approach: treat HK$334–375 as the prove-it band for staged entries after today’s giveback, keep a reclaim of SMA20 / SMA50 as confirmation for size-up, and respect open air under 334 toward the ~300 / 220 band. The alpha is buying AI storage demand and a washed-out chart in stages while paying an honest price for the elevated H-share multiple — and explicitly separating commentary’s ~27.7x figure from the HK listing’s 123.9x print.

    FAQ

    What does GigaDevice (03986) do?

    GigaDevice designs, develops and sells specialty memory chips, MCUs, sensor chips and analog chips. AASTOCKS lists the English name as GIGADEVICE. Dual listing: A-share 603986 (Shanghai) and H-share 03986 (HKEX, listed 13 Jan 2026).

    Why are market commentary notes talking about accumulating now?

    They flag a ~10% rebound after ~4 months of tech adjustment, H1 revenue +178.7% and profit +1091%, AI demand lifting storage prices, a >70% drawdown from ~1,248 toward ~300, and an SK Hynix shortage narrative through 2030 — arguing the name is worth accumulating after the deep correction.

    What are the key GigaDevice valuation numbers?

    At AASTOCKS 16:08 HKT on 29 Oct 2026 (HK$342.600, market Closed): TTM P/E 123.91x, P/B 11.28x, yield 0.25%, market cap HK$241.18B. RSI(14) ~38.9; chart MACD(12,26) −33.735 / signal −35.311 / div 1.577. Commentary cites ~27.7x TTM PE — that may be another share class or basis; do not treat HK TTM PE as 27.7x.

    What levels matter for 03986?

    Resistance HK$352.80–359.20, HK$374.92 (SMA20), HK$438.14 (SMA50), HK$549–564 (SMA150/100); support HK$334.20 (today’s low) then the ~300 / 220 band. Chart history starts 13 Jan 2026 — not a full calendar 1Y.

    Is this a buy after the AI storage rebound?

    That depends on your risk tolerance. Extreme H1 growth, AI storage demand, and a >70% drawdown support a staged-accumulate thesis, but the H-share TTM PE is 123.9x and the stock is still below the medium SMAs after today’s −4.6% giveback. Use levels; this is not financial advice.


    Disclaimer: For information only. Based on public market commentary notes and AASTOCKS data as of 29 Oct 2026 16:08 HKT (market Closed); data may be delayed. Chart history for 03986 starts at the H-share listing on 13 Jan 2026 and is not a full calendar 1-year window. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.
  • ZTO Express (02057): Market Share Up — Accumulate in Stages

    ZTO Express (02057): Market Share Up — Accumulate in Stages

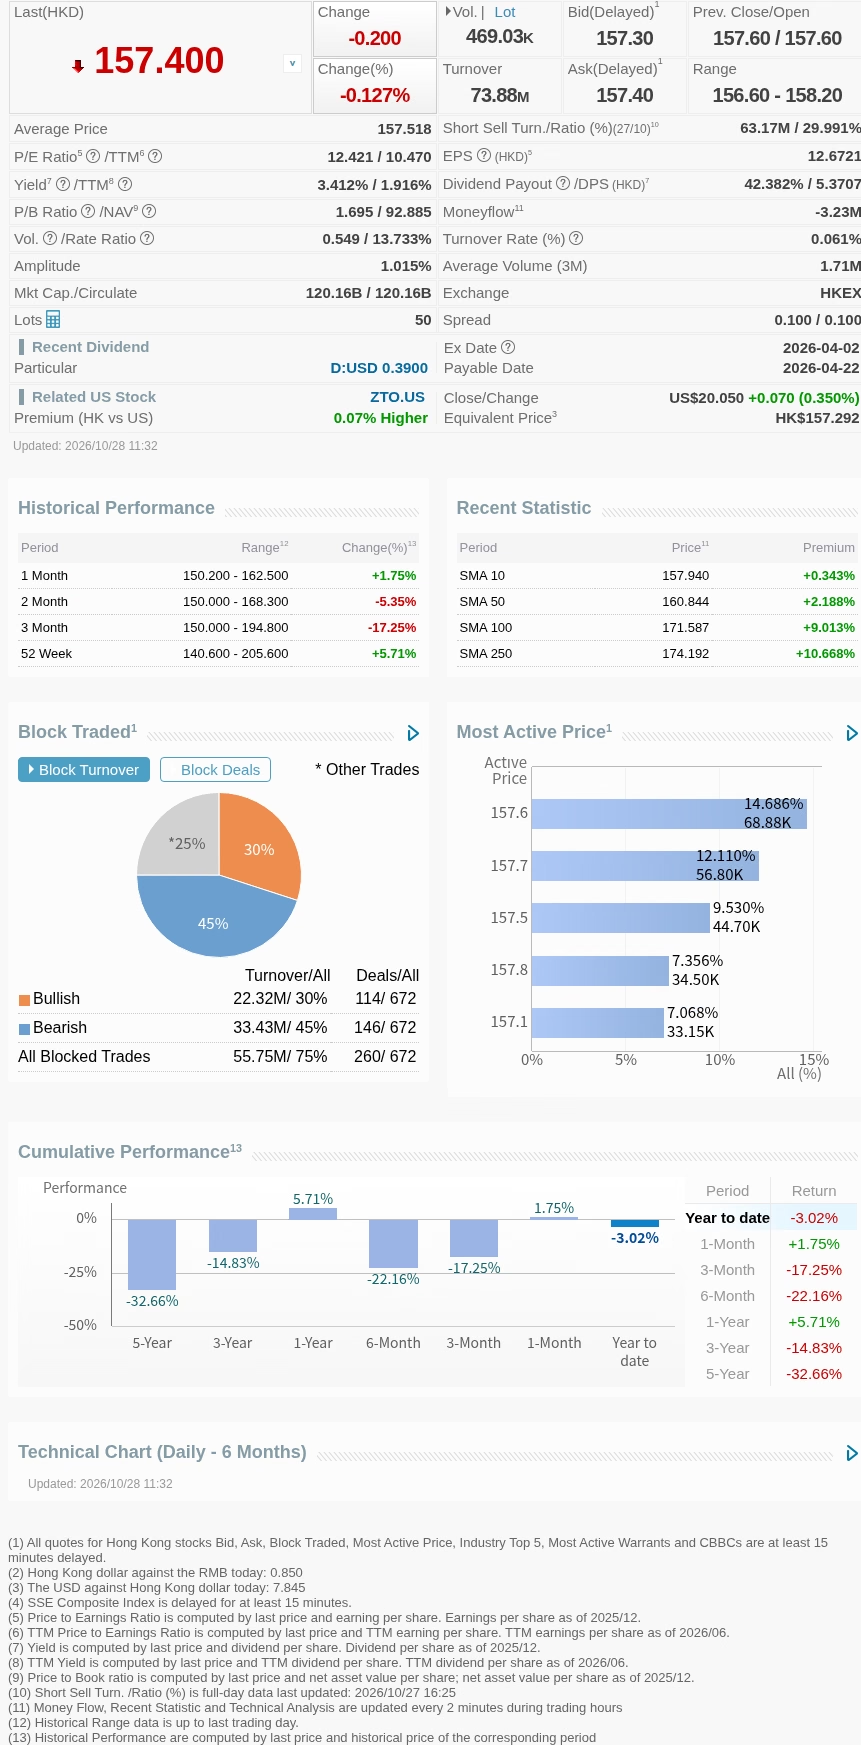
    ZTO Express (02057) — English name ZTO EXPRESS-W on AASTOCKS — traded near HK$157.400 mid-session on 28 Oct (−0.200 / −0.127%), after yesterday’s close at HK$157.60. This ZTO Express 02057 stock analysis asks the alpha question: with market share at 20.1% (+0.9ppt), H1 revenue +22.5% and profit +31.5%, and forward PE around 9.1x versus a five-year median of 12.8x, is the still-intact downward channel a stage-accumulate setup — or just more overhead supply waiting above?

    Market commentary notes say valuation is reasonable enough to accumulate in stages (分段吸納), citing share gains above industry volume growth, ASP lift, unit-cost deflation, and a forward multiple roughly 0.8 standard deviations below the five-year PE median.

    ZTO Express (02057) detailed quote on AASTOCKS, 28 Oct 2026 ~11:32 HKT
    Source: AASTOCKS, as of 28 Oct 2026 ~11:32 HKT

    The news in brief

    • Industry still growing, but slower (State Post Bureau, first 9M 2026). National express volume 151.3bn pieces (+4.3% YoY); industry revenue RMB 1.16tn (+7.2%). Inter-city 1371.8億件 = 137.18bn (+5.4%), about 90.7% of volume; same-city 110億件 = 11.0bn (−7.3%); intl / HK-Macau-Taiwan 31.2億件 = 3.12bn (+2.7%). Context: Jul 2025 price-law draft / anti-involution push; fee hikes and a stop to low-price market grabs; average express prices stabilized/rose from 2025 Q3 — a shift from pure price-war scale toward value, digital, green, and network intensity.
    • ZTO footprint (end-Jun 2026). Roughly 6,000 direct network partners; >31,000 pickup/delivery outlets; ~100,000 end stations; 92 sorting centers; 782 automated sorting lines; >3,600 trunk routes; >10,000 trunk vehicles; warehousing >2m sqm; coverage across all counties and 97% of townships, with overseas extension.
    • H1 2026 (RMB, 億 check). Revenue 278.3億 = RMB 27.83bn (+22.5% YoY) — express services 262.1億 (+24.2%), freight forwarding 3.7億 (+84.1%), materials 12億 (+0.5%). Parcel volume 201.54億件 = 20.154bn (+9.6%) — above industry average. Unit ticket / ASP +12.9%. Market share 20.1%, +0.9ppt. Direct-customer revenue +75.4%. Gross margin 25.9% (+0.2ppt). Unit transport cost −8.1%; trunk cost ratio −5ppt; sorting-center opex ratio −3ppt; S&A expense ratio −1.1ppt. Net profit 51.7億 = RMB 5.17bn (+31.5%). Operating cash flow ~73.5億 = RMB 7.35bn (+62.3%). Automated sorting lines +92 vs H1 2025.
    • Technical (commentary). Price still in a downward channel; momentum energy negative; outperformed HSI. If it breaks the channel top, overhead supply is limited (“上方籌碼少”) and a rally can sustain.
    • Valuation (commentary). Five-year PE median 12.8x; forward PE 9.1x, about 0.8 SD below median — valuation reasonable; conclusion: accumulate in stages at current levels.
    • Wednesday tape (AASTOCKS, updated 28 Oct 2026 ~11:32 HKT). Last HK$157.400 (−0.200 / −0.127%), prev 157.60, open 157.60, day 156.60–158.20. Market still open/moving; cite AASTOCKS and the timestamp. Related US ADR ZTO.US US$20.05; HK premium about 0.07%.

    Why market share and unit economics still matter

    ZTO is a classic China ecommerce express name: network partners, automated sorting, trunk fleets, and a rising direct-customer mix. Commentary’s point is not that the industry is booming at 20%+ — it isn’t (volume +4.3%) — but that ZTO is still taking share, lifting ASP, and cutting unit transport cost at the same time. That combination — volume above industry, ASP +12.9%, unit transport cost −8.1%, GPM 25.9% — is how you get profit +31.5% and OCF +62.3% while the sector cools from price-war mode into a more disciplined fee environment.

    The valuation overlay is patience, not chase: forward PE 9.1x vs a five-year median 12.8x (~0.8 SD below) is the “reasonable / stage accumulate” frame. Technically the stock is still inside a downward channel and has underperformed its own May highs near the HK$205 area, even as it has outperformed the HSI on the way down. That is a margin-of-safety plus share-gain story after a correction — not a momentum breakout until the channel top breaks.

    What still has to go right

    1. Share gains stick. 20.1% (+0.9ppt) has to keep compounding as industry volume growth stays mid-single-digit.
    2. ASP and cost discipline hold. Anti-involution fee stability plus further automation (sorting lines +92 YoY) need to protect the 25.9% GPM.
    3. Channel break confirms. A clean break of the downward-channel top, with limited overhead supply as the notes argue, is the technical unlock; until then this is staged buying into a still-bearish structure.

    ZTO Express 02057 stock analysis: valuation and key numbers

    MetricZTO Express (02057)
    Last price (28 Oct ~11:32)HK$157.400
    Day change−HK$0.200 (−0.127%)
    Prev close / openHK$157.60 / HK$157.60
    Day rangeHK$156.60 – 158.20
    52-week rangeHK$140.600 – 205.600
    Market cap / circulateHK$120.16B / 120.16B
    P/E / TTM P/E (EPS 12.672)12.421x / 10.470x
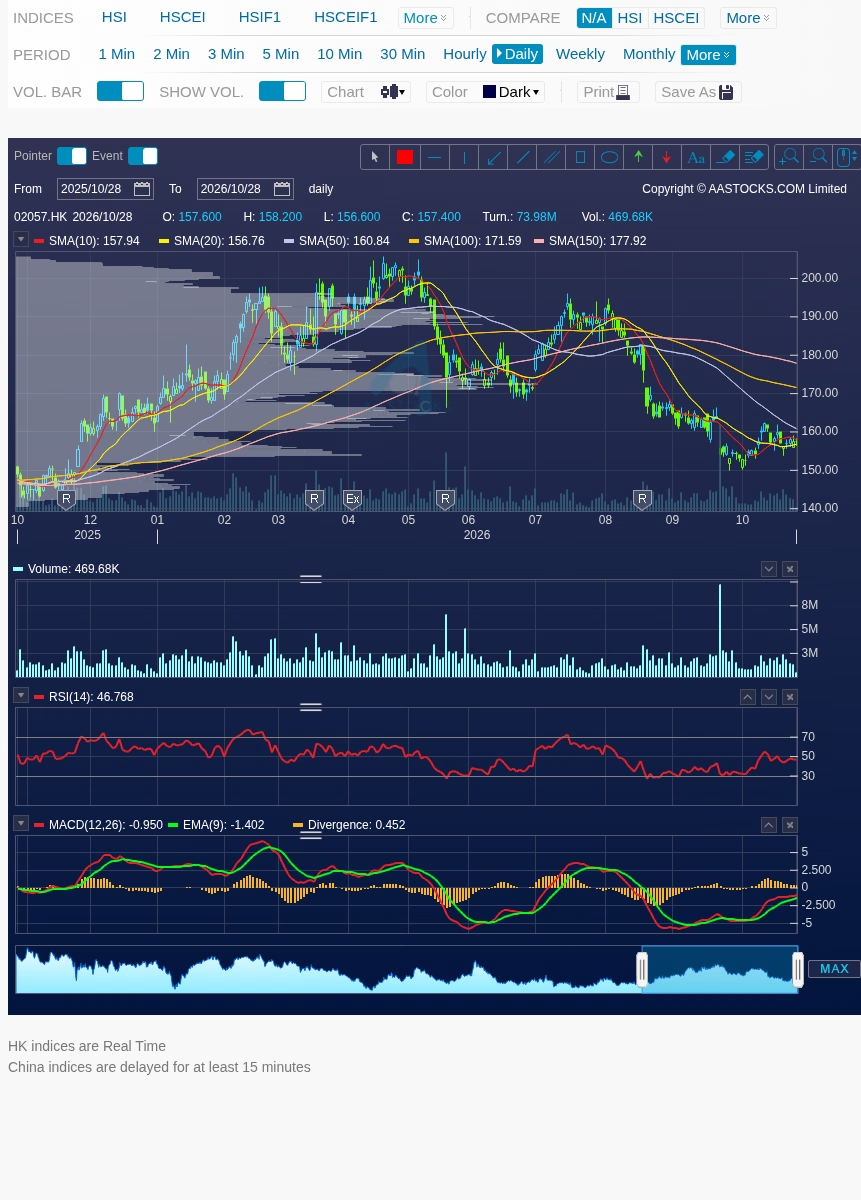
    P/B (NAV 92.885)1.695x
    Dividend yield / TTM / DPS3.412% / 1.916% / HK$5.3707
    Payout42.382%
    SMA 10 / 20 / 50157.940 / 156.76 / 160.844
    SMA 100 / 250171.587 / 174.192
    RSI 1446.768
    MACD (12,26) / signal / div−0.950 / −1.402 / 0.452
    Volume / turnover469.03K / HK$73.88M
    Short-sell ratio (27/10, full day)29.991%
    Data: AASTOCKS, updated 28 Oct 2026 11:32 HKT, market still open/moving. English name: ZTO EXPRESS-W. SMA10/50/100/250 from quote panel; SMA20 156.76 and MACD/RSI from chart. Related ZTO.US US$20.05; HK premium 0.07%.
    Operating / commentary checkpointsFigure
    Industry 9M vol / rev151.3bn pcs (+4.3%) / RMB 1.16tn (+7.2%)
    H1 revenue / YoYRMB 27.83bn / +22.5%
    H1 volume / ASP20.154bn pcs (+9.6%) / ASP +12.9%
    Market share20.1% (+0.9ppt)
    Gross margin25.9% (+0.2ppt)
    Unit transport cost−8.1%
    H1 net profit / OCFRMB 5.17bn (+31.5%) / RMB 7.35bn (+62.3%)
    Direct-customer rev+75.4%
    5y PE median → fwd PE12.8x → 9.1x (~0.8 SD below)
    Stance (commentary)Accumulate in stages
    Source: figures cited in market commentary notes; AASTOCKS for the quote table. 億 units converted: 278.3億 = RMB 27.83bn; 201.54億件 = 20.154bn pieces; 51.7億 = RMB 5.17bn; ~73.5億 = RMB 7.35bn; industry 1513億件 = 151.3bn.

    What the numbers tell us (our analysis):

    • Multiple is the accumulate argument. AASTOCKS trailing P/E 12.4x / TTM 10.5x sits next to commentary’s fwd 9.1x vs 12.8x median — this is a below-median quality logistics name, not a deep single-digit yield trade.
    • Yield is modest, not the floor. Trailing yield 3.41% (TTM 1.92%, DPS HK$5.37, payout ~42%) helps a little but is not the thesis.
    • Price is pinned under the longer SMAs. Last 157.40 is just under SMA10 157.94, slightly above SMA20 156.76, and well below SMA50 160.84 / SMA100 171.59 / SMA250 174.19 — medium-term stack still bearish.
    • RSI is neutral, not washed-out. RSI(14) 46.8 is mid-band — room for either a grind toward the channel top or another shakeout.
    • MACD is negative but improving. MACD −0.950 vs signal −1.402 (div +0.452) shows the histogram turning less bearish even while both lines sit under zero.
    • Shorts are elevated. Full-day short-sell ratio ~30% (27 Oct) can fuel either a squeeze on a channel break or another flush if the industry softens.

    Technical analysis: still in the channel, HSI-relative strength

    ZTO Express (02057) 1-year daily chart on AASTOCKS
    Source: AASTOCKS, as of 28 Oct 2026 ~11:32 HKT

    The one-year AASTOCKS chart is a round trip from the ~HK$205 May area into the mid-150s, with a late-year bounce off the ~HK$140–145 zone. Price is still inside the commentary’s downward channel; the notes argue a break of the channel top meets limited overhead supply, which is the technical unlock for a sustained rally. Relative to the Hang Seng, the stock has outperformed even while absolute momentum stayed soft.

    • First job: hold SMA20, then reclaim SMA10 / SMA50. Near-term pivot is HK$156.76 (SMA20) and HK$157.94 (SMA10); next resistance HK$160.84 (SMA50), then the heavier SMA100 / SMA250 band around 171–174.
    • Channel / commentary unlock. A break of the downward-channel top is the notes’ condition for a durable rally given “上方籌碼少.”
    • Support. Day low HK$156.60, then the September base toward HK$140.60 (52w low). A sustained break of the mid-150s would pause the stage-accumulate sizing for us until a new base forms.
    • RSI 46.8 is neutral fuel; MACD divergence +0.452 is the early constructive tell, not yet a trend flip.

    Levels: first resistance HK$157.94 (SMA10) and HK$160.84 (SMA50); heavier supply HK$171–174 (SMA100/250); support HK$156.60 (today’s low) then the HK$140–145 base.

    Bull case vs bear case

    Bull case

    • Market share 20.1% (+0.9ppt) with volume +9.6% vs industry +4.3% — still taking share in a slower market.
    • ASP +12.9%, unit transport cost −8.1%, GPM 25.9%, profit +31.5%, OCF +62.3% — unit economics compounding.
    • Direct-customer revenue +75.4% lifts mix toward higher-value clients and reverse logistics.
    • Forward PE 9.1x vs five-year median 12.8x (~0.8 SD below) — commentary’s stage-accumulate valuation frame.
    • Outperformed HSI inside the channel; MACD histogram improving (div +0.452); channel-top break = limited overhead supply per notes.

    Bear case

    • Price still below SMA50 / SMA100 / SMA250; absolute structure remains a downward channel.
    • Industry volume growth only +4.3% — any re-acceleration of price competition would hit ASP and GPM.
    • Short-sell ratio near 30% and a soft RSI mid-band leave room for another flush before any channel break.
    • Trailing yield ~3.4% is not a hard floor; ADR/H-share basis can wobble (HK premium only ~0.07% today).
    • “Accumulate in stages” fails if the mid-150s base breaks toward the HK$140 52w low without a new fundamental offset.

    Levels to watch

    1. HK$156.60–156.76 (day low / SMA20). Near-term floor — hold vs break decides whether staged buying has a tape floor today.
    2. HK$157.94 (SMA10). First reclaim for any short-term bounce to look real.
    3. HK$160.84 (SMA50). Intermediate trend repair and likely channel-adjacent resistance.
    4. HK$171.59 / 174.19 (SMA100 / SMA250). Heavier moving-average supply after the May–Sep slide.
    5. Downward-channel top. Commentary’s breakout condition — limited overhead supply if cleared.
    6. Industry ASP / anti-involution fees and share vs peers. Fundamental swing factors behind the 9.1x accumulate thesis.

    The DimSumInsider take

    ZTO Express is a share-gaining China express name with below-median forward PE after a correction from the ~HK$205 highs into the mid-150s — not a crushed single-digit P/E yield play. The fundamental print (H1 rev +22.5%, volume +9.6%, share 20.1%, ASP +12.9%, unit transport −8.1%, profit +31.5%) supports the commentary’s stage accumulate frame at fwd PE 9.1x vs 12.8x median, while the technical still asks for patience inside a downward channel. Our approach: treat HK$156.60–160.84 as the prove-it band for staged entries, keep the channel-top break as the confirmation for size-up, and respect open air under the mid-150s toward the HK$140 base. The alpha is buying share gains and unit-cost deflation in stages while the tape decides whether this correction was a re-rating gift or just more channel work.

    FAQ

    What does ZTO Express (02057) do?

    ZTO Express is a Hong Kong-listed China express-delivery and logistics operator with a large partner network, automated sorting, trunk routes, and rising direct-customer / reverse-logistics mix tied to ecommerce. AASTOCKS lists the English name as ZTO EXPRESS-W.

    Why are market commentary notes talking about accumulating now?

    They flag market share at 20.1% (+0.9ppt), H1 profit +31.5% with ASP and cost gains, a forward PE of 9.1x about 0.8 SD below the five-year median of 12.8x, and a still-intact downward channel that has nonetheless outperformed the HSI — arguing valuation is reasonable for staged buying.

    What are the key ZTO Express valuation numbers?

    At AASTOCKS ~11:32 HKT on 28 Oct 2026 (HK$157.400): P/E 12.42x, TTM P/E 10.47x, P/B 1.70x, yield 3.41%, market cap HK$120.16B. RSI(14) 46.8; MACD(12,26) −0.950 / signal −1.402 / div 0.452. Commentary forward PE ~9.1x vs 12.8x median.

    What levels matter for 02057?

    Resistance HK$157.94 (SMA10), HK$160.84 (SMA50), HK$171–174 (SMA100/250), plus the downward-channel top; support HK$156.60 (today’s low) then the HK$140–145 base.

    Is this a buy after the H1 beat?

    That depends on your risk tolerance. Share gains, ASP/cost leverage, and a below-median forward PE support a staged-accumulate thesis, but the stock is still in a downward channel under the longer SMAs. Use levels; this is not financial advice.


    Disclaimer: For information only. Based on public market commentary notes and AASTOCKS data as of 28 Oct 2026 ~11:32 HKT (market still open/moving); data may be delayed. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.