When momentum money dumps memory, optical-comms and compute names, most traders see a sector rolling over. The sharper move is to watch where that money lands. In Hong Kong’s AI trade, one name keeps holding up on the strength screens while its hardware cousins fade: Kingsoft (03888).
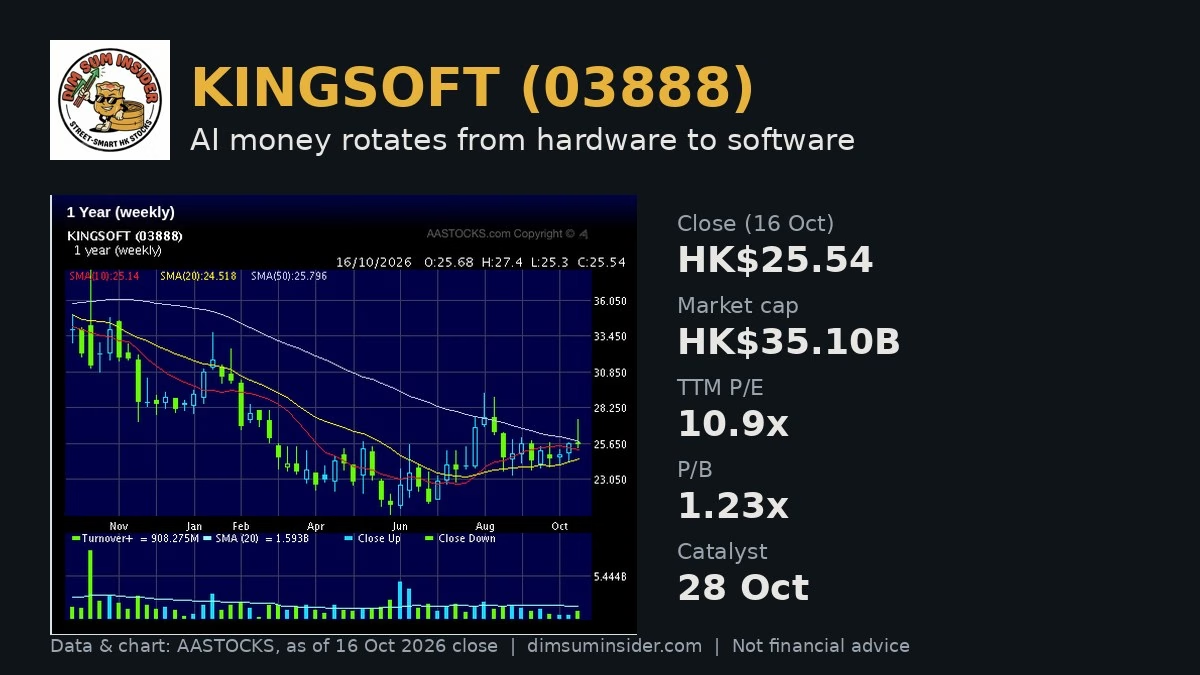
It closed Friday 16 Oct at HK$25.54, quiet on the surface, but it is now one of the cleaner software-versus-hardware tests on HKEX, with one catalyst date: 28 Oct.
The news in brief
- Market commentary published around 17 Oct 2026 suggests HK AI hardware is weakening across the board, with memory, optical comms and compute equipment hit in turn.
- Kingsoft (03888) has stayed firm among names with a relative-strength (RS) score above 70. The bull case reads this as money rotating inside the AI camp, from hardware to software.
- Street chatter frames Kingsoft as a top long pick: hold if it stays steady before 28 Oct, when Microsoft reports FY2027 Q1 and Kingsoft Office (688111.SH), a Kingsoft subsidiary, is expected to report Q3 2026 results.
- Diary note: the Hong Kong market is closed on Monday 19 Oct 2026 for a holiday and reopens Tuesday 20 Oct.
Why money is rotating from AI hardware to software
The bull case argues the rotation has fundamental support, not just sector noise. By some estimates, Copilot has more than 30 million paid users and Azure revenue grew 43%. AI, the argument goes, has moved “from a capex story to a P&L story”.
The key idea is a dual-track revenue model: the office entry point charges a subscription, and the cloud charges inference fees. Once both are proven, the market cares less about whose model is strongest and more about who owns the enterprise office entry point and the paying relationship.
Our read: hardware gets paid while everyone builds; software gets paid once customers use what was built. The question is not “is AI over?” but “who collects the recurring revenue now?”
Fundamentals: WPS 365 and the Microsoft analogy
One useful frame maps the Kingsoft group onto Microsoft’s two rings: Kingsoft Cloud as the Azure compute ring and WPS as the Office entry ring, each priced independently.
The group’s office business reports:
- WPS 365 revenue growth above 60% for several consecutive quarters. Q2 2026 revenue was RMB253m, up 61% year on year.
- 1H2026 gross margin of 90.88%.
- 48.25 million cumulative annual paying individual users as of June 2026.
- More than 80.13 million domestic WPS AI monthly active users and more than 200 billion average daily token calls as of end-2025.
These figures relate to the office business (Kingsoft Office, 688111.SH, a Kingsoft subsidiary), not to 03888 at group level.
The point is margin. As the bull case argues, software subscription converts AI revenue into profit far better than asset-heavy compute rental. At around 90% gross margin, most of each extra yuan of AI revenue reaches gross profit.
Valuation and key numbers
| Metric | Kingsoft (03888) |
|---|---|
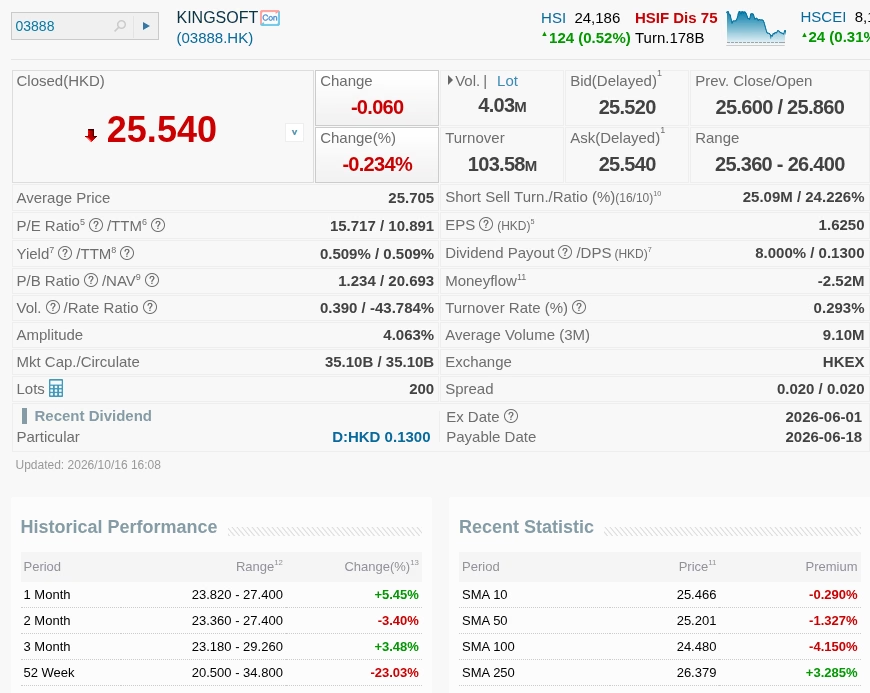
| Last price (16 Oct close) | HK$25.54 |
| Day change | -HK$0.06 (-0.23%) |
| 52-week range | HK$20.50 – 34.80 |
| 1-year / YTD performance | -23.03% / -10.20% |
| Market cap | HK$35.10B |
| P/E (FY2025, EPS HK$1.625) | 15.72x |
| TTM P/E | 10.89x |
| Dividend yield (DPS HK$0.13) / payout | 0.51% / 8% |
| P/B (NAV/share HK$20.693) | 1.23x |
| SMA 10 / 50 / 100 / 250 | 25.47 / 25.20 / 24.48 / 26.38 |
| RSI (14) | 53.7 |
| MACD (12/25) | 0.23, bullish |
| Volume vs 3M average | 4.03M vs 9.10M |
| Short-selling share of turnover | 24.2% (HK$25.09M) |
What the numbers tell us (our analysis):
- The P/E gap signals earnings growth. A 15.7x historical P/E against 10.9x TTM implies trailing earnings well above FY2025. Working back from the price, TTM EPS is roughly HK$2.35 against HK$1.625.
- Close to book. A P/B of 1.23x is undemanding for a group with a 90%-gross-margin subscription engine inside it.
- Not an income stock. An 8% payout and about 0.5% yield mean you are paid for growth, not dividends.
Technical picture
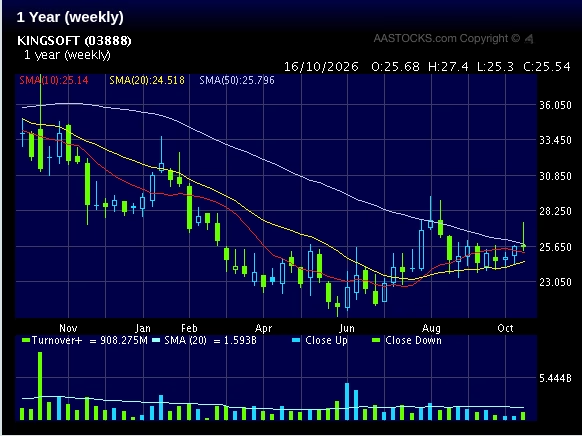
Down 23% over a year, the stock has stopped bleeding: +5.45% over one month, +3.48% over three and +3.82% over six. At HK$25.54 it sits just above its 10-, 50- and 100-day SMAs but about 3% below the 250-day line at HK$26.38. RSI at 53.7 is neutral and MACD reads bullish. The price chart shows a low near HK$21 in June, a spike towards HK$29 in August, and consolidation around the short and medium averages since.
Two flags: Friday’s 4.03M shares was less than half the 9.10M 3-month average, and short selling was about 24% of turnover. Light volume fits a pre-catalyst wait, but a real breakout needs a close above the 250-day SMA on volume; the short share says the bears are still here.
The competitive threat: Tencent WorkBuddy
On Wednesday 14 Oct, Tencent (00700) deeply integrated WorkBuddy with WeCom, reaching contacts at 14 million enterprises. WorkBuddy had more than 20 million monthly visits in June and ranks No.1 among mainland office agents.
One framing: Microsoft relies on subscription, Tencent on super-app distribution, and Kingsoft wins on the document execution layer and model neutrality. If entry-point players become the default agent, WPS risks being squeezed into an execution tool. Then again, giants rushing in shows enterprise AI office monetisation has arrived.
For context, Tencent closed at HK$417.80, near its 52-week low of HK$411.00 and below its 50-day (438.12) and 250-day (516.55) SMAs, at 15.2x P/E (14.1x TTM), 2.97x book and a 1.27% yield. Its HK$3,798.90B market cap is roughly 108 times Kingsoft’s. Data: AASTOCKS, as of 16 Oct 2026 close. Tencent has the distribution; right now, Kingsoft has the relative strength.
Catalysts: what to watch on 28 Oct
Microsoft’s FY2027 Q1 and Kingsoft Office’s Q3 2026 results are expected on the same day. For Microsoft, the question is whether Copilot growth holds and whether “subscription + Copilot Credits usage fees” shows quantifiable revenue. Microsoft has moved Cowork, Code and Autopilot agent scenarios to usage billing (default usage billing for some new Copilot Business licences was pushed from 2 Nov to 1 Dec). If dual-track is proven, AI office pricing shifts from “per user per month” to “per user per month + per agent task”.
For Kingsoft Office, three lines to watch:
- Office revenue. Not the 24.7% 1H growth, but whether the AI agent Lingxi (靈犀) scales up in 2H.
- WPS 365. Is 60%+ growth intact, with concrete “subscription + AI usage” revenue or usage figures?
- Gross margin. Does it hold near the 1H level of 90.88%?
Hard numbers mean AI becomes revenue; without them, the stock may consolidate for a while.
Games are a bonus, not the main course: an Angry Birds movie tie-in returns in December, and the JX3 (劍網3) graphics upgrade comes next year.
Risks
- 28 Oct disappointment. No quantified AI revenue could mean a period of consolidation.
- Platform squeeze. Tencent’s WeCom distribution could push WPS down to an execution layer.
- Technicals. The 250-day SMA is overhead, volume is light and short selling is heavy.
- Structure. 03888 is a holding group, not a pure WPS play; office-business figures do not map one-for-one to group value.
- Read-across. Weak Microsoft Copilot numbers would hit the whole software thesis.
The DimSumInsider take
Clear thesis, hard date, measurable outcome. Kingsoft offers AI-software exposure at 10.9x TTM P/E and 1.2x book, with a 90%-margin subscription engine in the group and relative strength while hardware bleeds. Position by the calendar, not by feel: holding into 28 Oct is a bet on office revenue, WPS 365 and gross margin. A close above the 250-day SMA (HK$26.38) on volume would confirm it. No hard AI-usage numbers, and expect the range to persist. The alpha is in knowing exactly what you are waiting for.
FAQ
Why is Kingsoft (03888) outperforming HK AI hardware stocks?
Market commentary suggests AI money is rotating from hardware to software, backed by WPS 365 growth and high margins in the group’s office business.
When is the next catalyst for Kingsoft?
28 Oct 2026: Microsoft’s FY2027 Q1 and Kingsoft Office’s (688111.SH) expected Q3 results. HKEX is closed on 19 Oct.
Is Kingsoft expensive?
Per AASTOCKS (16 Oct 2026 close): 15.7x P/E, 10.9x TTM P/E, 1.23x book, 0.51% yield.
Disclaimer: For information only. Based on public market commentary and AASTOCKS data as of 16 Oct 2026 close; data may be delayed. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.