GigaDevice (03986) — English name GIGADEVICE on AASTOCKS — closed at HK$342.600 on 29 Oct (−16.600 / −4.621%), giving back part of the prior session’s ~10% rebound that left the previous close at HK$359.20. This GigaDevice 03986 stock analysis asks the alpha question: after a >70% slide from the ~HK$1,248 high toward the ~300 area, with H1 revenue +178.7% and net profit +1091%, and AI demand lifting specialty-memory prices, is the bounce a stage-accumulate setup — or just a bear-market rally under a still-elevated H-share multiple?
Market commentary notes flag the storage-chip leader’s rebound after roughly four months of tech adjustment, cite an SK Hynix shortage narrative through 2030, and argue a staged accumulate after the deep drawdown. For the HK listing, AASTOCKS shows TTM P/E 123.9x and P/B 11.3x — not the ~27.7x figure that appears in some commentary (that may refer to a different share class or basis; see dual-listing note below). Stance can still be staged accumulate into the growth story, with eyes open on the high H-share multiple and soft technicals.
The news in brief
- Business. Designs, develops and sells specialty memory, MCUs, sensor chips and analog chips. Commentary ties the rebound thesis to rapid AI growth lifting storage-chip prices.
- H1 (RMB, 億 check). Revenue 115.66億 = RMB 11.566bn (+178.7% YoY); net profit 68.57億 = RMB 6.857bn (+1091% YoY). Near-term profit growth may slow, but AI demand is described as firm and longer-term potential constructive.
- Tape / drawdown. From a high near ~1,248 toward ~300 — drawdown >70% amid AI-infra growth skepticism. Prior session bounced nearly 10% (prev close 359.20); today gave back −4.6% to 342.60.
- Sector narrative (commentary). SK Hynix shortage expected through 2030 → sector stabilizing / rebounding after the multi-month tech adjustment.
- Valuation (critical). Commentary cites TTM PE ~27.7x as reasonable vs semiconductor-design peers and concludes accumulate. AASTOCKS H-share (03986) TTM PE is 123.910 / P/B 11.283 — use that for the HK listing. Dual listing: A-share 603986 (SH) / H-share 03986 (HK, listed 13 Jan 2026). The ~27.7x figure may refer to a different share class or basis; do not treat HK TTM PE as 27.7x.
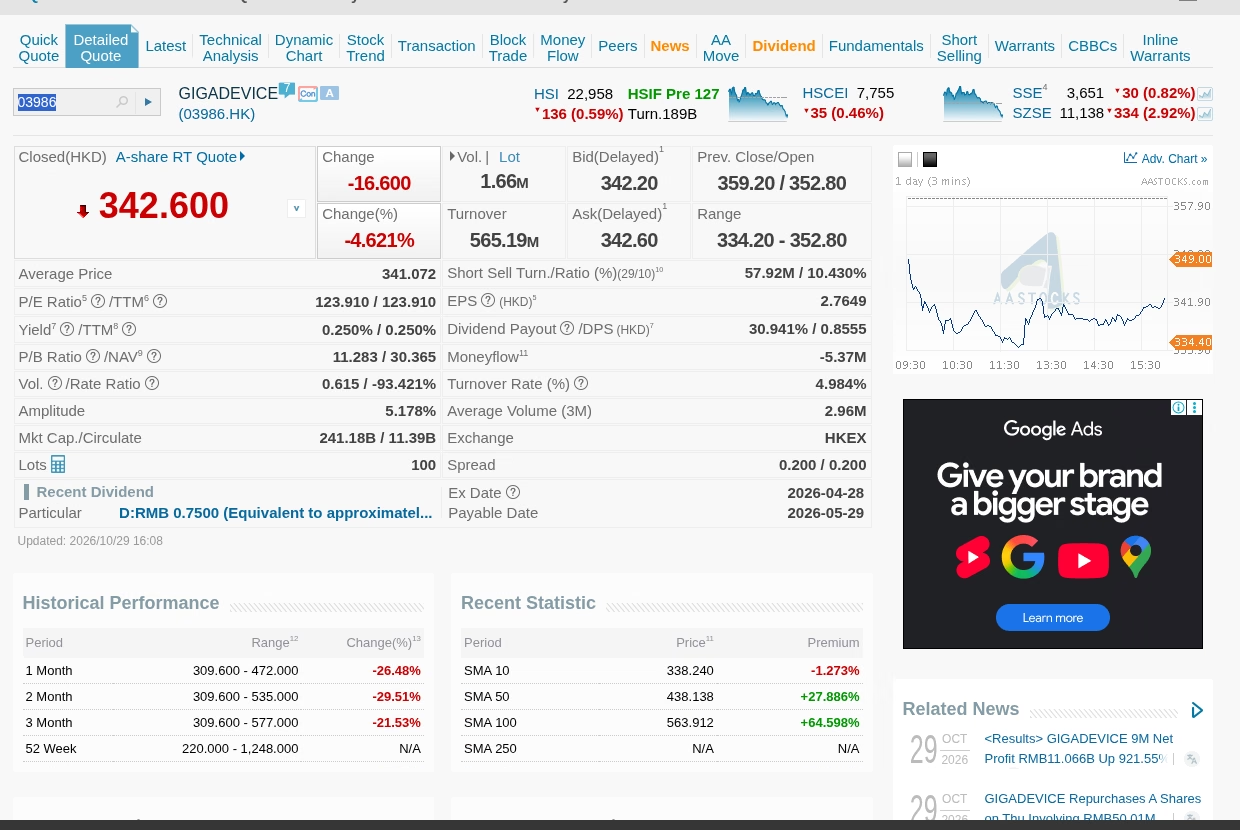
- Thursday close (AASTOCKS, updated 29 Oct 2026 16:08 HKT). Last HK$342.600 (−16.600 / −4.621%), prev 359.20, open 352.80, day 334.20–352.80, vol 1.66M, turnover HK$565.19M. Market Closed. Chart history starts at listing 2026/01/13 (not a full calendar 1Y; SMA250 N/A).
Why AI storage and the drawdown still matter
GigaDevice is a China specialty-memory / MCU / sensor / analog design name — not a pure foundry story. Commentary’s point is that after a brutal multi-month tech washout, AI demand is again lifting storage prices, H1 prints were extreme (+178.7% / +1091%), and the stock has already paid a >70% drawdown from the mid-year spike. That is a margin-of-safety plus AI-storage demand frame after a correction — not a cheap H-share multiple story.
The valuation overlay needs honesty: AASTOCKS H-share TTM PE 123.9x and P/B 11.3x are rich for a post-IPO H listing still under a year old. Commentary’s accumulate call leans on growth runway and the ~27.7x peer framing (likely another basis / A-share context). Our approach: respect the growth + drawdown case for staged buying, but size as if you are paying a high H-share multiple into a stock still below SMA50 / SMA100 with MACD bearish.
What still has to go right
- AI storage prices stay firm. Specialty-memory ASP and volume need to keep validating the H1 surge as AI demand, not a one-off inventory flush.
- H-share multiple compresses into earnings. At 123.9x TTM, the accumulate thesis needs profit growth (or A/H basis clarity) to catch up — not just another bounce.
- Technical repair. Reclaim SMA20 374.92 then SMA50 438.14; a sustained break of the ~334 day-low / ~300 commentary zone would pause staged sizing until a new base forms.
GigaDevice 03986 stock analysis: valuation and key numbers
| Metric | GigaDevice (03986) |
|---|---|
| Last price (29 Oct 16:08) | HK$342.600 |
| Day change | −HK$16.600 (−4.621%) |
| Prev close / open | HK$359.20 / HK$352.80 |
| Day range | HK$334.20 – 352.80 |
| 52-week range | HK$220.000 – 1,248.000 |
| Market cap / circulate | HK$241.18B / 11.39B |
| P/E / TTM P/E (EPS 2.7649) | 123.910x / 123.910x |
| P/B (NAV 30.365) | 11.283x |
| Dividend yield / TTM / DPS | 0.250% / 0.250% / HK$0.8555 |
| Payout | 30.941% |
| SMA 10 / 20 / 50 | 338.24 / 374.92 / 438.14 |
| SMA 100 / 150 / 250 | 563.91 / 549.40 / N/A |
| RSI 14 | 38.94 |
| MACD (12,26) / signal / div | −33.735 / −35.311 / 1.577 |
| Volume / turnover | 1.66M / HK$565.19M |
| Short-sell ratio (29/10, full day) | 10.430% |
| Operating / commentary checkpoints | Figure |
|---|---|
| H1 revenue / YoY | RMB 11.566bn / +178.7% |
| H1 net profit / YoY | RMB 6.857bn / +1091% |
| Business mix | Specialty memory, MCU, sensors, analog |
| AI / storage narrative | AI demand lifting storage-chip prices |
| Drawdown from high | ~1,248 → ~300 (>70%) |
| Sector note | SK Hynix shortage narrative through 2030 |
| Commentary TTM PE (notes) | ~27.7x — may be other class/basis |
| HK H-share TTM PE (AASTOCKS) | 123.9x |
| Dual listing | A 603986 / H 03986 (listed 13 Jan 2026) |
| Stance (commentary) | Accumulate (staged after drawdown) |
What the numbers tell us (our analysis):
- H-share multiple is the risk, not the accumulate argument. AASTOCKS TTM P/E 123.9x / P/B 11.3x sit far above commentary’s ~27.7x framing — treat the HK listing as expensive growth, and assume the lower figure may be A-share or another basis.
- Yield is not the floor. Trailing yield 0.25% (DPS HK$0.8555, payout ~31%) is incidental.
- Price is under the medium SMAs, just above SMA10. Last 342.60 is slightly above SMA10 338.24, well below SMA20 374.92 / SMA50 438.14 / SMA100 563.91 / SMA150 549.40 — medium-term stack still bearish.
- RSI is soft, not washed-out. RSI(14) ~38.9 is below mid-band — room for either a grind toward SMA20 or another shakeout under 334.
- MACD still bearish, histogram improving. MACD −33.735 vs signal −35.311 (div +1.577) shows a less-negative histogram while both lines sit deep under zero — early constructive tell, not a trend flip.
- Today’s −4.6% is a bounce giveback. Prior close 359.20 (~+10% session) failed to hold; vol 1.66M vs 3M avg 2.96M — not a panic flush, but not confirmed follow-through either.
Technical analysis: listing-to-date mountain, not a full 1Y
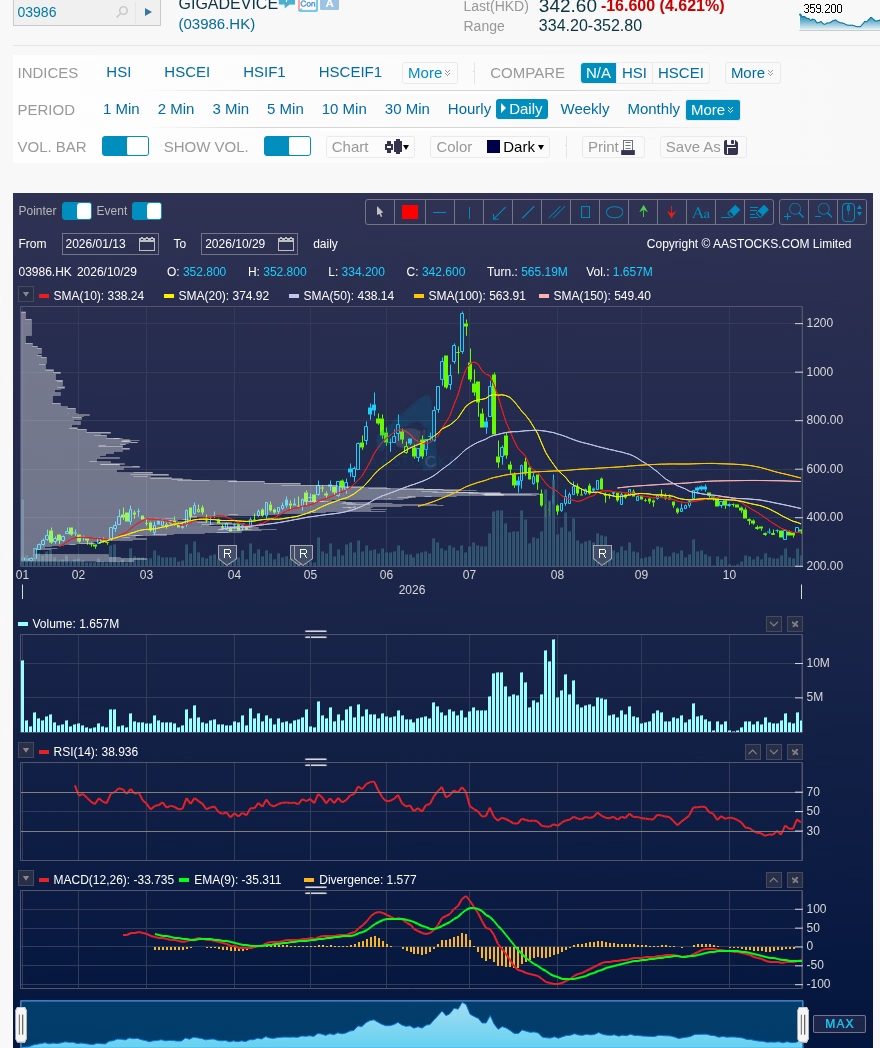
The AASTOCKS daily chart only loads from the H-share listing on 2026/01/13 through 2026/10/29 (~9.5 months) — there is no full calendar 1-year history yet (SMA250 N/A; 1Y return N/A on the quote page). What it shows is a classic post-IPO mountain: IPO area / early base near the low-200s, a vertical run into the ~1,248 high, then a multi-month collapse back toward the ~300–350 band. Today’s bar (O/H/L/C 352.80 / 352.80 / 334.20 / 342.60) sits just above SMA10 and well under SMA20–150.
- First job: hold above day low / ~300 zone, then reclaim SMA20. Near-term pivot is HK$334.20 (today’s low) and the commentary ~300 area; next resistance HK$374.92 (SMA20), then HK$438.14 (SMA50).
- Heavier supply. SMA100 563.91 / SMA150 549.40 — the mid-year distribution zone.
- Support. Day low HK$334.20, then the post-listing / 52w low area toward HK$220. A sustained break of the low-330s would pause the stage-accumulate sizing for us until a new base forms.
- RSI ~38.9 is soft fuel; MACD div +1.577 is the early constructive tell, not yet a trend flip.
Levels: first resistance HK$352.80 (day high / open) and HK$374.92 (SMA20); heavier HK$438.14 (SMA50) then ~550–564 (SMA150/100); support HK$334.20 then the ~300 / 220 band.
Bull case vs bear case
Bull case
- H1 revenue +178.7% and net profit +1091% — extreme operating leverage into AI/storage demand.
- Specialty memory + MCU + sensors + analog mix sits in the AI hardware stack, not just one product cycle.
- >70% drawdown from ~1,248 toward ~300 resets a lot of froth after the mid-year spike.
- SK Hynix shortage narrative through 2030 and sector rebound chatter after ~4 months of tech adjustment.
- RSI soft (~38.9); MACD histogram improving (div +1.577); prior session showed a ~10% bounce is still possible.
Bear case
- H-share TTM PE 123.9x / P/B 11.3x — expensive even after the drawdown; commentary’s ~27.7x is not the HK listing print.
- Price still below SMA20 / SMA50 / SMA100 / SMA150; absolute structure remains a post-spike collapse.
- Today’s −4.6% giveback after the bounce shows overhead supply is real near 350–360.
- Near-term profit growth may slow (per commentary); any AI-infra demand disappointment hits a high multiple hard.
- Chart window is short (listed 13 Jan 2026) — limited SMA history; SMA250 N/A; “1Y chart” captions must say listing-to-date.
Levels to watch
- HK$334.20 (day low). Near-term floor — hold vs break decides whether staged buying has a tape floor after the giveback.
- HK$352.80–359.20 (day high / prior close). Bounce-zone supply; reclaim needed to repair today’s −4.6%.
- HK$374.92 (SMA20). First medium-term repair level.
- HK$438.14 (SMA50). Intermediate trend repair after the multi-month slide.
- HK$549–564 (SMA150 / SMA100). Heavier moving-average supply from the mid-year distribution.
- AI storage ASP / H1→FY profit trajectory and A/H PE basis. Fundamental swing factors behind any accumulate thesis at 123.9x H-share TTM.
The DimSumInsider take
GigaDevice is an AI-storage / specialty-memory design name after a >70% drawdown from the ~1,248 high — not a cheap H-share multiple. The fundamental print (H1 rev +178.7%, profit +1091%) and the storage-shortage narrative support commentary’s accumulate frame, while AASTOCKS H-share TTM PE 123.9x / P/B 11.3x and a still-bearish SMA stack demand staged sizing and patience. Our approach: treat HK$334–375 as the prove-it band for staged entries after today’s giveback, keep a reclaim of SMA20 / SMA50 as confirmation for size-up, and respect open air under 334 toward the ~300 / 220 band. The alpha is buying AI storage demand and a washed-out chart in stages while paying an honest price for the elevated H-share multiple — and explicitly separating commentary’s ~27.7x figure from the HK listing’s 123.9x print.
FAQ
What does GigaDevice (03986) do?
GigaDevice designs, develops and sells specialty memory chips, MCUs, sensor chips and analog chips. AASTOCKS lists the English name as GIGADEVICE. Dual listing: A-share 603986 (Shanghai) and H-share 03986 (HKEX, listed 13 Jan 2026).
Why are market commentary notes talking about accumulating now?
They flag a ~10% rebound after ~4 months of tech adjustment, H1 revenue +178.7% and profit +1091%, AI demand lifting storage prices, a >70% drawdown from ~1,248 toward ~300, and an SK Hynix shortage narrative through 2030 — arguing the name is worth accumulating after the deep correction.
What are the key GigaDevice valuation numbers?
At AASTOCKS 16:08 HKT on 29 Oct 2026 (HK$342.600, market Closed): TTM P/E 123.91x, P/B 11.28x, yield 0.25%, market cap HK$241.18B. RSI(14) ~38.9; chart MACD(12,26) −33.735 / signal −35.311 / div 1.577. Commentary cites ~27.7x TTM PE — that may be another share class or basis; do not treat HK TTM PE as 27.7x.
What levels matter for 03986?
Resistance HK$352.80–359.20, HK$374.92 (SMA20), HK$438.14 (SMA50), HK$549–564 (SMA150/100); support HK$334.20 (today’s low) then the ~300 / 220 band. Chart history starts 13 Jan 2026 — not a full calendar 1Y.
Is this a buy after the AI storage rebound?
That depends on your risk tolerance. Extreme H1 growth, AI storage demand, and a >70% drawdown support a staged-accumulate thesis, but the H-share TTM PE is 123.9x and the stock is still below the medium SMAs after today’s −4.6% giveback. Use levels; this is not financial advice.
Disclaimer: For information only. Based on public market commentary notes and AASTOCKS data as of 29 Oct 2026 16:08 HKT (market Closed); data may be delayed. Chart history for 03986 starts at the H-share listing on 13 Jan 2026 and is not a full calendar 1-year window. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.