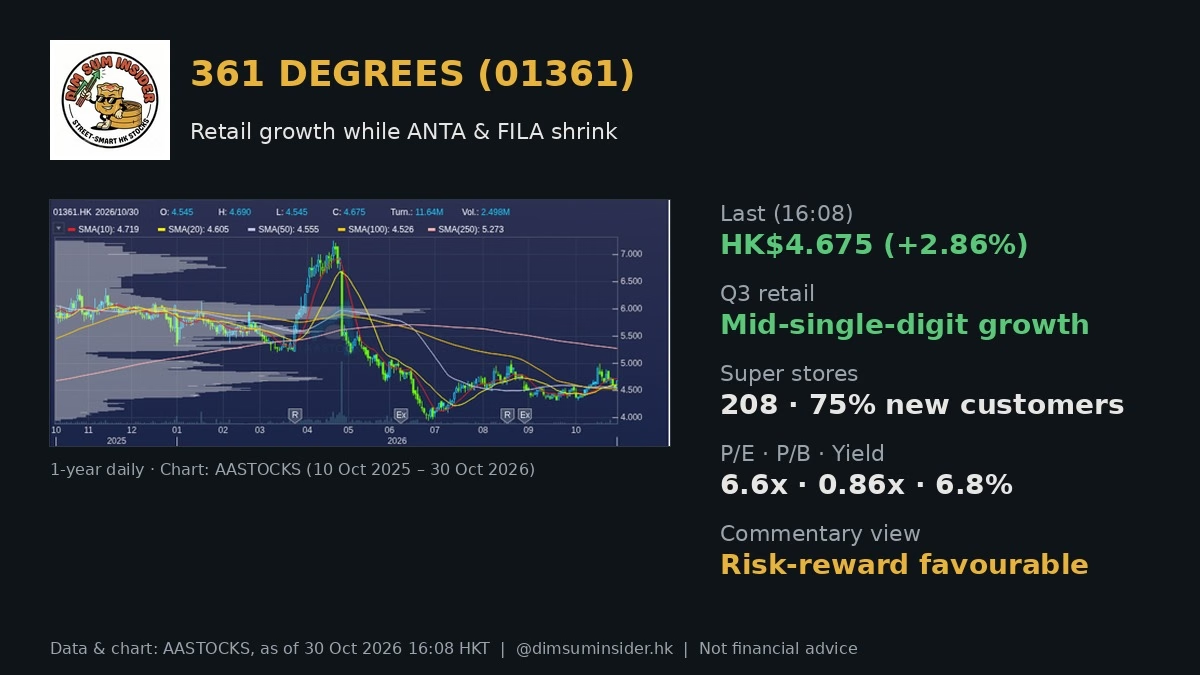
361 Degrees (01361), listed as 361 DEGREES on AASTOCKS, closed at HK$4.675 on Friday 30 Oct, up HK$0.130 (+2.86%). This 361 Degrees 01361 stock analysis asks the alpha question. In a quarter when the big China sportswear names went backwards, 361 kept growing. At about 6.6x earnings, 0.86x book and a ~6.8% trailing yield, is that enough to earn a re-rating?
Market commentary notes argue it is: retail is outrunning peers, the super-store rollout is pulling in genuinely new customers, and discounts are holding. Their view is that the risk-reward is favourable. The stock does not have to rally hard, but the downside looks limited. We broadly agree, with two caveats: the RMB and a high base.
The news in brief
- Q3 retail sales. Main-brand and kids offline retail both grew at a mid-single-digit rate. E-commerce grew at a mid-to-high single-digit rate.
- Peers went the other way. In the same week, the ANTA brand (02020) fell by a mid-single digit and FILA fell by a low-single digit. Li Ning (02331) and Xtep (01368) were expected to report slight declines.
- Super stores. 21 opened in Q3, for 208 on the mainland, and the full-year opening target was hit early. The share of new customers at these stores rose from about 65% to 75%, so three in every four shoppers are new to the brand.
- Discount and inventory. The offline discount was about 30% off, a touch deeper than roughly 29% off in Q2. The inventory-to-sales ratio held at 4.5–5x.
- Overseas. Management targets overseas at about 30% of revenue within 3–5 years. Overseas retail grew about 80% in H1, but it is expected to be only 4–5% of revenue for the full year.
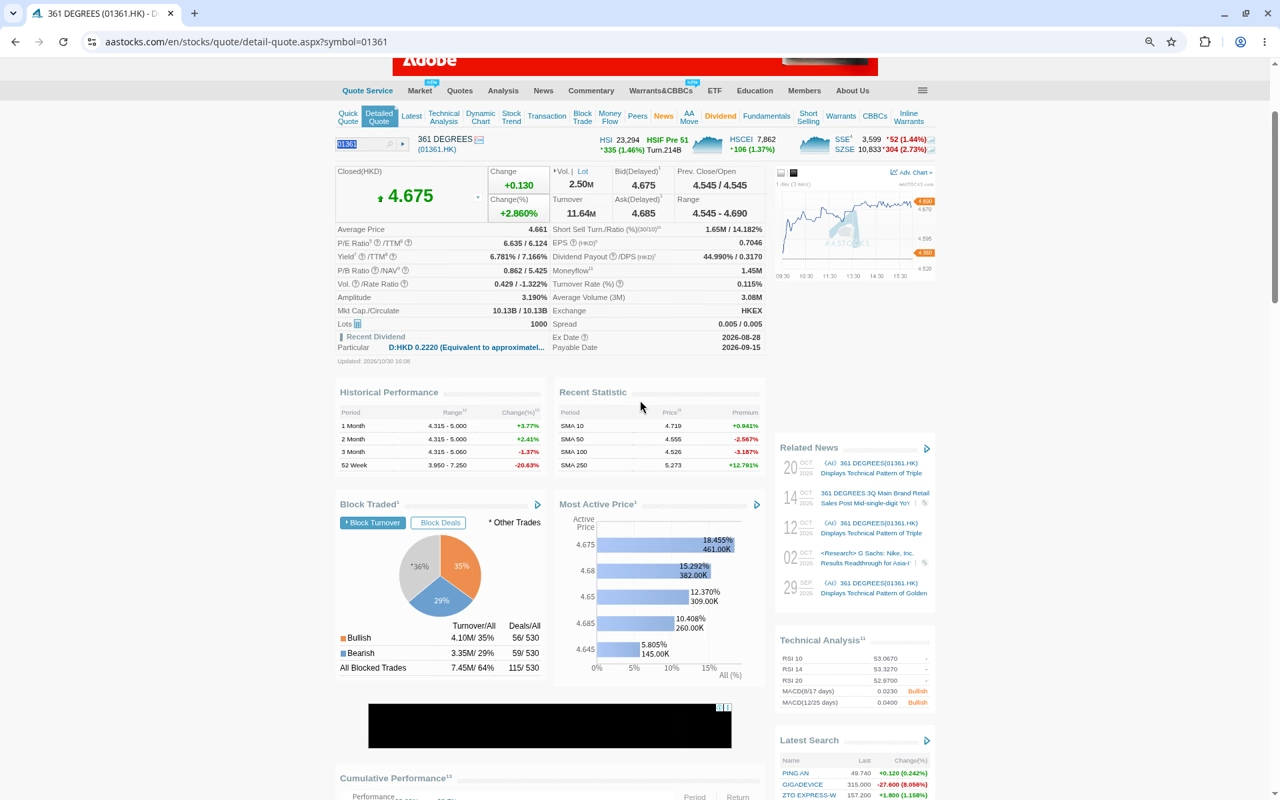
- Friday close (AASTOCKS, 30 Oct 2026 16:08 HKT). Last HK$4.675, open/prev close 4.545, day range 4.545–4.690, volume 2.50M, turnover HK$11.64M. Market Closed.
Why the super-store number matters more than the store count
Store openings are easy to count and easy to over-read. In a crowded market, the real risk for a sportswear brand is fighting rivals for the same customers until the only lever left is the discount. A 75% new-customer share at the super stores suggests 361 is widening its customer base, not just moving existing customers between channels. Tier-1 and tier-2 mall space is expensive, but if it brings in people who were not 361 customers before, it counts as investment rather than cost.
The discount data backs this up. Basketball was the most competitive category in Q3 and international brands were marking down harder, yet 361’s offline discount moved only from about 29% to about 30% off, and inventory stayed at 4.5–5x sales. Commentary notes read this as a company that is not buying sales with price. The real warning would be heavy markdowns to clear stock in Q4.
Overseas: an option, not the thesis
The overseas story gets the market excited: a former Nike executive has joined, 361 has sponsored five straight Asian Games, and it had a booth at the Berlin Marathon. But at 4–5% of revenue, even a doubling next year adds only a few percentage points to group sales. Treat it like a call option: worth something, but don’t count on too much.
Policy tailwind, with a lag
At the end of September, the State Council General Office issued guidance on using sports events to boost consumption (5 areas, 17 tasks). It includes co-branded and licensed event merchandise and faster upgrades of smart wearables. July’s national fitness plan aims to lift regular exercise participation to 40% and sports venue area per person from 3.11 to 4 square metres. More venues and events should mean more shoe sales over time, but policy usually takes 18 months or more to show up in retail sales.
361 Degrees 01361 stock analysis: valuation and key numbers
| Metric | 361 Degrees (01361) |
|---|---|
| Last price (30 Oct 16:08) | HK$4.675 |
| Day change | +HK$0.130 (+2.860%) |
| Prev close / open | HK$4.545 / HK$4.545 |
| Day range | HK$4.545 – 4.690 |
| 52-week range | HK$3.950 – 7.250 |
| Market cap | HK$10.13B |
| P/E / TTM P/E (EPS 0.7046) | 6.635x / 6.124x |
| P/B (NAV HK$5.425) | 0.862x |
| Dividend yield / TTM / DPS | 6.781% / 7.166% / HK$0.317 |
| Payout | 44.99% |
| SMA 10 / 20 / 50 | 4.719 / 4.605 / 4.555 |
| SMA 100 / 250 | 4.526 / 5.273 |
| RSI 14 | 53.3 |
| MACD (12,26) / signal / div | 0.042 / 0.049 / −0.007 |
| Volume / turnover | 2.50M / HK$11.64M |
| Commentary and forecast checkpoints | Figure |
|---|---|
| Share price when Q3 update was released | HK$4.6 – 4.9 |
| Forecast P/E (consensus-style) | 5.46x |
| Forecast P/B | 0.71x |
| Payout (maintained) | ~45% |
| Forecast dividend yield | ~8.25% |
| Relative-strength screen | Among the ~5.2% of stocks classed “strong”; RS score 60 |
| 1-month performance vs Hang Seng Index | +13.7 ppt |
| Commentary stance | Risk-reward favourable; no target price |
What the numbers tell us (our analysis):
- Trailing vs forward. AASTOCKS shows 6.6x P/E (TTM 6.1x) on reported earnings. The commentary’s 5.46x is a forecast, which assumes earnings keep growing. Either way, it is a single-digit multiple.
- Yield: 6.8% now, ~8% forecast. AASTOCKS shows 6.78% (TTM 7.17%) on DPS HK$0.317 with a ~45% payout. The ~8.25% is the commentary’s forecast yield and is not an AASTOCKS figure. Even with zero earnings growth, a yield near 7% is hard to find in Hong Kong.
- Below book. P/B 0.86x (the forecast is 0.71x) for a company whose sales are still growing while peers shrink.
- Small cap, thin trading. A market cap of HK$10.1B and turnover of about HK$11.6M a day mean liquidity is a real constraint for larger buyers.
Technical analysis: back above the 20-day line
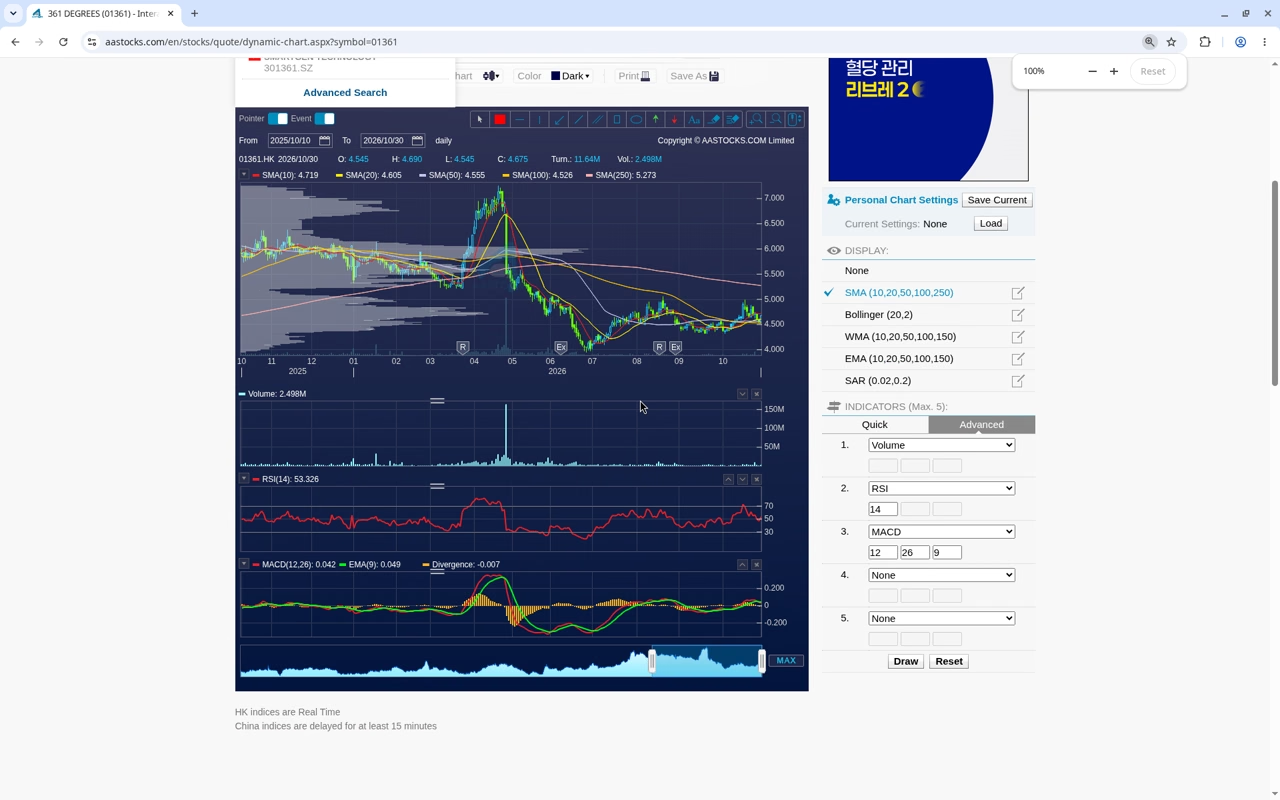
The AASTOCKS one-year daily chart (10 Oct 2025 to 30 Oct 2026) shows a spike to about HK$7.25 in April/May, a sharp drop and a low of about HK$3.95 in late June/July, and then a base in the HK$4.3–5.0 range. Friday’s close of 4.675 sits above SMA20 4.605, SMA50 4.555 and SMA100 4.526, but just below SMA10 4.719 and well below SMA250 5.273.
- Momentum is neutral to positive. RSI(14) is 53.3. MACD (0.042) is just under its signal line (0.049), a small negative divergence of −0.007, so the trend is flattening, not turning down.
- Support. HK$4.53–4.61 (SMA100, SMA50 and SMA20 bunched together), then the Friday low/open at 4.545, then the HK$3.95 52-week low.
- Resistance. HK$4.69–4.72 (day high and SMA10), then the ~HK$5.0 ceiling of the range, then HK$5.27 (SMA250). A close above the 250-day line would confirm a re-rating.
Bull case vs bear case
Bull case
- Retail grew while ANTA brand, FILA, Li Ning and Xtep fell or were guided lower.
- 75% of super-store customers are new, and the full-year store target was reached early.
- Discounts and inventory are stable, with no price war.
- About 6.6x P/E, 0.86x book and a 6.8% yield (TTM 7.2%), with a ~8.25% forecast in commentary.
- A relative-strength screen ranks it among the strongest ~5% of stocks; it is up 13.7 ppt vs the HSI over a month.
- The State Council sports-consumption guidance and the fitness plan support demand in the medium term.
Bear case
- RMB risk: earnings are in RMB and the shares trade in HKD, so a weaker yuan can make “cheap” an illusion.
- High base: the main brand grew double digits in Q3 last year. If Q4 slows to low-single digits, it becomes a demand problem.
- Consumer stocks are out of favour, and a stock can stay range-bound for a long time.
- Overseas is still only 4–5% of revenue.
- Low liquidity, and the price is still below SMA250.
Levels to watch
- HK$3.95 (52-week low). A break would void the base.
- HK$4.53–4.61 (SMA100/50/20 cluster). The key trend support.
- HK$4.69–4.72 (day high / SMA10). The first hurdle.
- ~HK$5.0 (range top). A breakout would open up the re-rating.
- HK$5.27 (SMA250). Trend confirmation.
- Fundamentals. Q4 retail growth (mid-single digit vs low-single digit), discount depth, the RMB and the final dividend.
The DimSumInsider take
361 Degrees is a cheap, high-yield consumer name that is outgrowing its peers. Investors are also getting a small overseas option on top. The data that matters is the 75% new-customer share at super stores and a discount that barely moved in a brutal quarter. At roughly 6.6x trailing earnings and 0.86x book, with a yield near 7%, the market is pricing it as an ex-growth name. Our approach: accumulate on dips into the HK$4.53–4.61 moving-average cluster, add on a close above HK$5.0, and cut if HK$3.95 breaks. Watch the Q4 update closely, because low-single-digit growth would weaken the thesis.
FAQ
How did 361 Degrees’ Q3 retail sales compare with peers?
Main-brand and kids offline retail grew at a mid-single-digit rate, and e-commerce at a mid-to-high single-digit rate. The ANTA brand fell by a mid-single digit, FILA by a low-single digit, and Li Ning and Xtep were expected to decline slightly.
What are 361 Degrees super stores?
They are large-format stores. 21 opened in Q3, bringing the mainland total to 208, and the full-year target was reached early. About 75% of their customers are new to the brand, up from about 65%.
What is 361 Degrees’ dividend yield?
AASTOCKS shows 6.781% (TTM 7.166%) on DPS of HK$0.317 with a ~45% payout, as of 30 Oct 2026 16:08 HKT. Market commentary notes forecast a yield of about 8.25%.
What are the key 361 Degrees valuation numbers?
At HK$4.675 (AASTOCKS, 30 Oct 2026, market Closed): P/E 6.635x (TTM 6.124x), P/B 0.862x, market cap HK$10.13B. Consensus-style forecasts put the forward P/E at about 5.46x and P/B at 0.71x.
What levels matter for 01361?
Support is at HK$4.53–4.61 (SMA100/50/20), then HK$4.545, then the 52-week low of HK$3.95. Resistance is at HK$4.69–4.72, then about HK$5.0, then HK$5.27 (SMA250).
Disclaimer: For information only. Based on public market commentary notes, company operating updates as reported, and AASTOCKS data as of 30 Oct 2026 16:08 HKT (market Closed); data may be delayed. Forecast figures are estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.