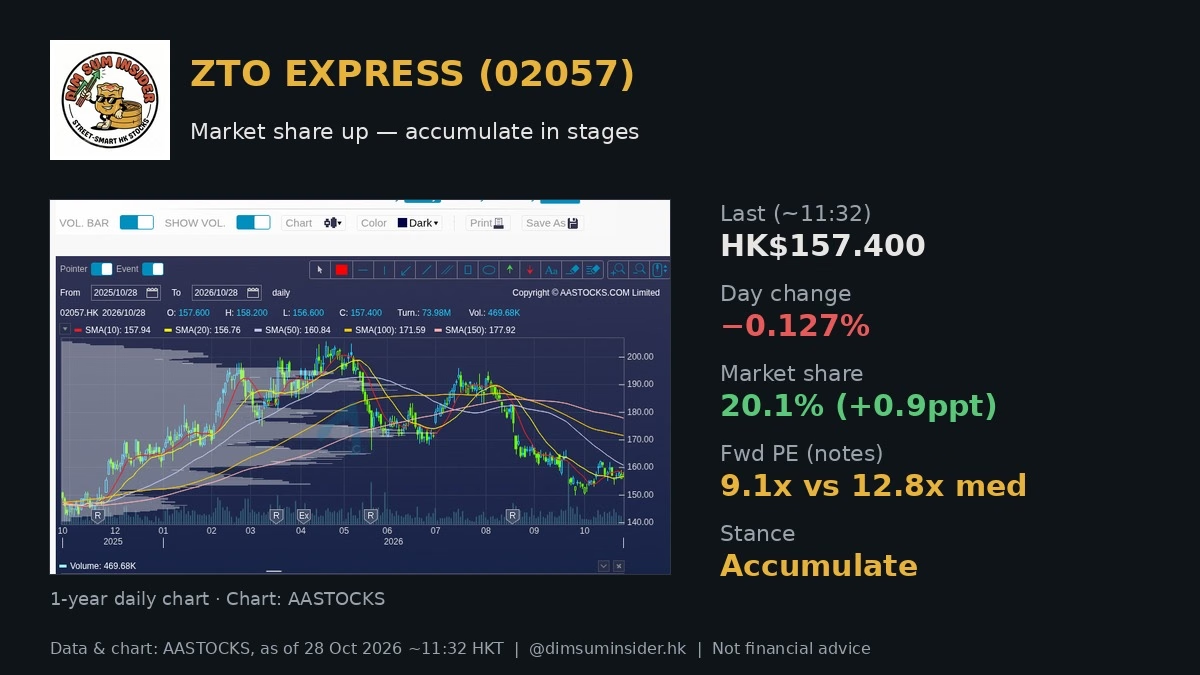
ZTO Express (02057) — English name ZTO EXPRESS-W on AASTOCKS — traded near HK$157.400 mid-session on 28 Oct (−0.200 / −0.127%), after yesterday’s close at HK$157.60. This ZTO Express 02057 stock analysis asks the alpha question: with market share at 20.1% (+0.9ppt), H1 revenue +22.5% and profit +31.5%, and forward PE around 9.1x versus a five-year median of 12.8x, is the still-intact downward channel a stage-accumulate setup — or just more overhead supply waiting above?
Market commentary notes say valuation is reasonable enough to accumulate in stages (分段吸納), citing share gains above industry volume growth, ASP lift, unit-cost deflation, and a forward multiple roughly 0.8 standard deviations below the five-year PE median.
The news in brief
- Industry still growing, but slower (State Post Bureau, first 9M 2026). National express volume 151.3bn pieces (+4.3% YoY); industry revenue RMB 1.16tn (+7.2%). Inter-city 1371.8億件 = 137.18bn (+5.4%), about 90.7% of volume; same-city 110億件 = 11.0bn (−7.3%); intl / HK-Macau-Taiwan 31.2億件 = 3.12bn (+2.7%). Context: Jul 2025 price-law draft / anti-involution push; fee hikes and a stop to low-price market grabs; average express prices stabilized/rose from 2025 Q3 — a shift from pure price-war scale toward value, digital, green, and network intensity.
- ZTO footprint (end-Jun 2026). Roughly 6,000 direct network partners; >31,000 pickup/delivery outlets; ~100,000 end stations; 92 sorting centers; 782 automated sorting lines; >3,600 trunk routes; >10,000 trunk vehicles; warehousing >2m sqm; coverage across all counties and 97% of townships, with overseas extension.
- H1 2026 (RMB, 億 check). Revenue 278.3億 = RMB 27.83bn (+22.5% YoY) — express services 262.1億 (+24.2%), freight forwarding 3.7億 (+84.1%), materials 12億 (+0.5%). Parcel volume 201.54億件 = 20.154bn (+9.6%) — above industry average. Unit ticket / ASP +12.9%. Market share 20.1%, +0.9ppt. Direct-customer revenue +75.4%. Gross margin 25.9% (+0.2ppt). Unit transport cost −8.1%; trunk cost ratio −5ppt; sorting-center opex ratio −3ppt; S&A expense ratio −1.1ppt. Net profit 51.7億 = RMB 5.17bn (+31.5%). Operating cash flow ~73.5億 = RMB 7.35bn (+62.3%). Automated sorting lines +92 vs H1 2025.
- Technical (commentary). Price still in a downward channel; momentum energy negative; outperformed HSI. If it breaks the channel top, overhead supply is limited (“上方籌碼少”) and a rally can sustain.
- Valuation (commentary). Five-year PE median 12.8x; forward PE 9.1x, about 0.8 SD below median — valuation reasonable; conclusion: accumulate in stages at current levels.
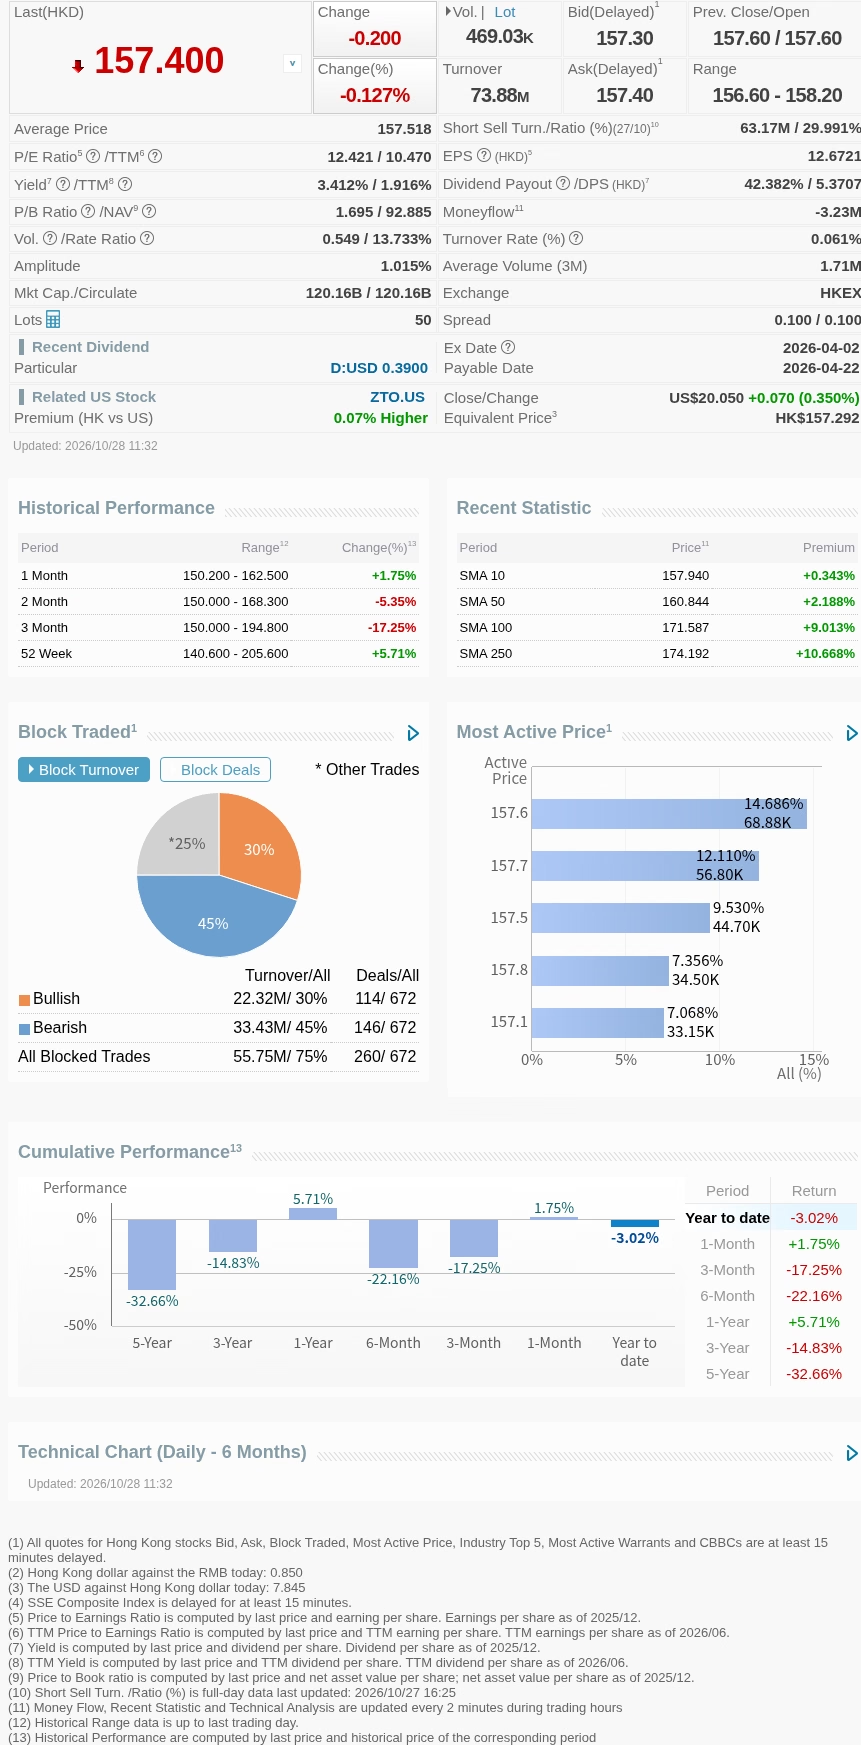
- Wednesday tape (AASTOCKS, updated 28 Oct 2026 ~11:32 HKT). Last HK$157.400 (−0.200 / −0.127%), prev 157.60, open 157.60, day 156.60–158.20. Market still open/moving; cite AASTOCKS and the timestamp. Related US ADR ZTO.US US$20.05; HK premium about 0.07%.
Why market share and unit economics still matter
ZTO is a classic China ecommerce express name: network partners, automated sorting, trunk fleets, and a rising direct-customer mix. Commentary’s point is not that the industry is booming at 20%+ — it isn’t (volume +4.3%) — but that ZTO is still taking share, lifting ASP, and cutting unit transport cost at the same time. That combination — volume above industry, ASP +12.9%, unit transport cost −8.1%, GPM 25.9% — is how you get profit +31.5% and OCF +62.3% while the sector cools from price-war mode into a more disciplined fee environment.
The valuation overlay is patience, not chase: forward PE 9.1x vs a five-year median 12.8x (~0.8 SD below) is the “reasonable / stage accumulate” frame. Technically the stock is still inside a downward channel and has underperformed its own May highs near the HK$205 area, even as it has outperformed the HSI on the way down. That is a margin-of-safety plus share-gain story after a correction — not a momentum breakout until the channel top breaks.
What still has to go right
- Share gains stick. 20.1% (+0.9ppt) has to keep compounding as industry volume growth stays mid-single-digit.
- ASP and cost discipline hold. Anti-involution fee stability plus further automation (sorting lines +92 YoY) need to protect the 25.9% GPM.
- Channel break confirms. A clean break of the downward-channel top, with limited overhead supply as the notes argue, is the technical unlock; until then this is staged buying into a still-bearish structure.
ZTO Express 02057 stock analysis: valuation and key numbers
| Metric | ZTO Express (02057) |
|---|---|
| Last price (28 Oct ~11:32) | HK$157.400 |
| Day change | −HK$0.200 (−0.127%) |
| Prev close / open | HK$157.60 / HK$157.60 |
| Day range | HK$156.60 – 158.20 |
| 52-week range | HK$140.600 – 205.600 |
| Market cap / circulate | HK$120.16B / 120.16B |
| P/E / TTM P/E (EPS 12.672) | 12.421x / 10.470x |
| P/B (NAV 92.885) | 1.695x |
| Dividend yield / TTM / DPS | 3.412% / 1.916% / HK$5.3707 |
| Payout | 42.382% |
| SMA 10 / 20 / 50 | 157.940 / 156.76 / 160.844 |
| SMA 100 / 250 | 171.587 / 174.192 |
| RSI 14 | 46.768 |
| MACD (12,26) / signal / div | −0.950 / −1.402 / 0.452 |
| Volume / turnover | 469.03K / HK$73.88M |
| Short-sell ratio (27/10, full day) | 29.991% |
| Operating / commentary checkpoints | Figure |
|---|---|
| Industry 9M vol / rev | 151.3bn pcs (+4.3%) / RMB 1.16tn (+7.2%) |
| H1 revenue / YoY | RMB 27.83bn / +22.5% |
| H1 volume / ASP | 20.154bn pcs (+9.6%) / ASP +12.9% |
| Market share | 20.1% (+0.9ppt) |
| Gross margin | 25.9% (+0.2ppt) |
| Unit transport cost | −8.1% |
| H1 net profit / OCF | RMB 5.17bn (+31.5%) / RMB 7.35bn (+62.3%) |
| Direct-customer rev | +75.4% |
| 5y PE median → fwd PE | 12.8x → 9.1x (~0.8 SD below) |
| Stance (commentary) | Accumulate in stages |
What the numbers tell us (our analysis):
- Multiple is the accumulate argument. AASTOCKS trailing P/E 12.4x / TTM 10.5x sits next to commentary’s fwd 9.1x vs 12.8x median — this is a below-median quality logistics name, not a deep single-digit yield trade.
- Yield is modest, not the floor. Trailing yield 3.41% (TTM 1.92%, DPS HK$5.37, payout ~42%) helps a little but is not the thesis.
- Price is pinned under the longer SMAs. Last 157.40 is just under SMA10 157.94, slightly above SMA20 156.76, and well below SMA50 160.84 / SMA100 171.59 / SMA250 174.19 — medium-term stack still bearish.
- RSI is neutral, not washed-out. RSI(14) 46.8 is mid-band — room for either a grind toward the channel top or another shakeout.
- MACD is negative but improving. MACD −0.950 vs signal −1.402 (div +0.452) shows the histogram turning less bearish even while both lines sit under zero.
- Shorts are elevated. Full-day short-sell ratio ~30% (27 Oct) can fuel either a squeeze on a channel break or another flush if the industry softens.
Technical analysis: still in the channel, HSI-relative strength
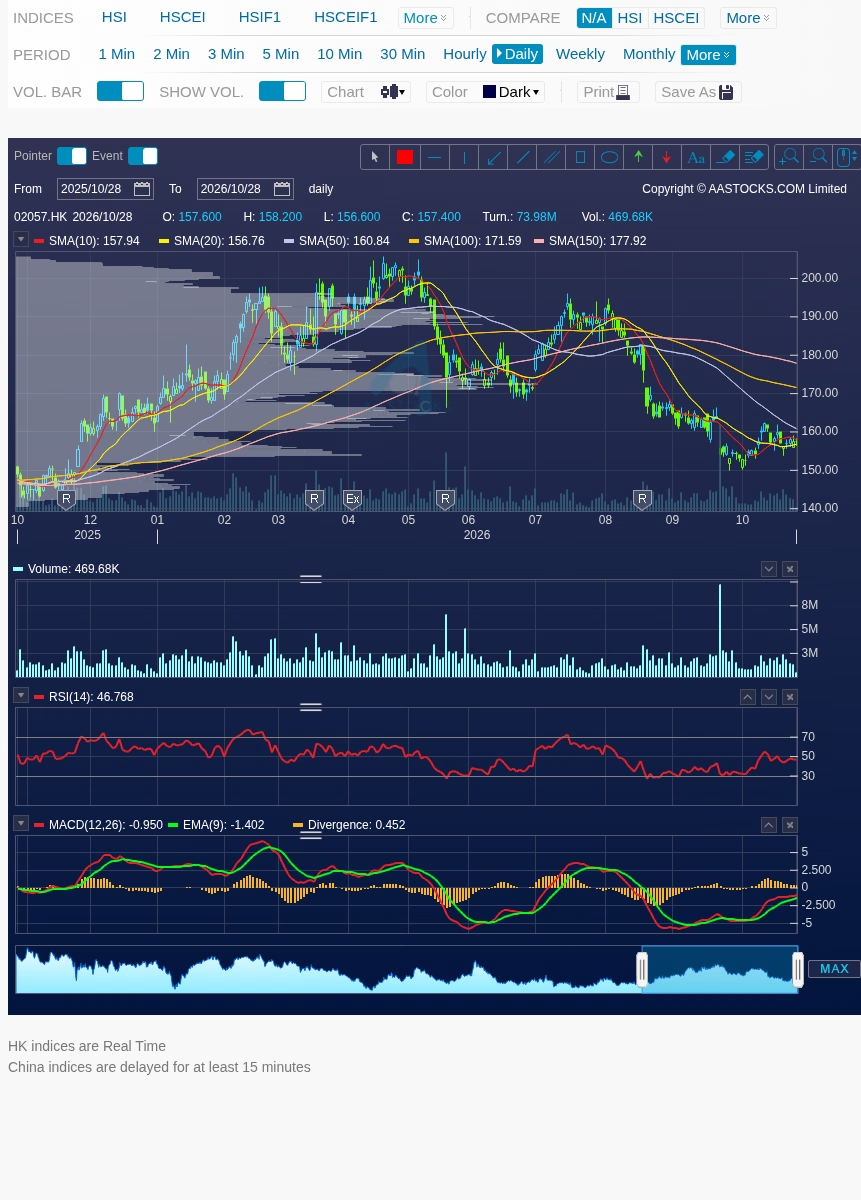
The one-year AASTOCKS chart is a round trip from the ~HK$205 May area into the mid-150s, with a late-year bounce off the ~HK$140–145 zone. Price is still inside the commentary’s downward channel; the notes argue a break of the channel top meets limited overhead supply, which is the technical unlock for a sustained rally. Relative to the Hang Seng, the stock has outperformed even while absolute momentum stayed soft.
- First job: hold SMA20, then reclaim SMA10 / SMA50. Near-term pivot is HK$156.76 (SMA20) and HK$157.94 (SMA10); next resistance HK$160.84 (SMA50), then the heavier SMA100 / SMA250 band around 171–174.
- Channel / commentary unlock. A break of the downward-channel top is the notes’ condition for a durable rally given “上方籌碼少.”
- Support. Day low HK$156.60, then the September base toward HK$140.60 (52w low). A sustained break of the mid-150s would pause the stage-accumulate sizing for us until a new base forms.
- RSI 46.8 is neutral fuel; MACD divergence +0.452 is the early constructive tell, not yet a trend flip.
Levels: first resistance HK$157.94 (SMA10) and HK$160.84 (SMA50); heavier supply HK$171–174 (SMA100/250); support HK$156.60 (today’s low) then the HK$140–145 base.
Bull case vs bear case
Bull case
- Market share 20.1% (+0.9ppt) with volume +9.6% vs industry +4.3% — still taking share in a slower market.
- ASP +12.9%, unit transport cost −8.1%, GPM 25.9%, profit +31.5%, OCF +62.3% — unit economics compounding.
- Direct-customer revenue +75.4% lifts mix toward higher-value clients and reverse logistics.
- Forward PE 9.1x vs five-year median 12.8x (~0.8 SD below) — commentary’s stage-accumulate valuation frame.
- Outperformed HSI inside the channel; MACD histogram improving (div +0.452); channel-top break = limited overhead supply per notes.
Bear case
- Price still below SMA50 / SMA100 / SMA250; absolute structure remains a downward channel.
- Industry volume growth only +4.3% — any re-acceleration of price competition would hit ASP and GPM.
- Short-sell ratio near 30% and a soft RSI mid-band leave room for another flush before any channel break.
- Trailing yield ~3.4% is not a hard floor; ADR/H-share basis can wobble (HK premium only ~0.07% today).
- “Accumulate in stages” fails if the mid-150s base breaks toward the HK$140 52w low without a new fundamental offset.
Levels to watch
- HK$156.60–156.76 (day low / SMA20). Near-term floor — hold vs break decides whether staged buying has a tape floor today.
- HK$157.94 (SMA10). First reclaim for any short-term bounce to look real.
- HK$160.84 (SMA50). Intermediate trend repair and likely channel-adjacent resistance.
- HK$171.59 / 174.19 (SMA100 / SMA250). Heavier moving-average supply after the May–Sep slide.
- Downward-channel top. Commentary’s breakout condition — limited overhead supply if cleared.
- Industry ASP / anti-involution fees and share vs peers. Fundamental swing factors behind the 9.1x accumulate thesis.
The DimSumInsider take
ZTO Express is a share-gaining China express name with below-median forward PE after a correction from the ~HK$205 highs into the mid-150s — not a crushed single-digit P/E yield play. The fundamental print (H1 rev +22.5%, volume +9.6%, share 20.1%, ASP +12.9%, unit transport −8.1%, profit +31.5%) supports the commentary’s stage accumulate frame at fwd PE 9.1x vs 12.8x median, while the technical still asks for patience inside a downward channel. Our approach: treat HK$156.60–160.84 as the prove-it band for staged entries, keep the channel-top break as the confirmation for size-up, and respect open air under the mid-150s toward the HK$140 base. The alpha is buying share gains and unit-cost deflation in stages while the tape decides whether this correction was a re-rating gift or just more channel work.
FAQ
What does ZTO Express (02057) do?
ZTO Express is a Hong Kong-listed China express-delivery and logistics operator with a large partner network, automated sorting, trunk routes, and rising direct-customer / reverse-logistics mix tied to ecommerce. AASTOCKS lists the English name as ZTO EXPRESS-W.
Why are market commentary notes talking about accumulating now?
They flag market share at 20.1% (+0.9ppt), H1 profit +31.5% with ASP and cost gains, a forward PE of 9.1x about 0.8 SD below the five-year median of 12.8x, and a still-intact downward channel that has nonetheless outperformed the HSI — arguing valuation is reasonable for staged buying.
What are the key ZTO Express valuation numbers?
At AASTOCKS ~11:32 HKT on 28 Oct 2026 (HK$157.400): P/E 12.42x, TTM P/E 10.47x, P/B 1.70x, yield 3.41%, market cap HK$120.16B. RSI(14) 46.8; MACD(12,26) −0.950 / signal −1.402 / div 0.452. Commentary forward PE ~9.1x vs 12.8x median.
What levels matter for 02057?
Resistance HK$157.94 (SMA10), HK$160.84 (SMA50), HK$171–174 (SMA100/250), plus the downward-channel top; support HK$156.60 (today’s low) then the HK$140–145 base.
Is this a buy after the H1 beat?
That depends on your risk tolerance. Share gains, ASP/cost leverage, and a below-median forward PE support a staged-accumulate thesis, but the stock is still in a downward channel under the longer SMAs. Use levels; this is not financial advice.
Disclaimer: For information only. Based on public market commentary notes and AASTOCKS data as of 28 Oct 2026 ~11:32 HKT (market still open/moving); data may be delayed. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.