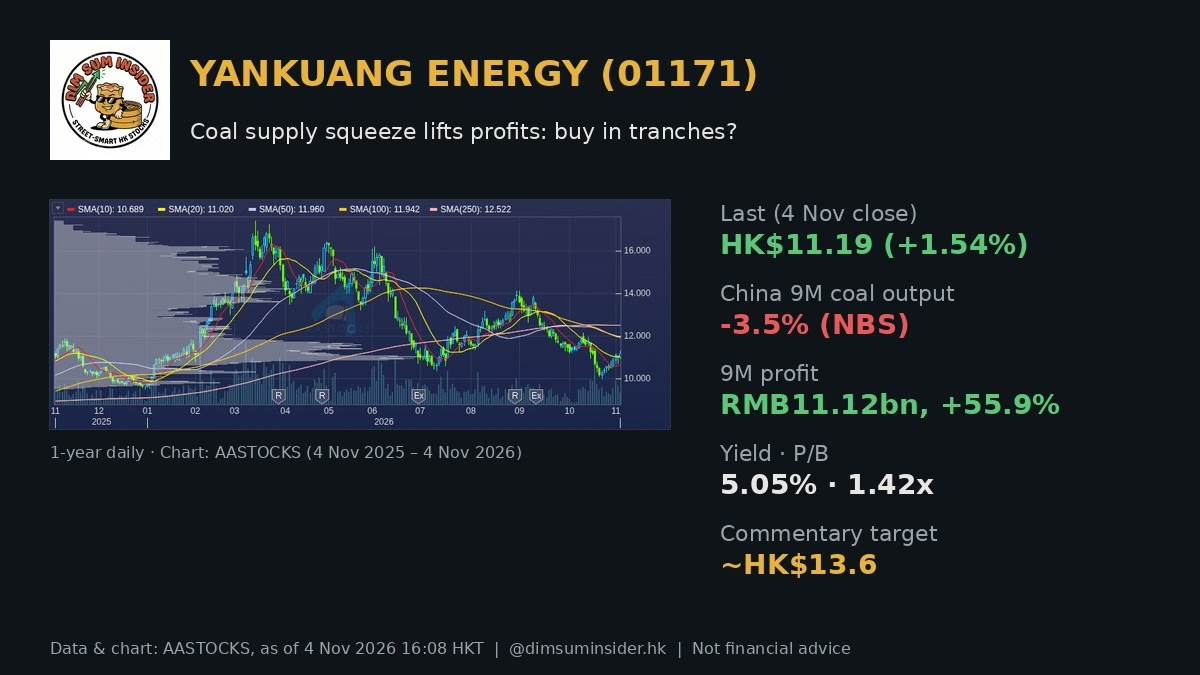
Yankuang Energy (01171), listed as YANKUANG ENER on AASTOCKS, rose 1.54% to HK$11.19 on Wednesday 4 Nov. China’s coal market has tightened: national output is down, prices have climbed for most of the year, and the heating season is starting. This Yankuang Energy 01171 stock analysis looks at whether higher coal and coal-chemical margins, shown in a 55.9% jump in nine-month profit, make the stock worth building into.
Market commentary notes see the valuation as reasonable and suggest accumulating in tranches, with a technical target near HK$13.6. We broadly agree: earnings momentum is strong and the multiple is below its own history, but the share price is still under its 50-, 100- and 250-day averages, so staged buying makes sense.
Key takeaways
- Supply is shrinking. National Bureau of Statistics (NBS) data show China’s above-scale raw coal output was about 3.45bn tonnes in 9M 2026, down 3.5% YoY, after safety inspections and capacity checks idled many mines.
- Prices are up. Market commentary notes say the Qinhuangdao 5,500 kcal thermal coal price moved back above RMB 1,000/t in October for the first time in three years, with a peak year-to-date gain of nearly 50%.
- Industry profits jumped. NBS figures cited in the notes put 9M revenue of coal mining and washing at RMB 2.1trn (+11.9%) and profit at RMB 353.04bn (+57%).
- Yankuang’s 9M print. Revenue RMB 117.5bn (+11.3%), gross margin 33.1% (+3.4 ppt), profit RMB 11.12bn (+55.9%), adjusted profit RMB 8.54bn (+31.1%).
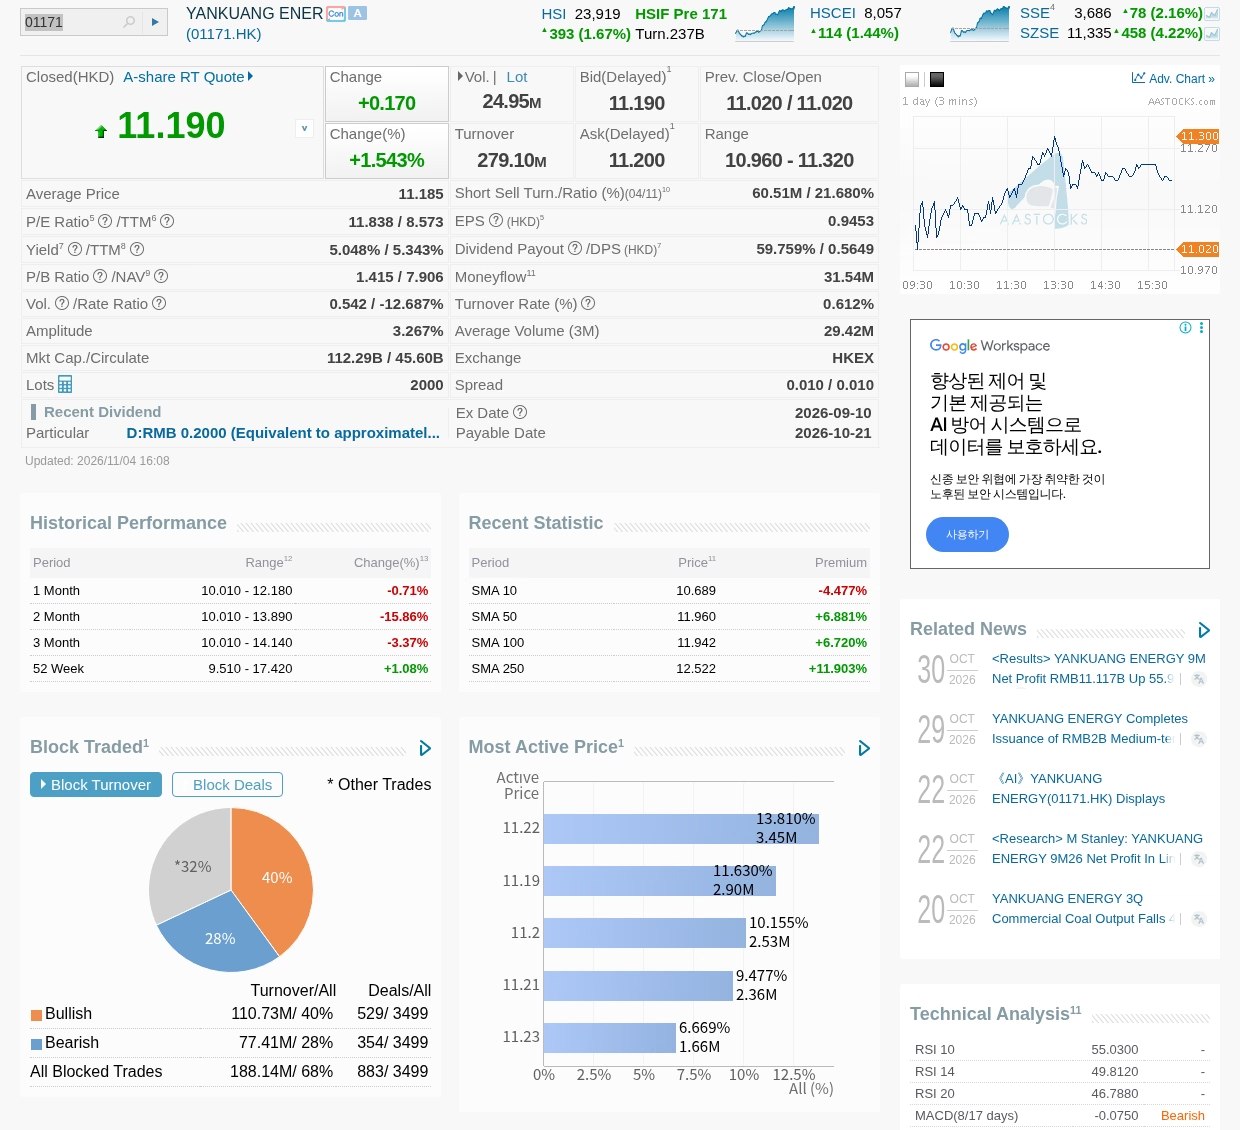
- Valuation. AASTOCKS shows P/E 11.84x (TTM 8.57x), P/B 1.42x and yield 5.05% (TTM 5.34%). Commentary notes estimate a forward P/E of about 5.9x versus a 5-year median of 7x.
- Commentary stance. Valuation reasonable; accumulate in tranches; technical target about HK$13.6.
China coal market: supply contraction meets the heating season
The main driver this year has been supply. NBS data show 9M 2026 above-scale raw coal output of about 3.45bn tonnes, down 3.5% from a year earlier. Safety incidents in core producing regions led to strict safety checks and capacity reviews, and a large number of mines stopped for rectification.
With supply and demand tightly balanced, thermal and coking coal prices have trended higher since the start of the year. Because prices rose much faster than output fell, coal miners’ revenue and profit both expanded: NBS figures for the first three quarters show coal mining and washing revenue of RMB 2.1trn (+11.9%) and profit of RMB 353.04bn (+57%).
Heading into November:
- Demand support. Cold air has hit the mainland, coastal power plants and northern regions have started winter stockpiling, and coal chemicals keep steady demand.
- Supply returning slowly. Mines that were stopped are gradually restarting, and the National Energy Administration has rolled out measures to raise output. September’s output decline narrowed from August, and daily output is back above 12m tonnes.
Our read: the heating-season restocking should hold prices up near term, but recovering supply is the main thing that could cap further gains.
Yankuang Energy 9M 2026 results
Yankuang is a Shandong Energy group subsidiary. It mines and sells coal, makes and sells coal chemicals, and runs logistics, equipment and power businesses. Its mining bases are in Shandong, Shaanxi–Inner Mongolia and Australia, where subsidiary Yancoal Australia (03668) is one of the country’s largest coal exporters.
| Item | 9M 2026 | Change |
|---|---|---|
| Revenue | RMB 117.5bn | +11.3% YoY |
| Coal revenue | RMB 74.6bn (63.5% of total) | +16.4% |
| Coal-chemical revenue | RMB 20.06bn (17.1% of total) | +8.3% |
| Gross margin | 33.1% | +3.4 ppt |
| Profit | RMB 11.12bn | +55.9% |
| Adjusted profit | RMB 8.54bn | +31.1% |
Coal unit economics
| Coal metric | 9M 2026 | Change |
|---|---|---|
| Coal output | 132 Mt | −3% |
| Coal sales | 126 Mt | −0.3% |
| Own-produced coal sales | 120 Mt | −1.3% |
| Average coal selling price | RMB 591.88/t | +16.7% |
| Own-produced coal average price | RMB 587.8/t | +16.8% |
| Coal segment gross margin | 36.1% | +4.8 ppt |
The company managed output to match the market, then raised its coal washing rate to sell more higher-value washed coal. Prices did the work: volumes were flat to slightly lower, but a 16–17% price gain pushed the coal margin up almost 5 points.
Coal-chemical unit economics
| Coal-chemical metric | 9M 2026 | Change |
|---|---|---|
| Product output and sales | — | Slightly lower YoY |
| Average selling price | RMB 3,180/t | +10.5% |
| Unit cost | — | +5.8% |
| Unit gross profit | RMB 938/t | +23.7% |
Using its own coal as feedstock cuts out middlemen and raw-material price risk. Unit costs of key products such as methanol and acetic acid fell sharply YoY according to the notes, though the segment’s overall unit cost rose 5.8%. With prices up 10.5%, unit gross profit rose 23.7%. Yankuang’s coal-chemical base has total capacity of more than 10m tonnes, including China’s first million-tonne indirect coal liquefaction demonstration unit.
Growth projects
- Won the Hongzhun coal mine tender, adding 406m tonnes of quality resources, including scarce high-grade coking coal.
- Mine construction at Youfangliang and Yangjiaping is progressing; the Xinjiang 800,000-tonne olefins project is under full construction.
- Proposed acquisition of Shandong Energy power assets, plus thermal, wind, solar and storage build-out.
Yankuang Energy 01171 stock analysis: valuation
| Metric | Yankuang Energy (01171) |
|---|---|
| Last price (2026/11/04 close) | HK$11.190 |
| Day change | +HK$0.170 (+1.543%) |
| Prev close / open | HK$11.020 / HK$11.020 |
| Day range | HK$10.960 – 11.320 |
| 52-week range | HK$9.510 – 17.420 |
| Market cap / circulating | HK$112.29B / HK$45.60B |
| P/E / TTM P/E | 11.838x / 8.573x |
| P/B (NAV HK$7.906) | 1.415x |
| Dividend yield / TTM | 5.048% / 5.343% (DPS HK$0.5649) |
| Volume / turnover | 24.95M / HK$279.10M |
| Market commentary notes | Figure |
|---|---|
| 5-year median P/E | 7x |
| Forward P/E estimate | ~5.9x |
| Position in band | ~0.4 standard deviation below median |
| Valuation view | Reasonable |
| Strategy | Accumulate in tranches |
| Technical target | ~HK$13.6 (early-September high), ~21.5% above HK$11.19 |
What the numbers tell us (our analysis):
- Earnings are catching up with the price. The AASTOCKS trailing P/E of 8.57x is backward-looking. The ~5.9x forward estimate assumes the higher 2026 earnings run-rate holds, which depends on coal prices.
- Income support. A 5.05% yield (5.34% TTM) pays holders to wait. AASTOCKS lists the latest dividend as RMB 0.20, ex-date 2026-09-10.
- Well off the highs. At HK$11.19 the stock is about 36% below its 52-week high of HK$17.42 and 18% above the HK$9.51 low.
Technical analysis: back above the short-term averages
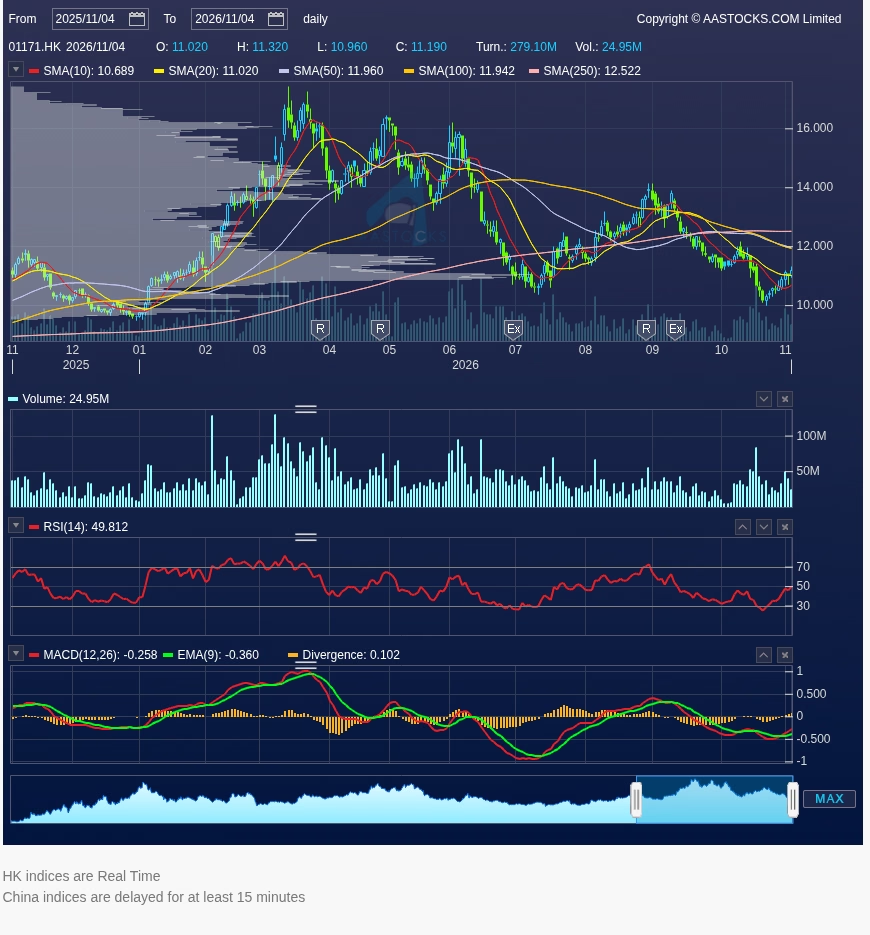
The AASTOCKS one-year daily chart (4 Nov 2025 to 4 Nov 2026) shows a rally to the HK$17.42 high in spring, a slide through the summer, a recovery to around HK$14 in early September, then a drop to near HK$10 in late October. The stock has bounced since.
- Moving averages. The price of 11.19 is above SMA10 10.689 and SMA20 11.020, but below SMA100 11.942, SMA50 11.960 and SMA250 12.522.
- Momentum. RSI(14) is 49.8, neutral. MACD(12,26) is −0.258 against a signal of −0.360 (divergence +0.102), a bullish crossover below zero. Commentary notes also see negative momentum fading and say a break above the top of the falling channel could open a run at the early-September high of about HK$13.6.
- Support. HK$11.02 (SMA20 and prev close), then HK$10.69 (SMA10), then the 1-month low of HK$10.01.
- Resistance. HK$11.32 (day high), then HK$11.94–11.96 (SMA100/SMA50), then HK$12.52 (SMA250), then HK$13.6.
Risks
- Supply comes back. Restarting mines and NEA measures to raise output could cool prices after the heating season.
- Coal price sensitivity. Most of the profit gain came from price, not volume; a price reversal would hit margins quickly.
- Volumes are soft. Coal output fell 3% and coal-chemical volumes slipped in 9M.
- Project and deal risk. Large capex (Hongzhun, Xinjiang olefins, power assets) carries cost and execution risk.
- Trend not yet repaired. The price is still below SMA50, SMA100 and SMA250.
- Estimates can change. Forward P/E and targets are views, not guarantees.
The DimSumInsider take
Yankuang is a direct play on tighter Chinese coal supply, with coal chemicals adding a second margin lever. 9M profit up 55.9% on a 16.7% higher coal price shows the operating leverage. We agree with the commentary notes’ stance: valuation is reasonable and buying in tranches suits a cyclical name. We would add on a close above SMA50 (HK$11.96), treat HK$13.6 as the first target, and reassess below the HK$10.01 October low.
FAQ
Why are China coal prices rising in 2026?
Supply has shrunk. NBS data show 9M above-scale raw coal output down 3.5% to about 3.45bn tonnes after safety checks closed many mines, while heating-season stockpiling adds demand.
What were Yankuang Energy’s 9M 2026 results?
Revenue rose 11.3% to RMB 117.5bn, gross margin rose 3.4 points to 33.1%, profit rose 55.9% to RMB 11.12bn, and adjusted profit rose 31.1% to RMB 8.54bn.
How much does Yankuang make per tonne of coal chemicals?
The average selling price rose 10.5% to RMB 3,180/t, and unit gross profit rose 23.7% to RMB 938/t.
What is Yankuang Energy’s valuation?
According to AASTOCKS as of the 2026/11/04 close: HK$11.19, P/E 11.84x (TTM 8.57x), P/B 1.42x, yield 5.05% and market cap HK$112.29B. Commentary notes estimate a forward P/E of about 5.9x versus a 5-year median of 7x.
What levels matter for 01171?
Support is at HK$11.02, then HK$10.69, then HK$10.01. Resistance is at HK$11.32, then HK$11.94–11.96, then HK$12.52, then HK$13.6.
Disclaimer: For information only. Based on public market commentary notes, company results as reported, NBS data, and AASTOCKS data as of 2026/11/04 16:08 HKT (market Closed); data may be delayed. Forward P/E and targets are forward-looking estimates. DimSumInsider may hold positions not stated here. Consult a licensed financial adviser. This is not financial advice. Do your own research.